

Dear compounders,
In the first part of this series (find it here), I walked through Grab, the first of seven ideas I am lining up as potential homes for the capital that would be freed up if the Ember proposal for Ashtead Technology materializes or if the gap to the offer closes.
Idea number two is a very different animal. It is a former market darling that has lost almost three-quarters of its value in just over two years, and a stock I have passed on for as long as I have been writing about it.
All my prior Novo Nordisk write-ups:
Idea #2: Novo Nordisk
What is the price trying to tell us?
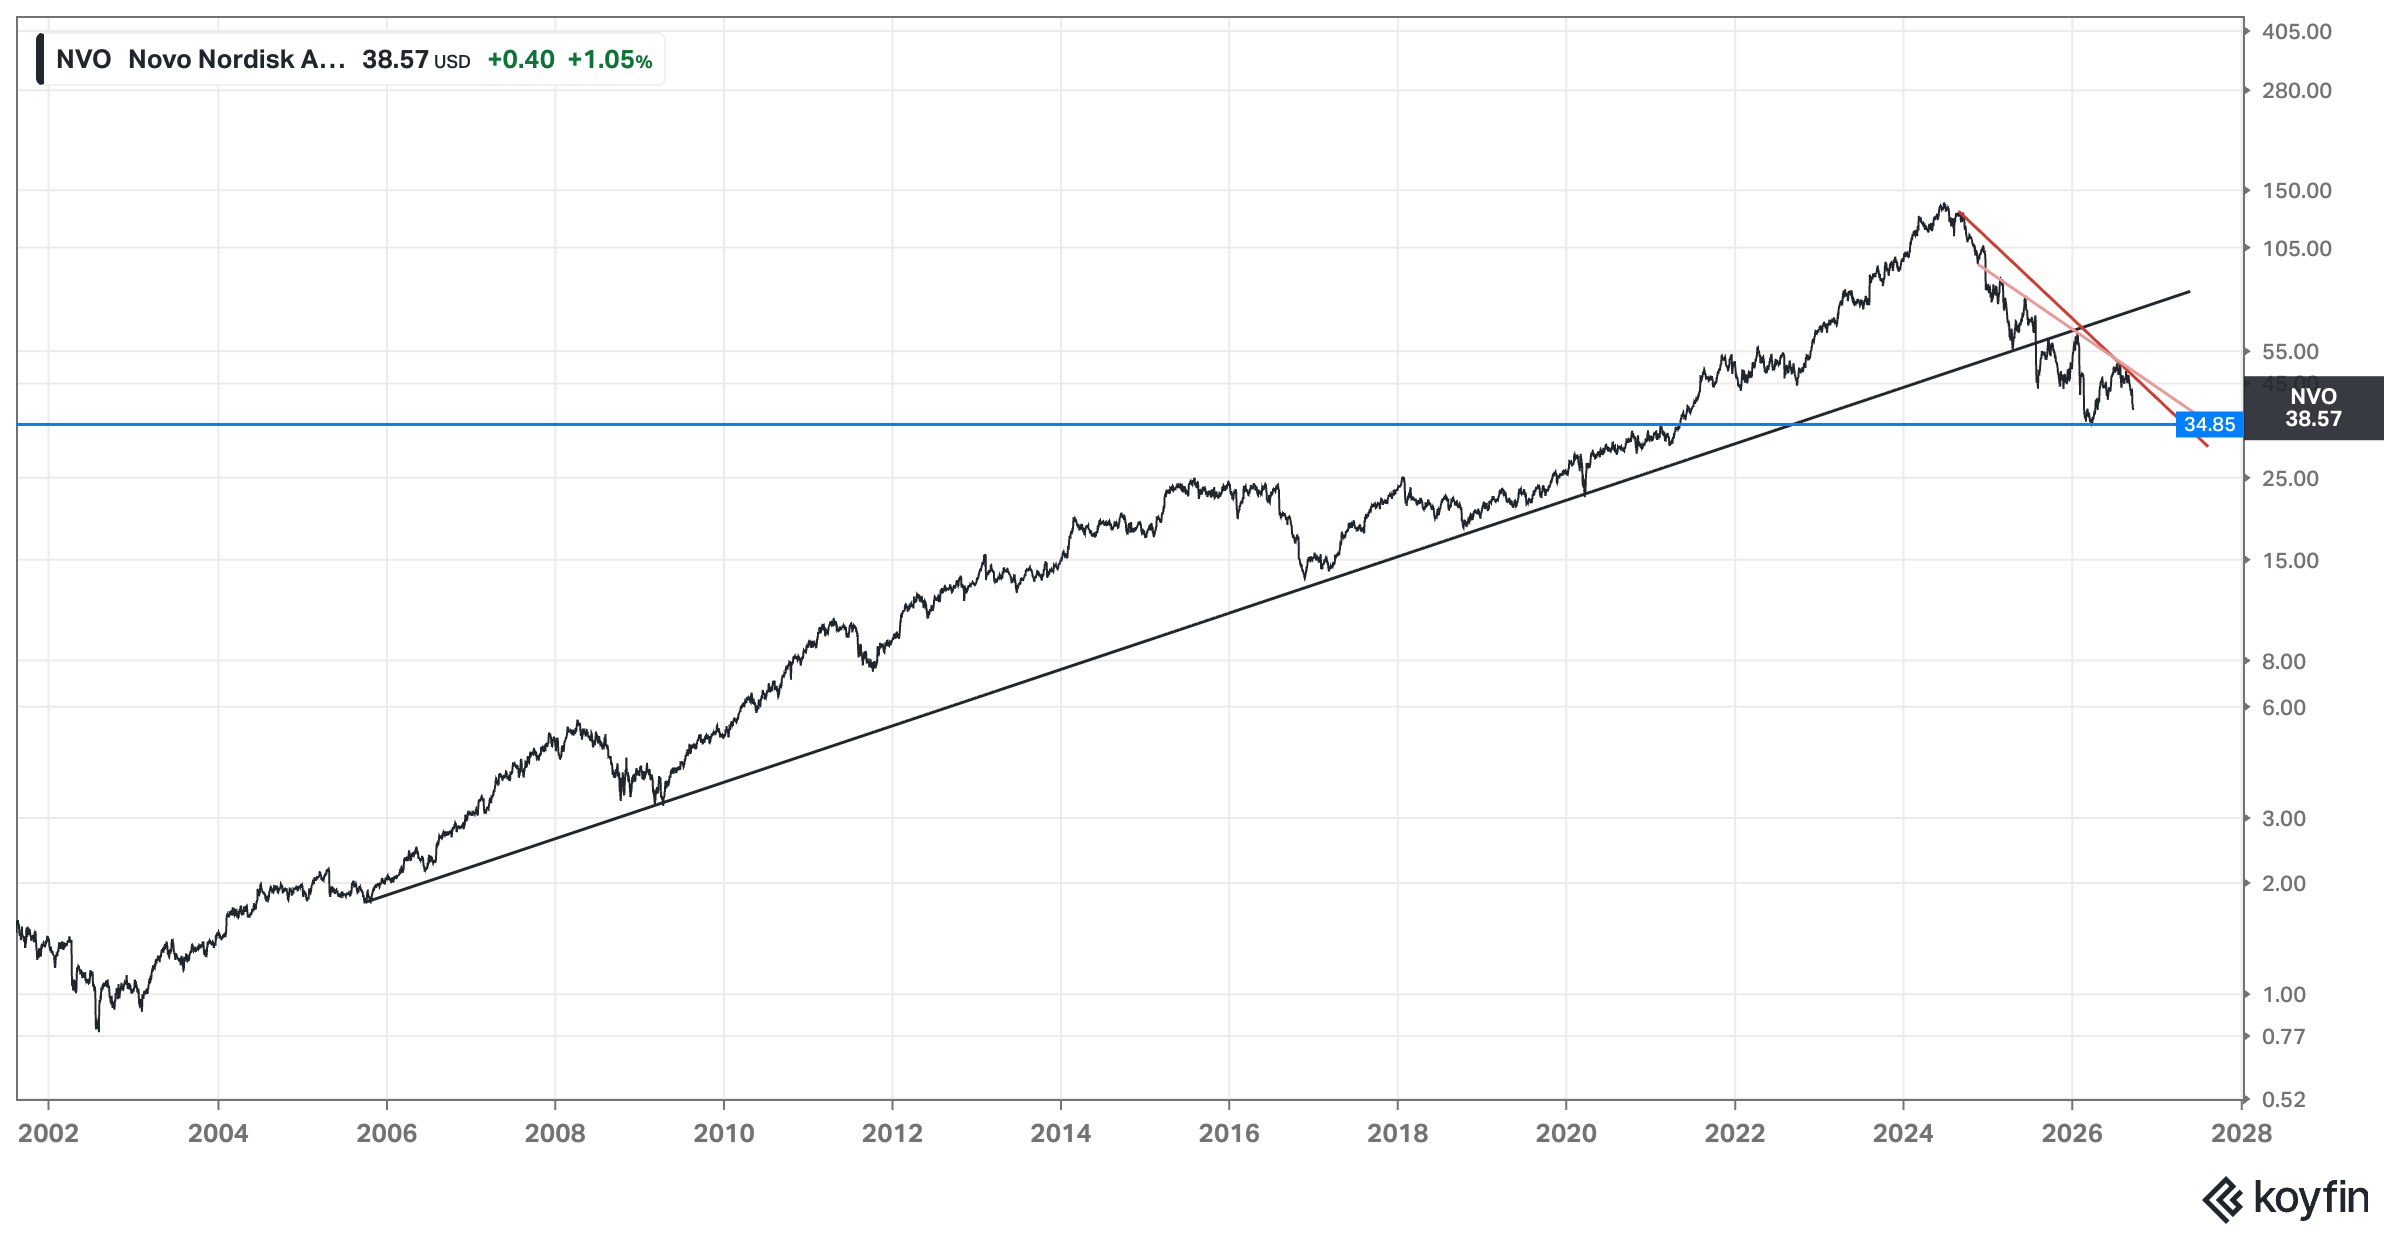
Novo has been in a downtrend since June 2024. The stock is down 72.6% over roughly 2.2 years, which works out to a CAGR of about minus 44%. That is pretty bad, and yet the most important line on this chart is the black one. For almost two decades, Novo respected a long-term uptrend that started in the mid-2000s, and in 2025 it broke that line decisively.
In Part 3 of my framework series, I wrote that the longer and steeper the uptrend, the more violent the reversion when it finally breaks. Novo is a textbook case, right next to Constellation Software and Diageo (and many other recent ones come to mind such as Rollins or Intuitive Surgical). Of the two downtrend lines, the light red one probably carries the stronger signal. It covers a shorter period than the dark red one, but it has five touchpoints compared with just two, and neither line has been broken.
Clear support is hard to find. The only meaningful reference point on the downside is the March 2026 low at $34.85, roughly 10% below the current share price, and it may well get tested soon.
As I explained in Part 3 of my framework series:
Large volume spikes often signal forced behavior – capitulation, de-risking, mandate-driven selling. These are moments when decision-making is less reflective and more reactive.
High volume near peaks = bearish
High volume near troughs = bullish
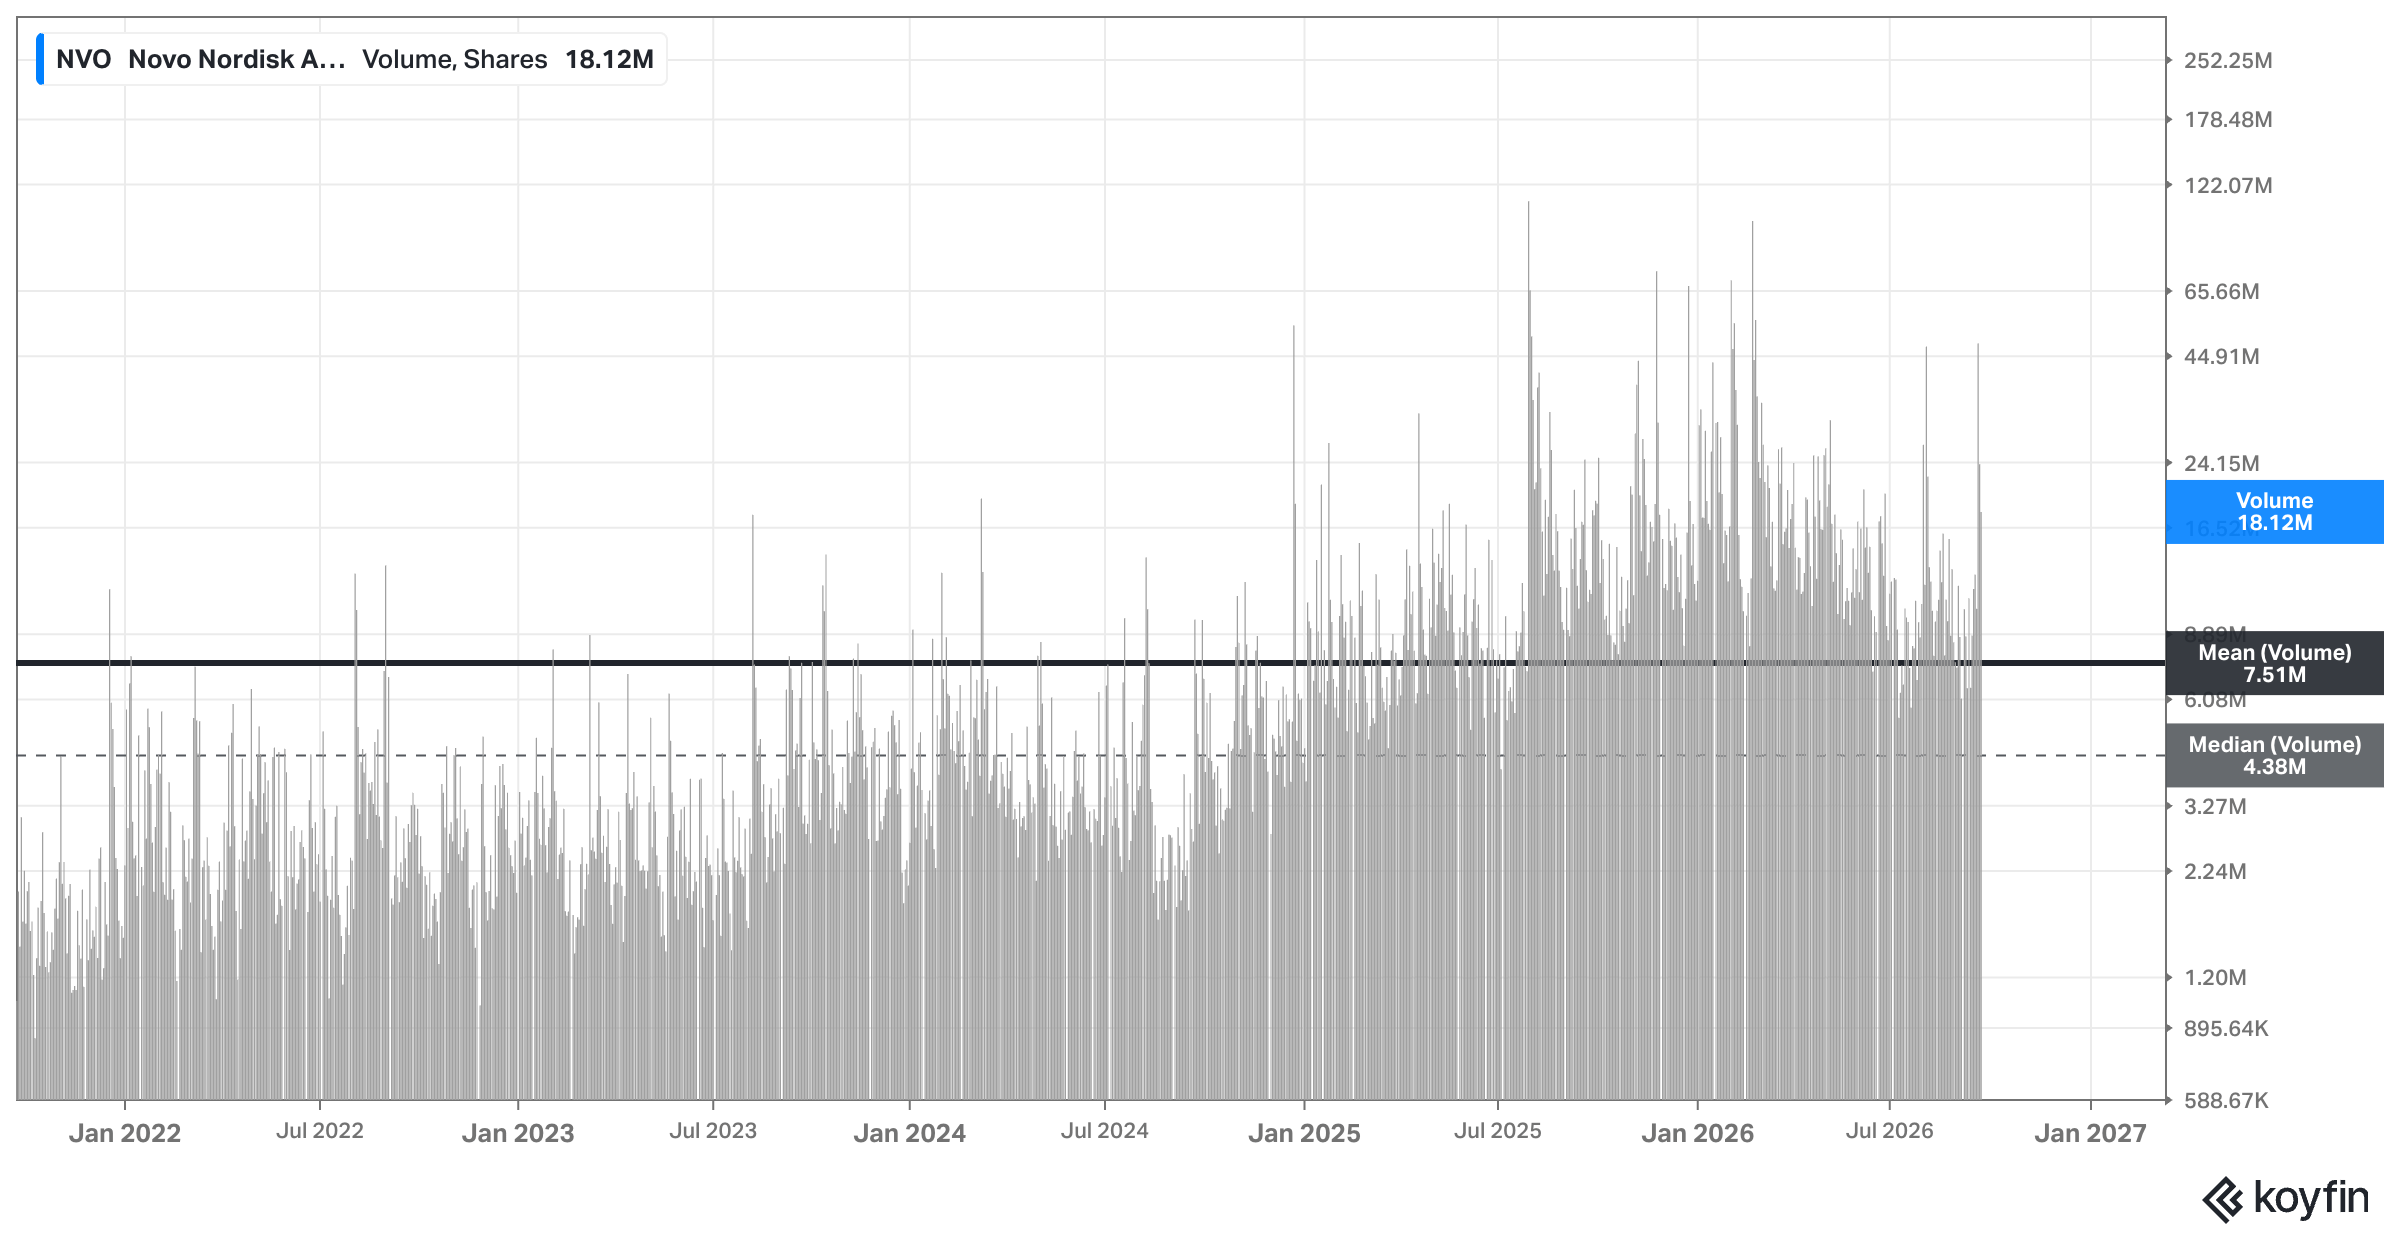
Applied to Novo, the picture is sobering. The stock has traded in heavy volume throughout 2025 and 2026, with daily turnover regularly at several times its long-term average of about 7.5 million shares and multiple clear spikes along the way. More than once, a spike looked like the capitulation that marks a bottom, and more than once Novo went on to make new lows. Investing is tough and technical analysis is just one tool in your toolkit that you need to couple with many other ones and even then you might not perfectly time the lows – but does this mean you shouldn’t try?
Volume has eased somewhat from its early-2026 peaks, but it remains far above pre-selloff levels, and the latest spike in September came on the way down. That tells me the transition in ownership I described in Part 3 of my perception change analysis series (I cannot even pinpoint from whom to whom … long-term owners to those concluding that the embedded expectations at this price make up for the many mistakes of the past?) is not finished yet.
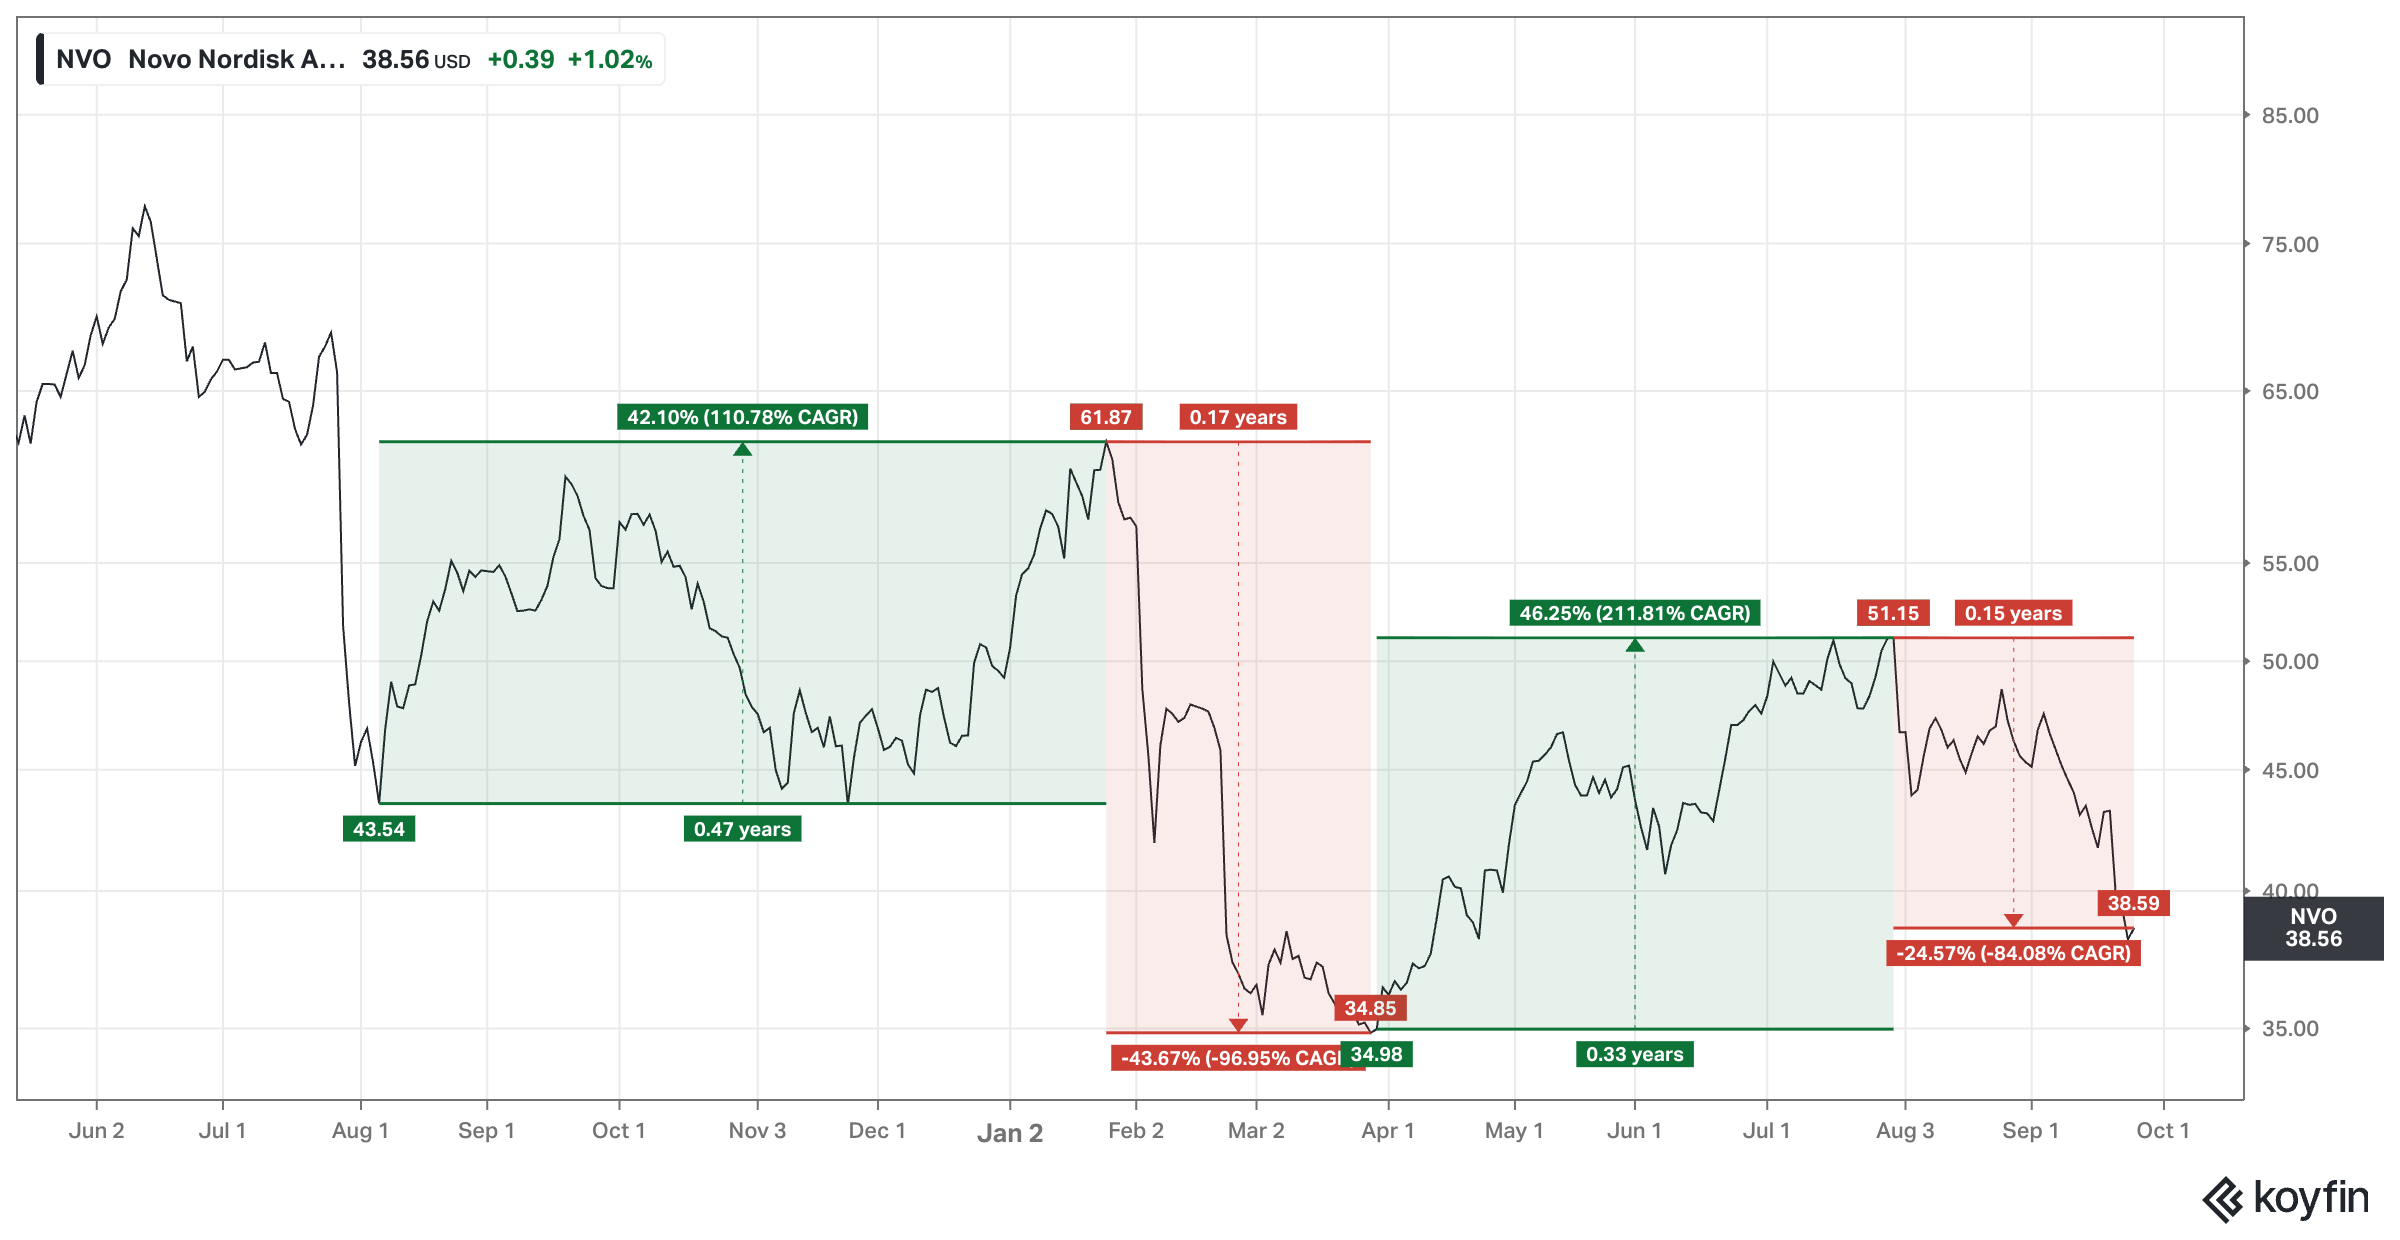
Novo has also been incredibly volatile. Since August 2025, the stock has gone through two full bull and bear cycles, rallying 42% and 46% within a few months each time and then giving back 44% and 25% even faster. Bulls take the stairs, bears ride the elevator, and Novo illustrates the saying almost perfectly.
Interestingly, the stock trades only about 11% below its August 2025 low of $43.54, and for more than a year it has been stuck in a range between roughly $35 and $62.
In the language of my framework, that looks like the early shape of a sideways base, although an unusually wild one.
Is sentiment bombed out, or is there still some air left to let out?
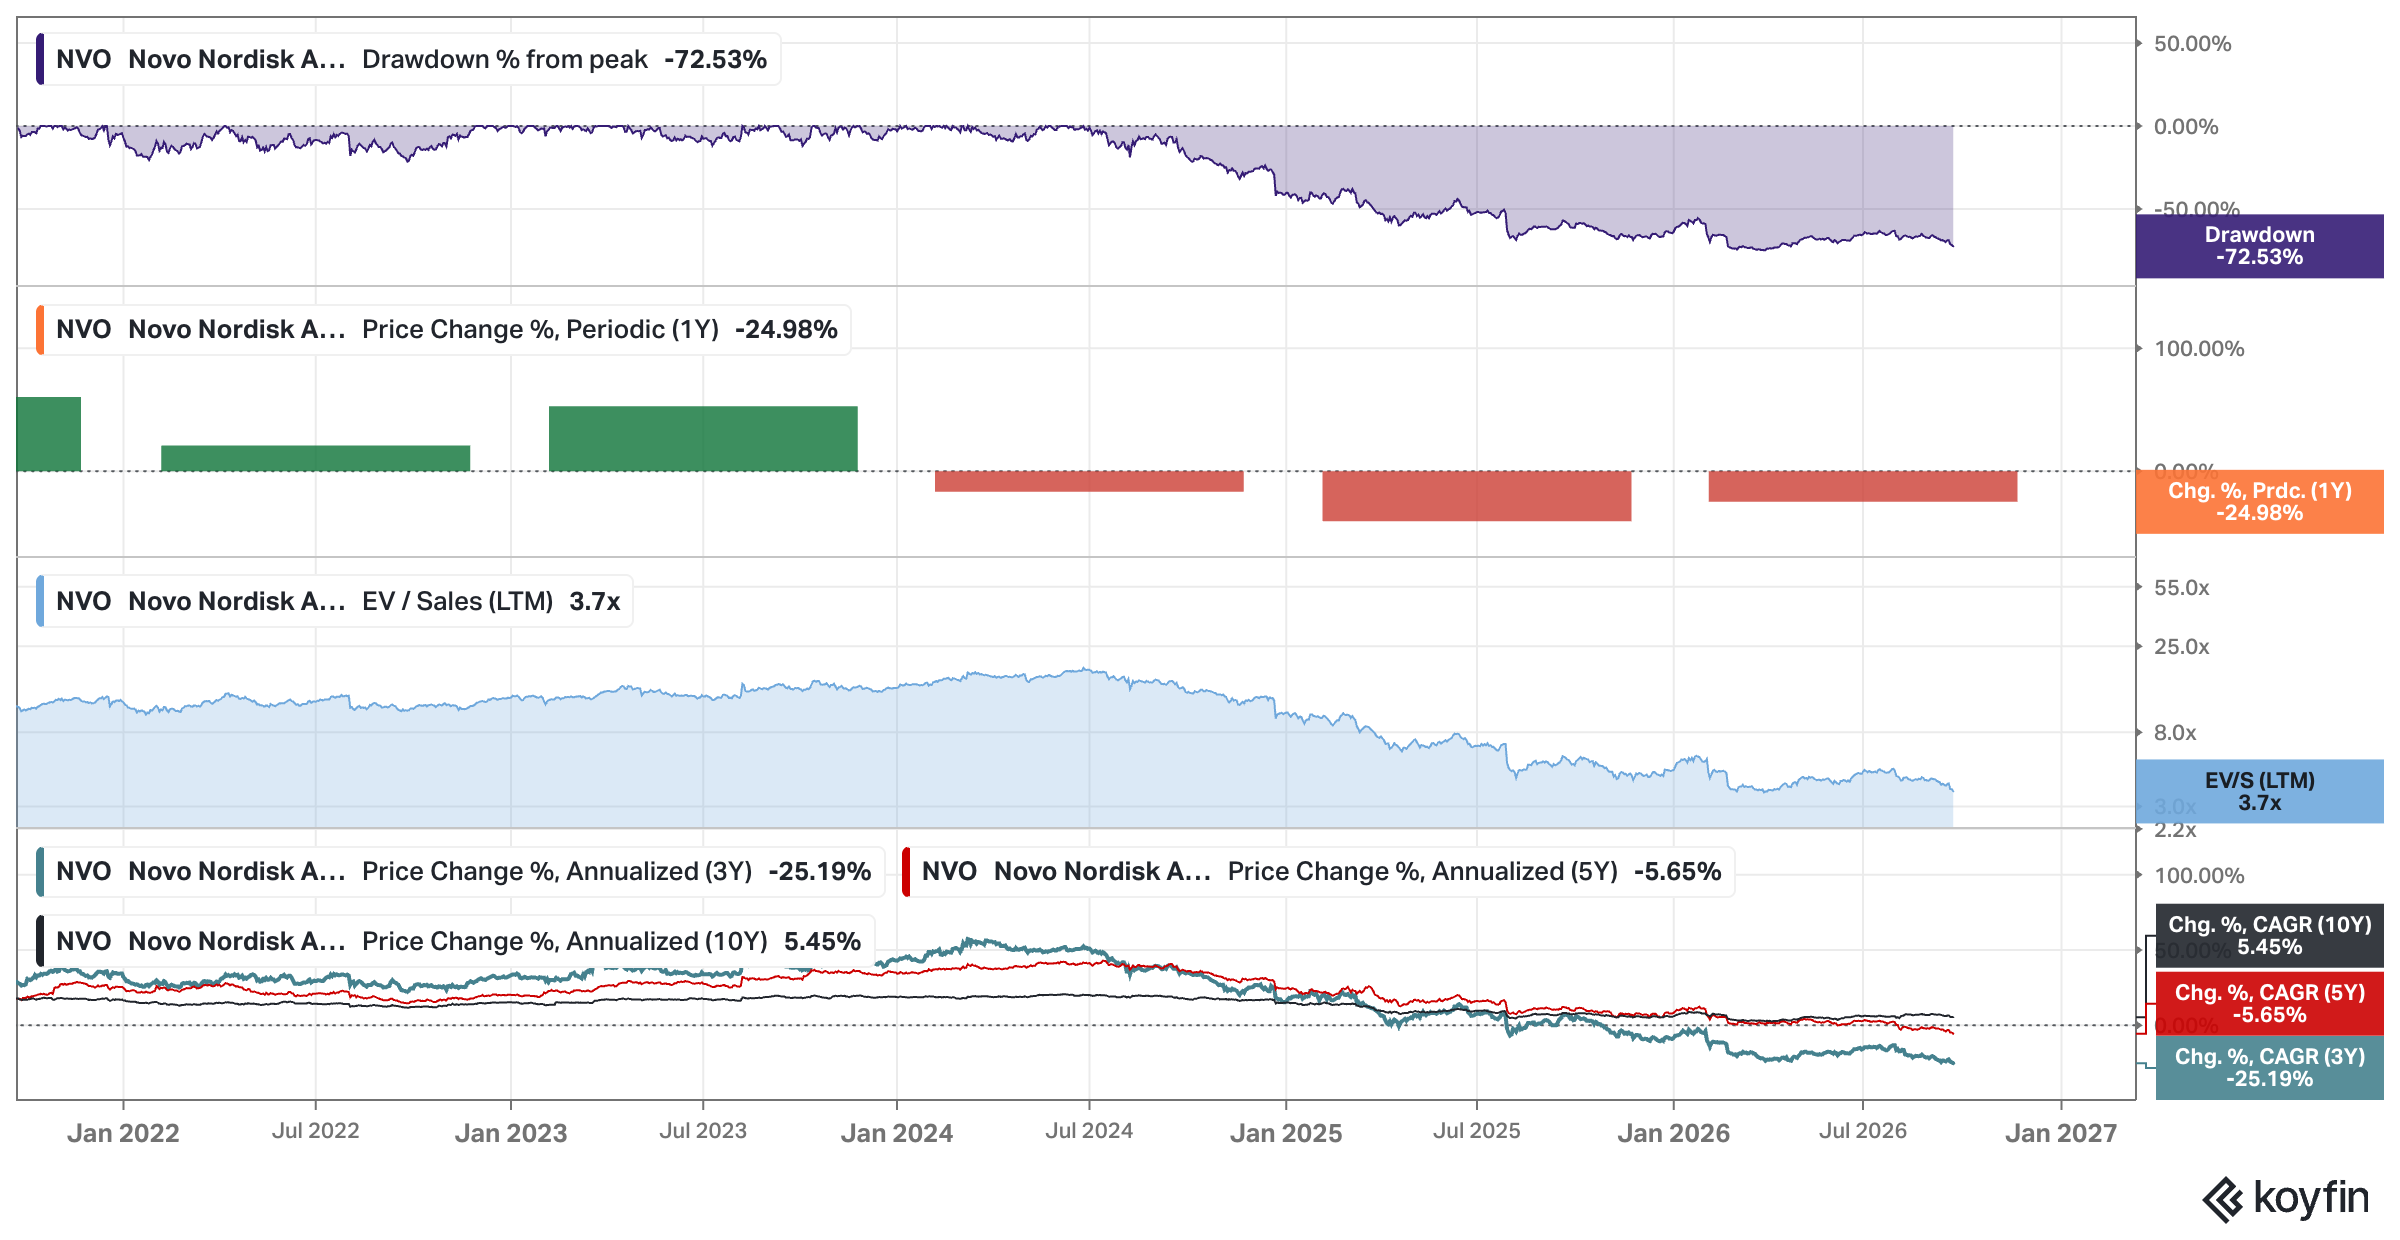
My hunch is that sentiment is pretty bombed out. Novo has delivered three down years in a row, the drawdown stands at about 72%, the three-year CAGR at roughly minus 25%, and even the five-year CAGR has turned negative. No one seems to want to touch the business. The one exception is the ten-year CAGR, which is still positive at around 5%, so the longest-standing holders are still in the green and have not necessarily capitulated yet.
Which new insights change how I think about Novo?
Investors do not seem to trust the new management team, and I struggle to argue with them. Mike Doustdar strikes me as more of a hired-gun-type CEO (even though he rose through the ranks of Novo), and his countless public interviews – seemingly an attempt to restore confidence while the business keeps underdelivering – just don’t quite sit well with me. This is just a gut feeling and highly subjective, of course, but sometimes you need to trust your gut (Rob Vinall argues it’s a great filter with strong signal value), and there are plenty of other companies out there.
The Capital Markets Day on September 21 added an embarrassing moment on top. During a break in the livestream, members of the management team left their microphones on while they believed they were speaking in private, and listeners on the webcast clearly overheard one of them say: “We are going through a period right now where it is almost impossible to provide guidance.” It reminds me of how voters perceive politicians. Most people would rather hear an uncomfortable truth than a sugarcoated one. If visibility is really that poor, management is free to avoid guidance entirely, which is what almost every company did during Covid. That would serve shareholders far better than issuing guidance without any cushion, missing it, and burning through whatever investor confidence is left. The shares fell about 7% on the day, so the market seems to have drawn a similar conclusion.
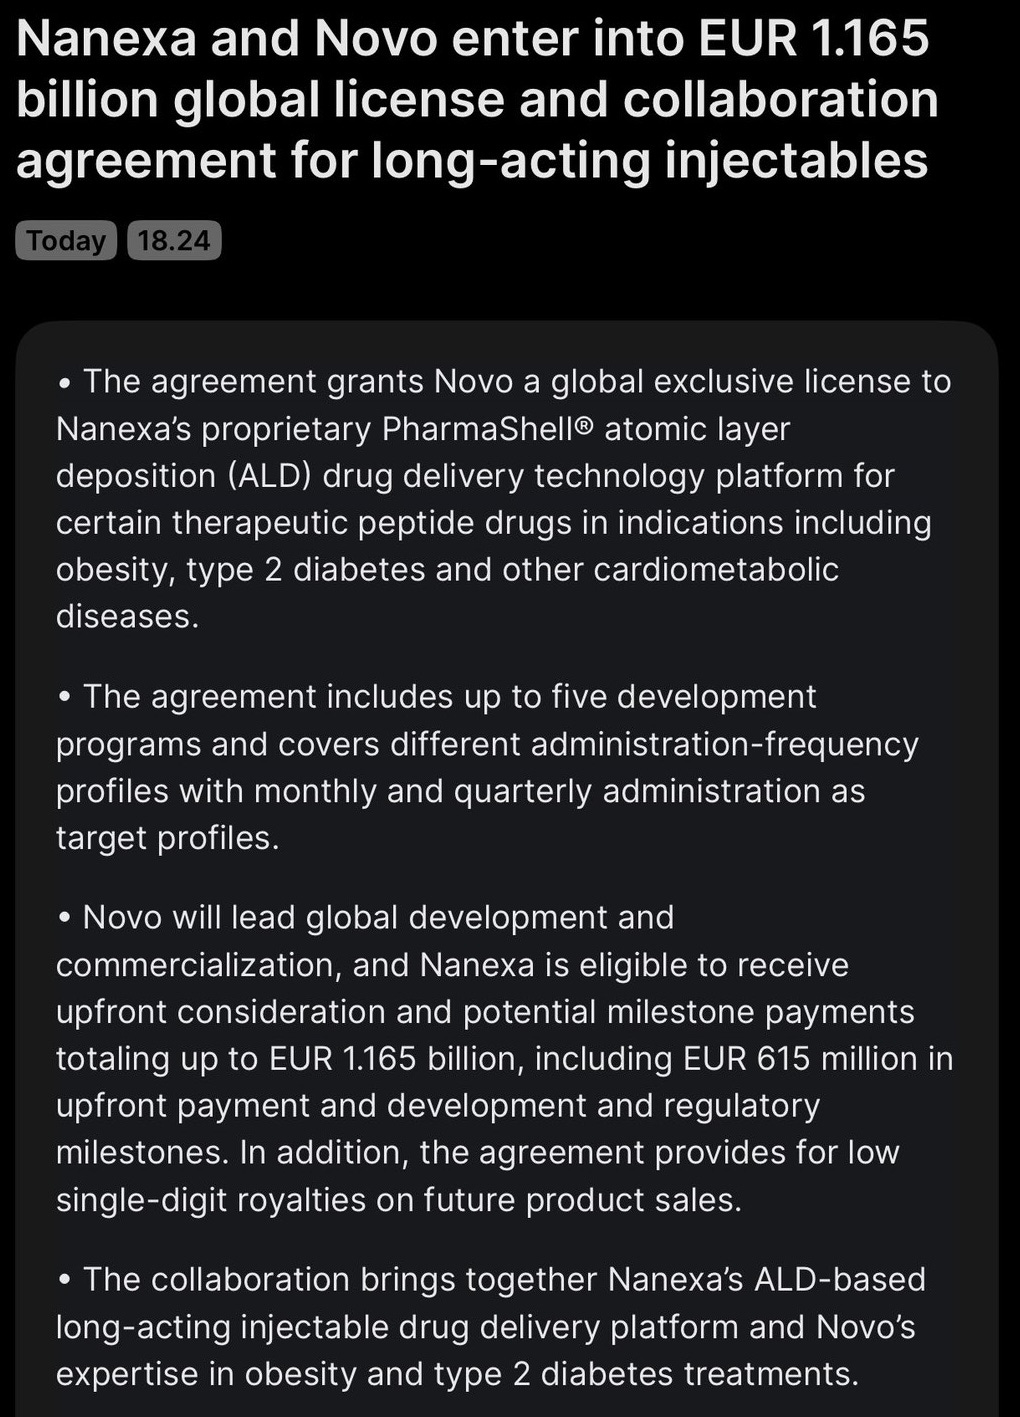
Management also wants to pursue more acquisitions and diversify the business. I covered the base rates of M&A in the first part of this series on Grab (link), and they apply to Novo just as much. The company’s dealmaking in obesity has taken a winding path lately. In mid-September, Novo terminated its 2024 collaboration with Ascendis on once-monthly TransCon Semaglutide, and only ten days later it announced a license and collaboration agreement with Nanexa worth up to EUR 1.165bn (roughly $1.3bn), including EUR 615m in upfront payment and development and regulatory milestones plus low single-digit royalties, for as many as five development programs with dosing intervals ranging from once monthly to once quarterly. Novo had previously run an evaluation deal with Nanexa before choosing Ascendis as its primary partner, so it is now returning to a partner it had passed on, which is something we rarely see. Nanexa already has preclinical semaglutide data supporting dosing as infrequent as once a quarter. The press release does not name the molecules, although I would be surprised if semaglutide and amycretin were not among the five, and cagrilintide may well be one of them.
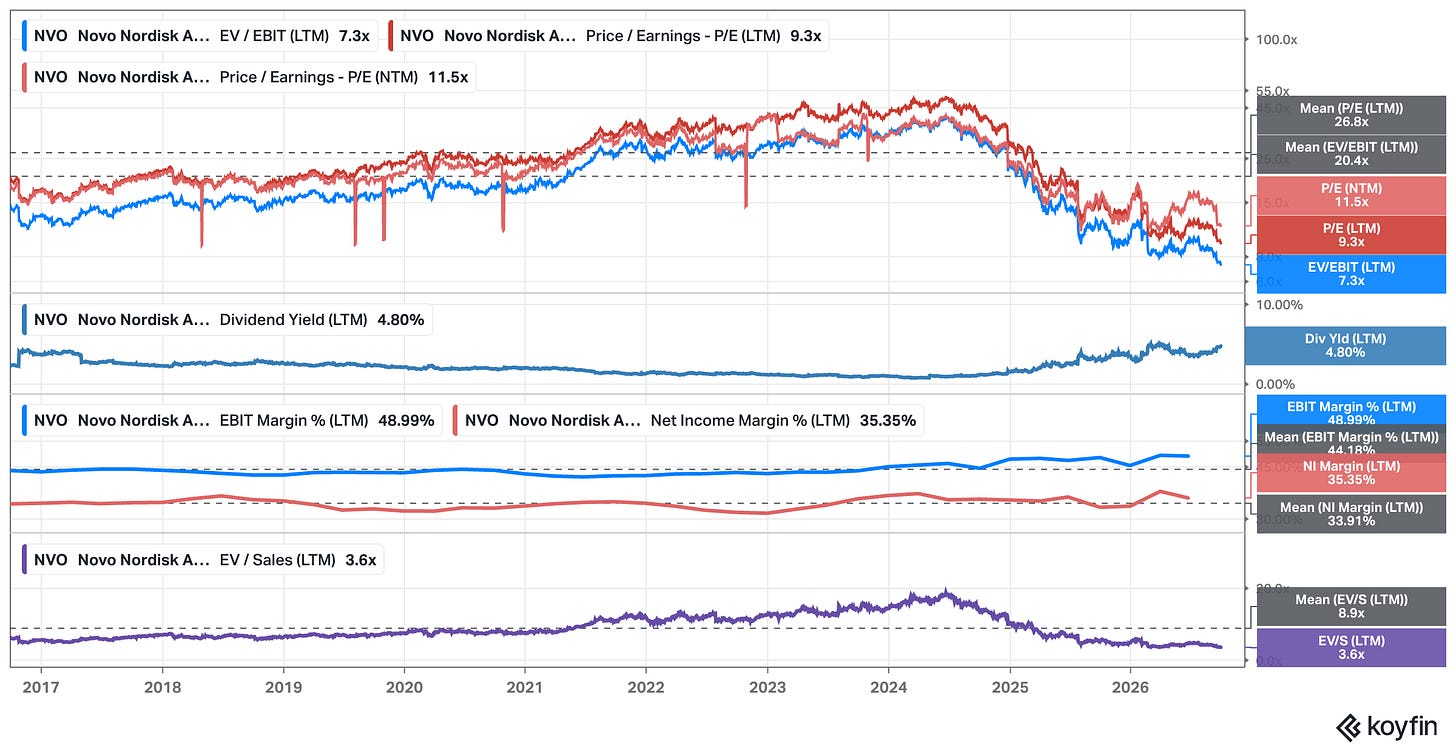
At the same time, you always have to ask what is priced in. I keep saying that the biggest mistake I see investors make is the inability to distinguish between the business outlook and the expectations embedded in the current price. The mistake shows up on the upside whenever embedded expectations become very unlikely to be realized. It is just as common near the bottom, when a share price reaches a level that requires only minimal business success from here. Novo’s stock trades at its cheapest sales multiple since 2015 (3.6x EV to trailing sales) and at 9.3x trailing earnings. I would take that last number with a grain of salt, since the forward multiple is higher – a sign that the market expects earnings to fall from here – and how low earnings can go is one of the key questions here given the many headwinds, pricing pressure and strong competition above all.
Still, Novo has a few things going for it, including a very strong Wegovy pill launch in the US, and this may turn out to be a classic time arbitrage opportunity. In previous write-ups I shared how five factors drive a drug’s success: Efficacy, Safety/Risk, Tolerance, Convenience, Pricing. Applied to the Wegovy pill, convenience is the most obvious win, since many patients would rather take a daily tablet than inject themselves, and Novo reported more than 3 million prescriptions by the ADA meeting in June. Longer term, I’m optimistic
that the pill will be the preferred form factor.Jan (@janthecurious1) shared some good thoughts on X after buying the stock following the Capital Markets Day. He does not pretend the problems have disappeared and acknowledges intense competition from Lilly, real US pricing pressure, and the burden of proving that the pipeline and new launches can return Novo to growth. His argument is that the market is underestimating how much was actually presented at the Capital Markets Day. Management laid out more than DKK 150bn in risk-adjusted annual sales potential from the current pipeline by 2035, more than five new multi-blockbusters launched by 2030, at least ten new Phase 3 programmes, and over 60 million patients reached globally by 2030.
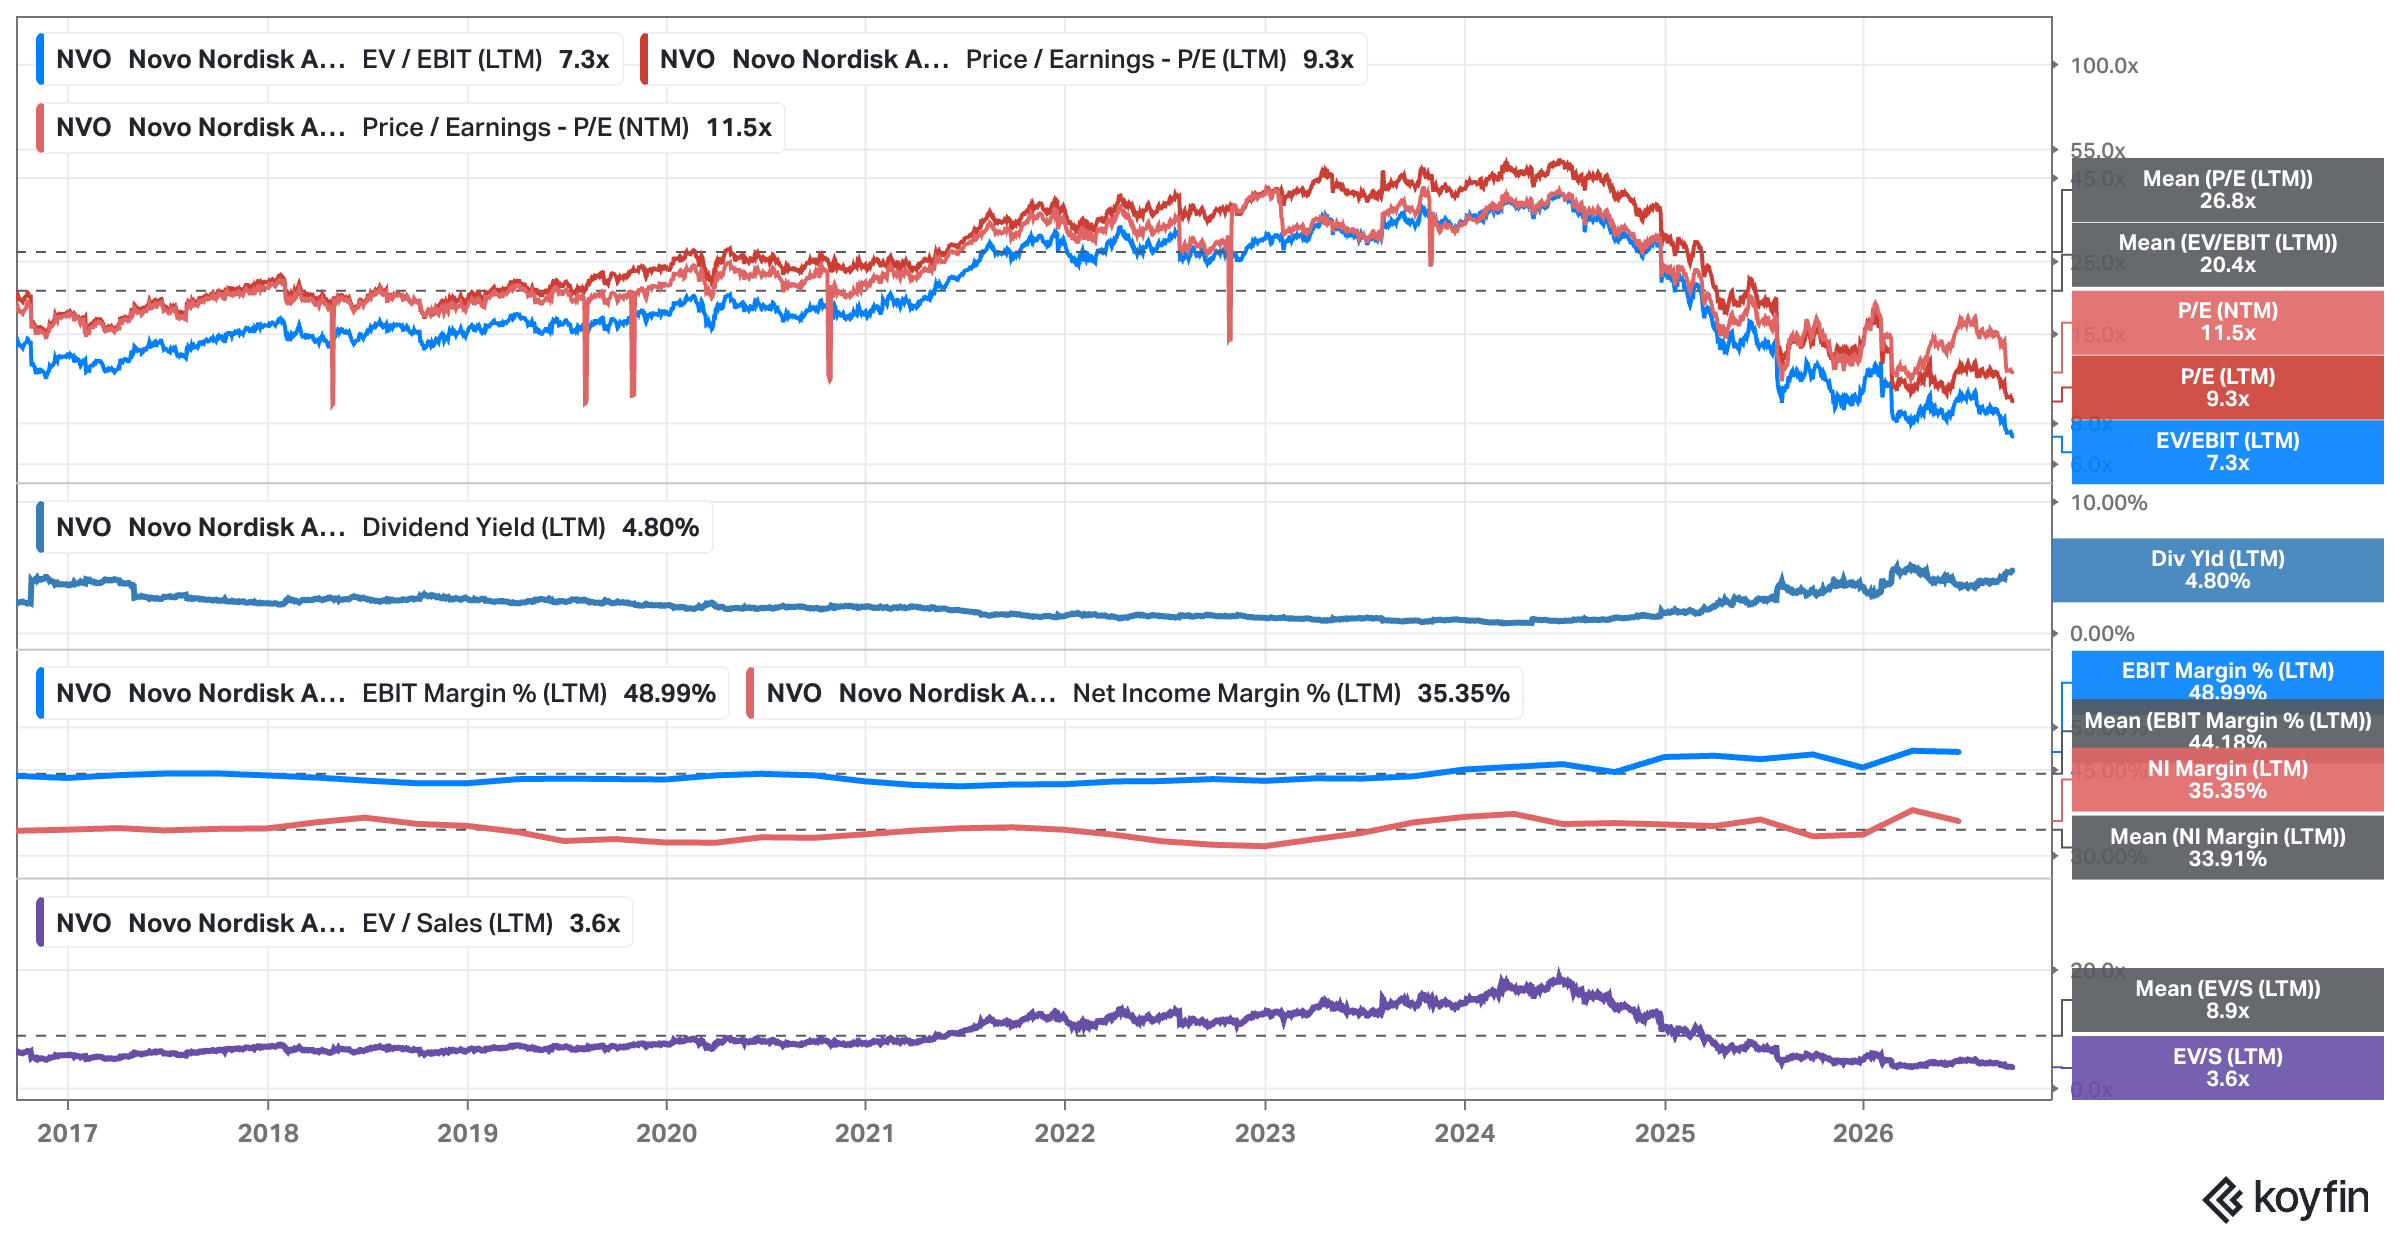
“When you look at this slide, what I’d like you to remember from it is the headline. That’s our ambition. We will have the plan to launch at least 5 multi-blockbusters by 2030, pretty much every year and deliver a combined sales of more than DKK 150 billion in value in less than 10 years from today. This ambition is risk-adjusted, which means it allows for development risks. This is what you should remember.“
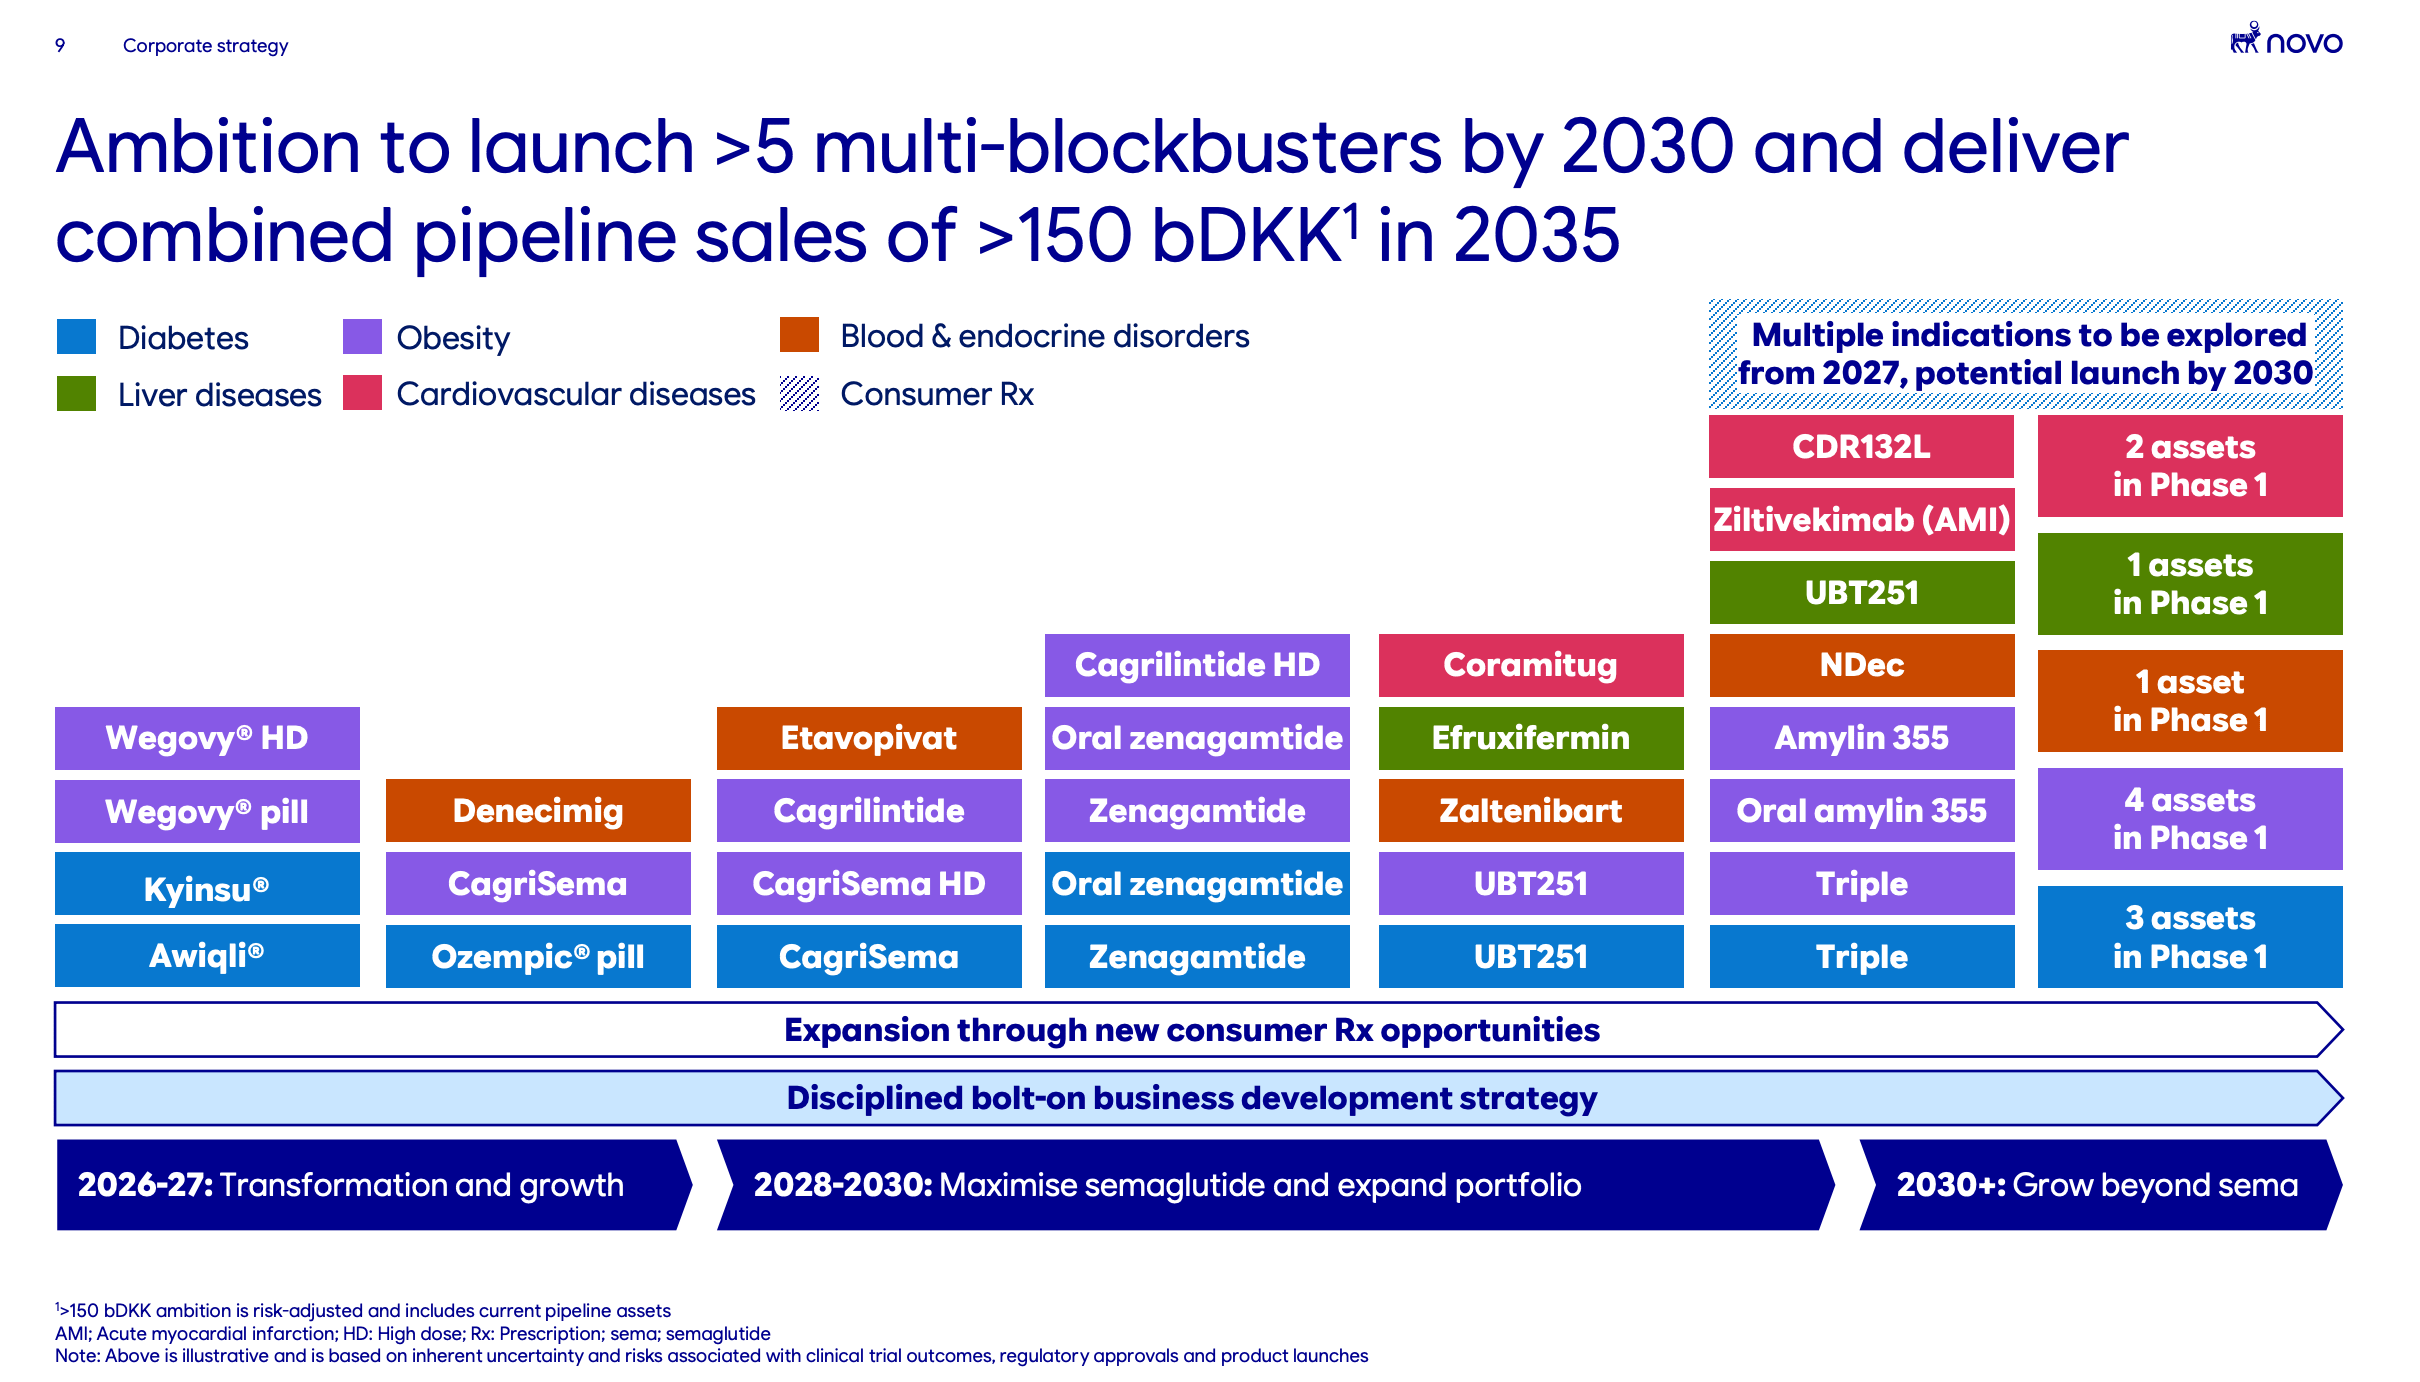
Five oral obesity candidates are in development, a major expansion of manufacturing capacity for oral GLP-1s is underway, CagriSema (an investigational, once-weekly injectable combination medication) is moving toward a potential US approval, and zenagamtide/amycretin is being developed as both an oral and an injectable treatment. Then there is the Wegovy pill, which Jan considers one of the most important parts of the case. Novo has captured the large majority of new oral obesity prescriptions in the US, and management is preparing for a market in which oral treatments play a much bigger role than they do today. To be fair to the bears, the CagriSema story has its own blemish. In a head-to-head Phase 3 trial, it failed to show non-inferiority against Lilly’s tirzepatide, with weight loss of about 23% versus 25.5%.
Final Verdict:
There is so much more to unpack, and I have discussed Novo at length in many previous write-ups (see links above), and many of those points still hold, so I encourage you to continue your reading sessions there. I have always passed on Novo so far, partly because it sits a little outside my circle of competence and I respect those borders.
We might, however, now be in territory where I can exploit a behavioral edge, a setup that does not rely on superior analysis, which I do not think I could bring to a business like this one.
You’d think the sentiment regarding Novo can’t get much worse from here. In the past, investors thought so too, and then it did.
So of course it might happen again, but there is some strong fundamental support in the single-digit earnings multiple territory and my hunch is that the perception of Novo cannot get much worse. The stock has been about flat for around a year, so bears struggled to push the stock significantly lower.
At the same time, Novo is incredibly concentrated product-wise given the size of the company, which is also something I struggle with getting comfortable with. Semaglutide (the active ingredient in Novo's blockbuster drugs Ozempic, Wegovy, and Rybelsus) alone accounts for roughly three-quarters of 2026 sales, and the clock on it is already running – generics launched in Canada, India and China this year, Medicare's negotiated price cuts US pricing by 71% from 2027, and the key patents expire in Europe in 2031 and the US at the end of that year.
Pulling the threads together, I think a bottom may be nearing. A two-decade uptrend broke hard, but both downtrend lines are still intact, volume spikes have repeatedly failed to mark the bottom, and the stock is drifting back toward its March low. Compared with Grab, there is no confirmed stabilization to lean on and the fundamental outlook looks more challenging. What I can see is a valuation that already requires little (if margins can stay above a certain level) business success and a wide sideways range that could, in time, turn into a proper base.
Two signals would change my read. A successful retest of the $34.85 low, ideally on fading volume and followed by a higher low, would suggest that the marginal seller is finally stepping back. A break above the light red downtrend line, currently somewhere in the mid-$40s, that holds on a retest from above would confirm that the balance of power has shifted toward buyers.
A decisive break below $34.85 on heavy volume, on the other hand, would tell me the selling pressure is not exhausted yet.
Disclaimer:
As of the date of publication the author owns no shares in the company; but that may change. The analysis presented in this blog may be flawed and/or critical information may have been overlooked. The content provided should be considered an educational resource and should not be construed as individualized investment advice, nor as a recommendation to buy or sell specific securities. I may own some of the securities discussed. The stocks, funds, and assets discussed are examples only and may not be appropriate for your individual circumstances. It is the responsibility of the reader to do their own due diligence before investing in any index fund, ETF, asset, or stock mentioned or before making any sell decisions. Also double-check if the comments made are accurate. You should always consult with a financial advisor before purchasing a specific stock and making decisions regarding your portfolio.
I have expertise and more than two decades of research in this field. I think Novo is priced as if they have 5% market share and no pipeline. Reality is they have around 40% market share for obesity and diabetes. 40%!!! If we were comparing similar market share breakdown for NVDA vs AMD, we would have assigned a different price to the laggard. Second, we think of 23% weight loss on Cagrisema as a failure. More than 75% of patients do not need to lose more than this much weight. Also look at weight loss results from other companies, like B.I for survo... makes Cagrisema look much better. Also 2031 patent expiry isn't tomorrow. there are already NDA submitted (Cagrisema) and trials under way for phase 3... so i am taking the historically low valuation, 4% dividend yield and getting paid to wait.
There are estimated 1 billion patients with obesity. even 5% market share of that by 2035 will be unimagineable.
A concise and well reasoned summary!
I am always amazed by how popular Novo Nordisk is with many financial commentators.
I believe that your call as it being outside your circle of competence is a wise one and one I firmly share, even though are maybe especially because I work in healthcare.