

A quick word on context for anyone joining this series now. This post is the third installment in a series of seven, in which I walk through the companies that currently rank highest on my watchlist. The trigger was Ember Infrastructure Management’s 615p proposal for Ashtead Technology, one of my largest positions. If that deal materializes, a meaningful chunk of capital will need a new home, and I want my homework done before the cash lands in my account. Every idea goes through my perception change framework and answers the same set of questions. Could now be an opportune moment to buy? Is sentiment bombed out, or is there still some air left to let out? What is the price trying to tell us? And which new qualitative insights change how I think about the business? If you missed the first two parts, you can catch up on Grab here and on Novo Nordisk here.
Dear compounders,
Who would have thought that LVMH, for years one of the most admired compounders in Europe, could fall this far?
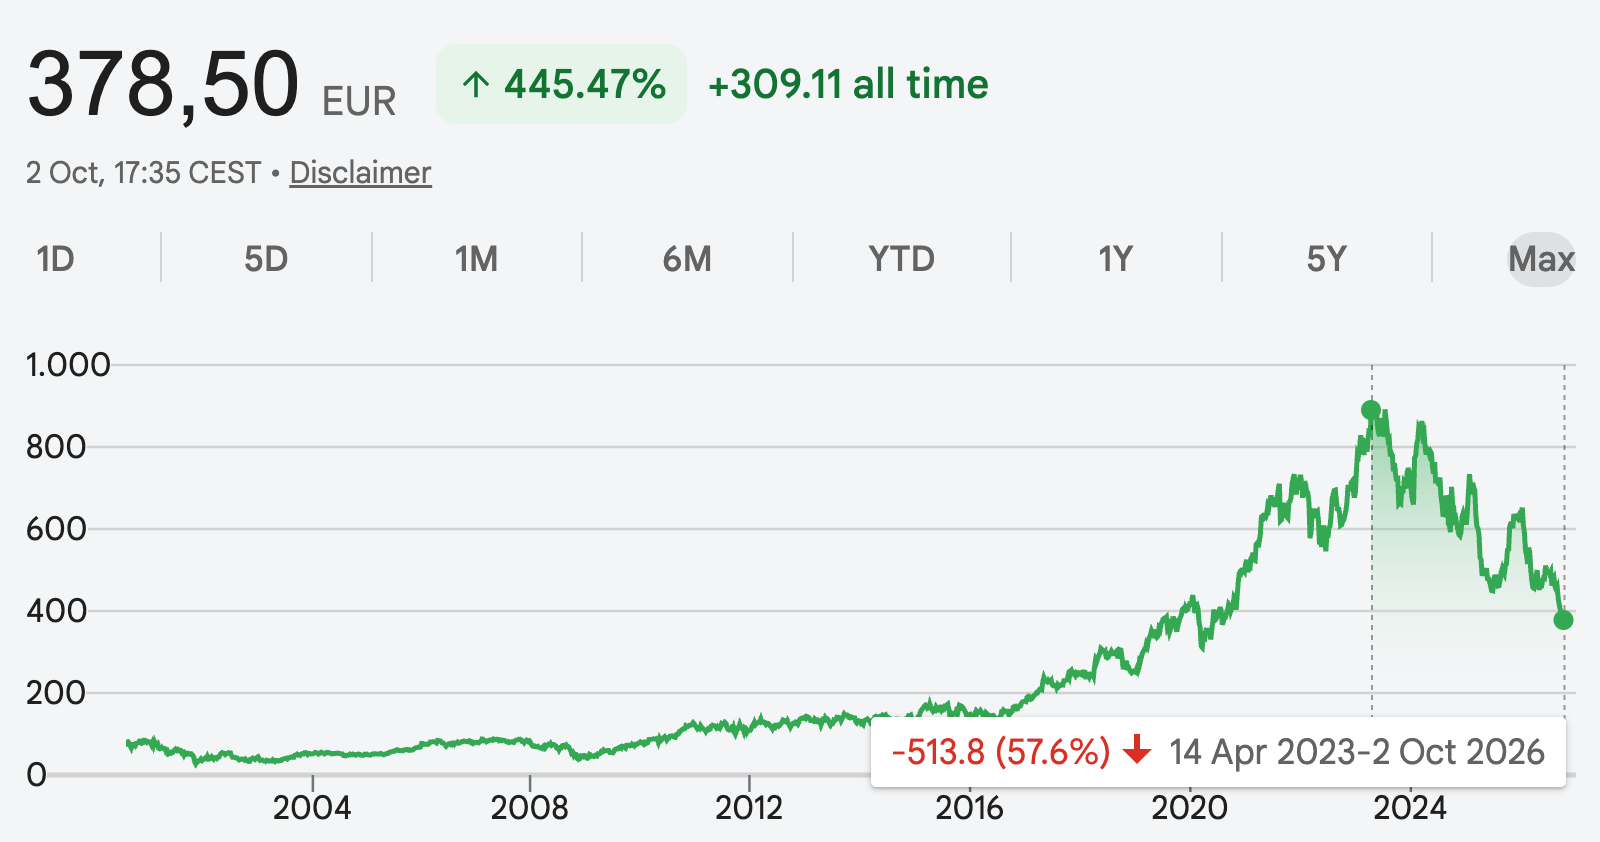
Just like Novo Nordisk, the subject of the previous installment [read it here], LVMH was long perceived as one of the best businesses in the world, and rightfully so. Yet the stock is now in its worst drawdown since the Global Financial Crisis, down about 55% from its peak, and it has lost roughly 41% over the last five years. Ouch.
That brings me back to my piece on half a lost decade stocks. Five years of going nowhere, or in LVMH’s case going backwards, can do serious damage to a portfolio and to an investor’s conviction.
Half a Lost Decade Stocks

Today, I am going to write about the concept of “half a lost decade”-stocks as an adjustment to the “lost decade”-stocks mental model, because the original version doesn’t fit my investing style or the kind of business I want to be a part-owner in.
A full lost decade is still a long way off, though. Over the last ten years, the stock is up around 140%, which tells you how extraordinary the run before the decline was. There is one important difference to the setups I described in that piece. There, I was looking for companies whose share price went sideways while earnings kept compounding underneath. LVMH’s net profit of €10.9bn in 2025 was below the roughly €12bn it earned in 2021, so this drawdown reflects shrinking earnings as well as a shrinking multiple. I also don’t consider LVMH a business that compounds intrinsic value at 15-20%+, so I might look for an entire lost decade, as unfathomable as this may sound …
Read my prior LVMH analyses:
I still consider LVMH a world-class business, and investors who paid €900 a share were right about its quality. Where they went astray was in three other assessments. They underestimated how much demand Covid had pulled forward, they extrapolated growth rates the industry could not sustain, and they trusted management to protect the exclusivity of its key brands while chasing volume. Those three mistakes are what the market has been correcting ever since. In short, they were wrong about the embedded expectations at COVID price levels, which LVMH could not achieve.
Further below, I will also introduce you to Intern Pierre, who has been short the luxury sector throughout the last few years and, as far as I can tell, still is. Shorting luxury was a deeply contrarian call when he started. Hats off to him for that call!
And with the sector down this much, still being short is beginning to feel contrarian again.
One housekeeping note before we start. Since I wrote this post, the share price has fallen further to €378 as of Friday’s close. I have kept the charts as they were, so keep in mind that they are slightly dated.
New here? Join 5,100+ readers and get 3 FREE GIFTS when you subscribe:
📈 Valuation Spreadsheet
📚 eBook: Investing Visualizations
💡 eBook: 250 Thought-Provoking Quotes
Idea #3: LVMH
What is the price trying to tell us?
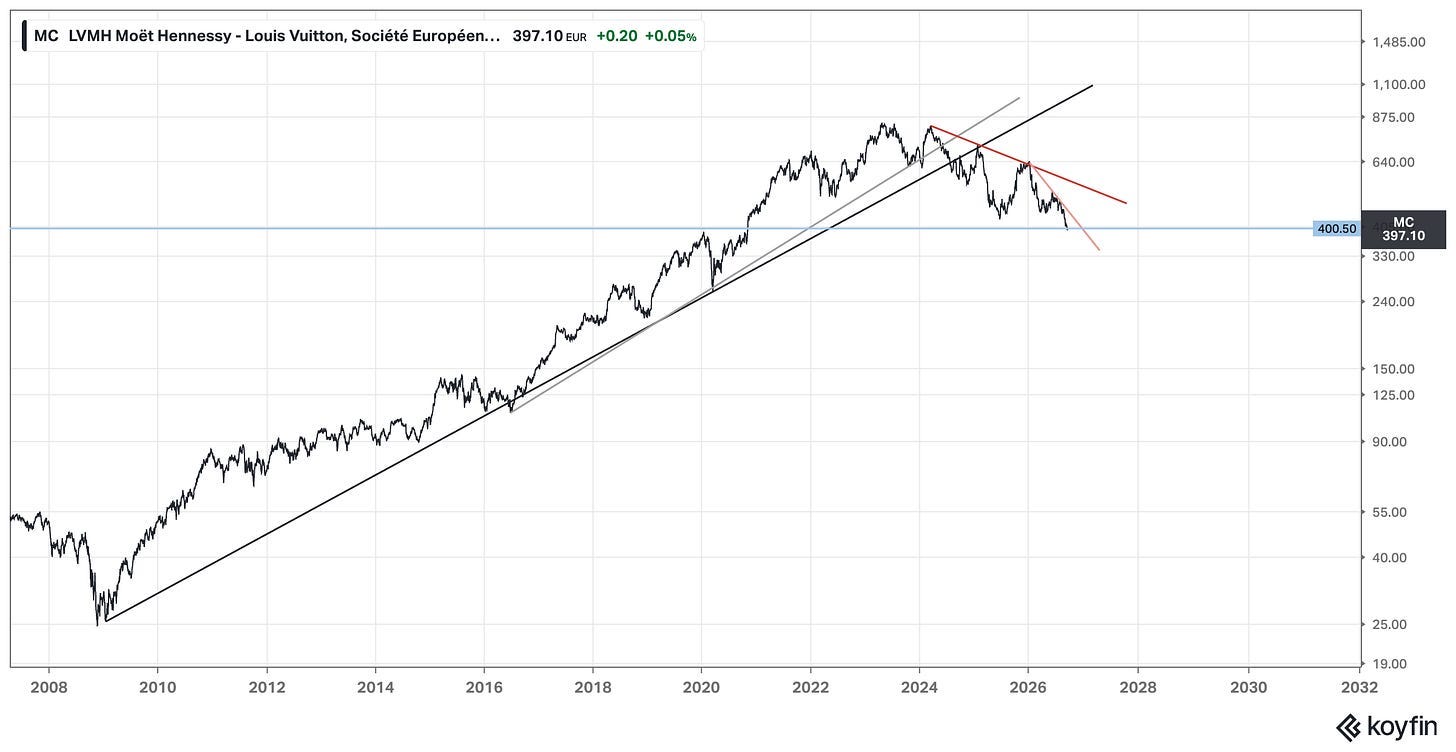
LVMH has broken both of its long-term uptrends, the one that started at the GFC low in early 2009 and the steeper one that began in 2016. It is yet another textbook example of the mental model from Part 3 of my framework series: the longer and steeper the uptrend, the more violent the reversion when it finally breaks. The stock now trades well below the downtrend that started in March 2024, which has three touchpoints.
If you zoom in, there is also a shorter-term downtrend that kicked off in January 2026 and already has four touchpoints.
Neither line has been seriously challenged.
When I drafted this section, LVMH had just slipped below the psychologically important €400 level. It has since dropped further to €378, so the break has extended rather than reversed.
In the language of my framework, a true confirmation would come if the stock rallied back toward €400 and got rejected there, turning former support into resistance.
As I wrote in Part 3 of my framework:
“Clean trends have multiple touchpoints. Price interacts with the line repeatedly. Buyers step in near the same level. Sellers emerge where you’d expect them to. Each interaction is a form of confirmation. It tells you that market participants are responding to that level. Supply and demand are being validated in the open.”
Is sentiment bombed out, or is there still some air left to let out?
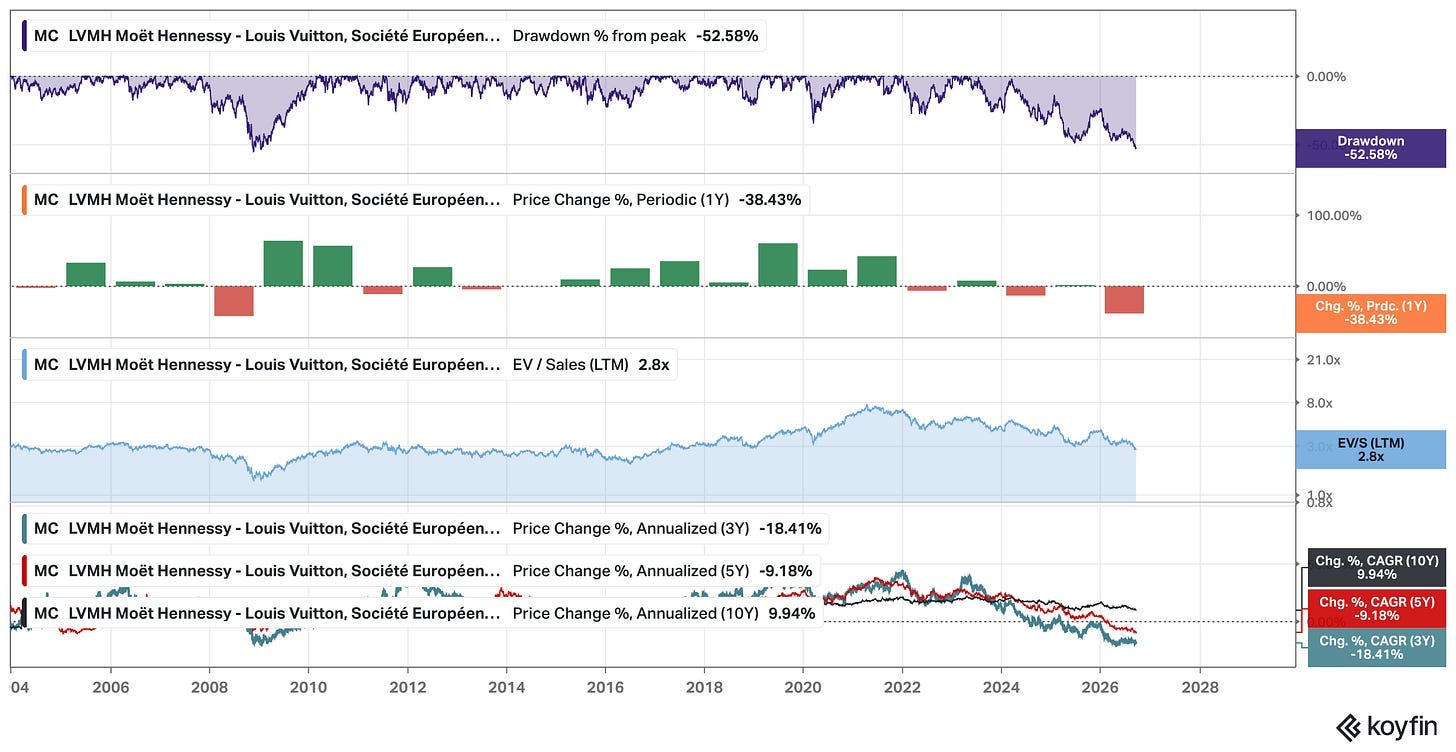
LVMH is experiencing its worst drawdown since the GFC. At about 53% in the chart above and roughly 55% at €378, it is now approaching the depth of the 2008–2009 decline.
The last five years have been rough for shareholders, with a five-year price CAGR of about minus 9% and a three-year CAGR of about minus 18%. The ten-year CAGR is still close to 10%, though, which again shows how strong the run before the decline was.
On valuation, LVMH trades at 2.8x EV to trailing sales in the chart, roughly 18% below its long-term mean of 3.4x, and lower still at today’s price. That is cheap relative to its own history, although far from the sub-2x multiples the stock traded at during the GFC.
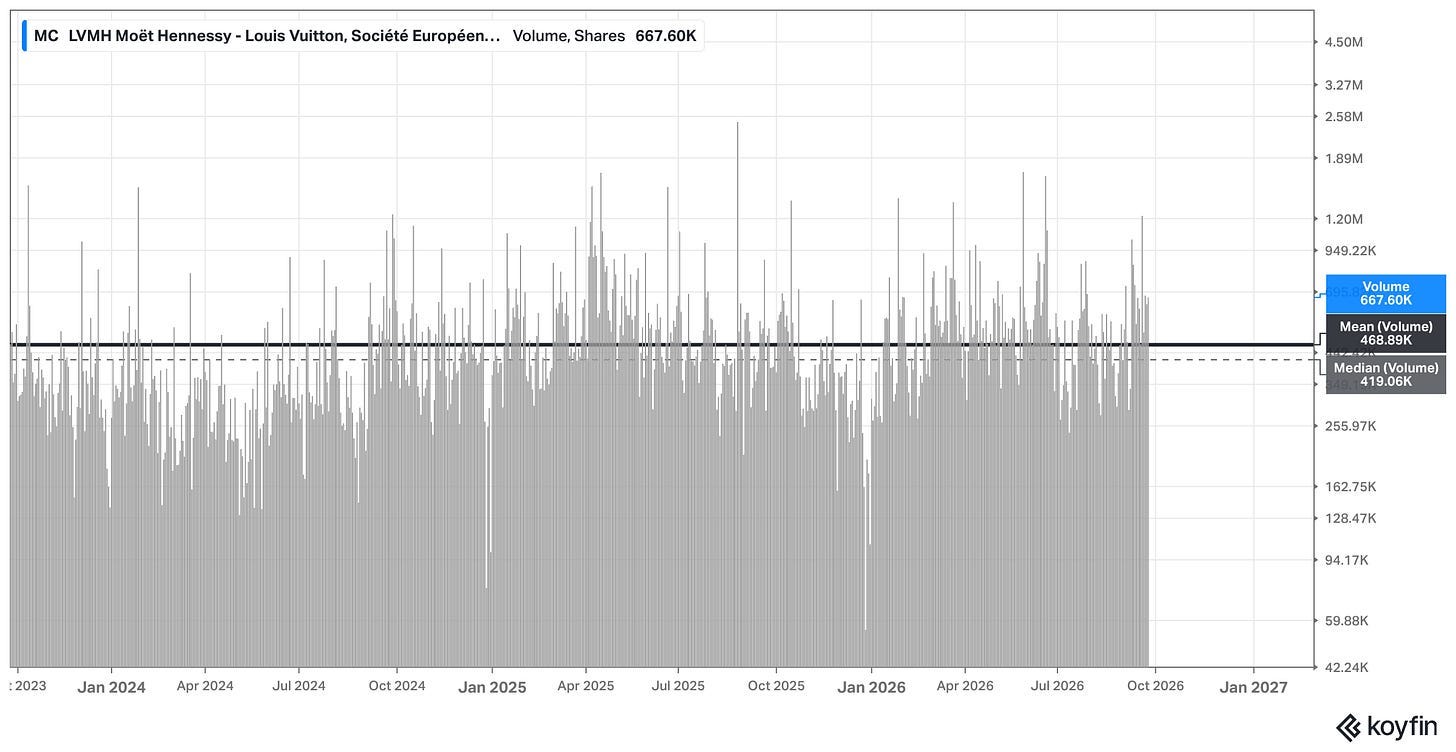
Volume tells a more ambiguous story than I first thought. There have been several spikes over the past two years, including a cluster in recent weeks at more than twice the mean daily volume of roughly 470,000 shares, and plenty of holders have clearly headed for the exit. None of these spikes has looked like a true capitulation, though, and the largest one came about a year ago, after which the stock kept falling. That matches what I saw with Novo, where volume spikes repeatedly failed to mark the bottom.
I would want to see heavy volume coincide with a low that actually holds before concluding that the sellers are exhausted.
Which new insights change how I think about LVMH?
Few large companies in Europe carry as much negative sentiment right now as LVMH. Just like Novo Nordisk, LVMH was once the biggest company by market cap in Europe, and it might as well follow Novo in its track of losing its “top 10” status.
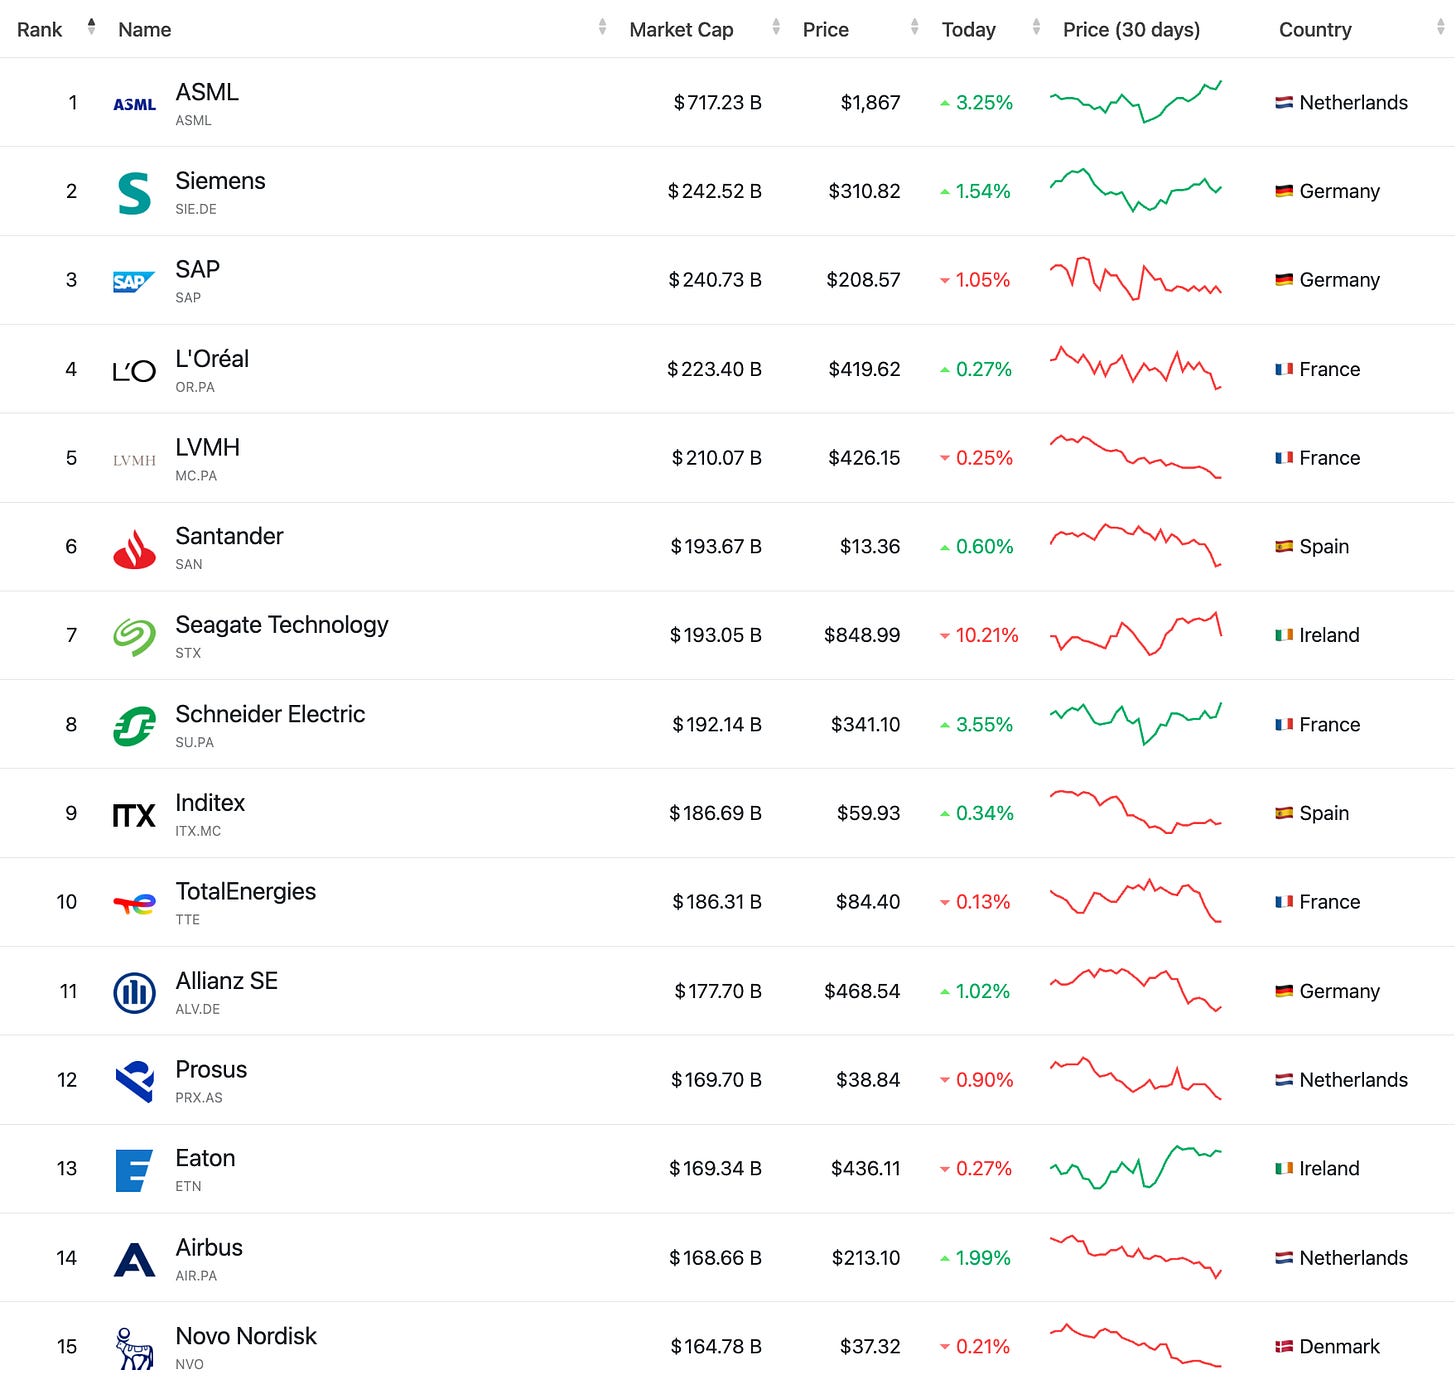
And the list of worries keeps growing. The debate used to center on the cyclical slowdown in luxury demand. It now spans legal exposure, currencies, China, brand fatigue, and the structure of the group itself. Some of these risks are well understood and probably priced in. Others have only surfaced recently, and those are the ones I find more interesting to think through.
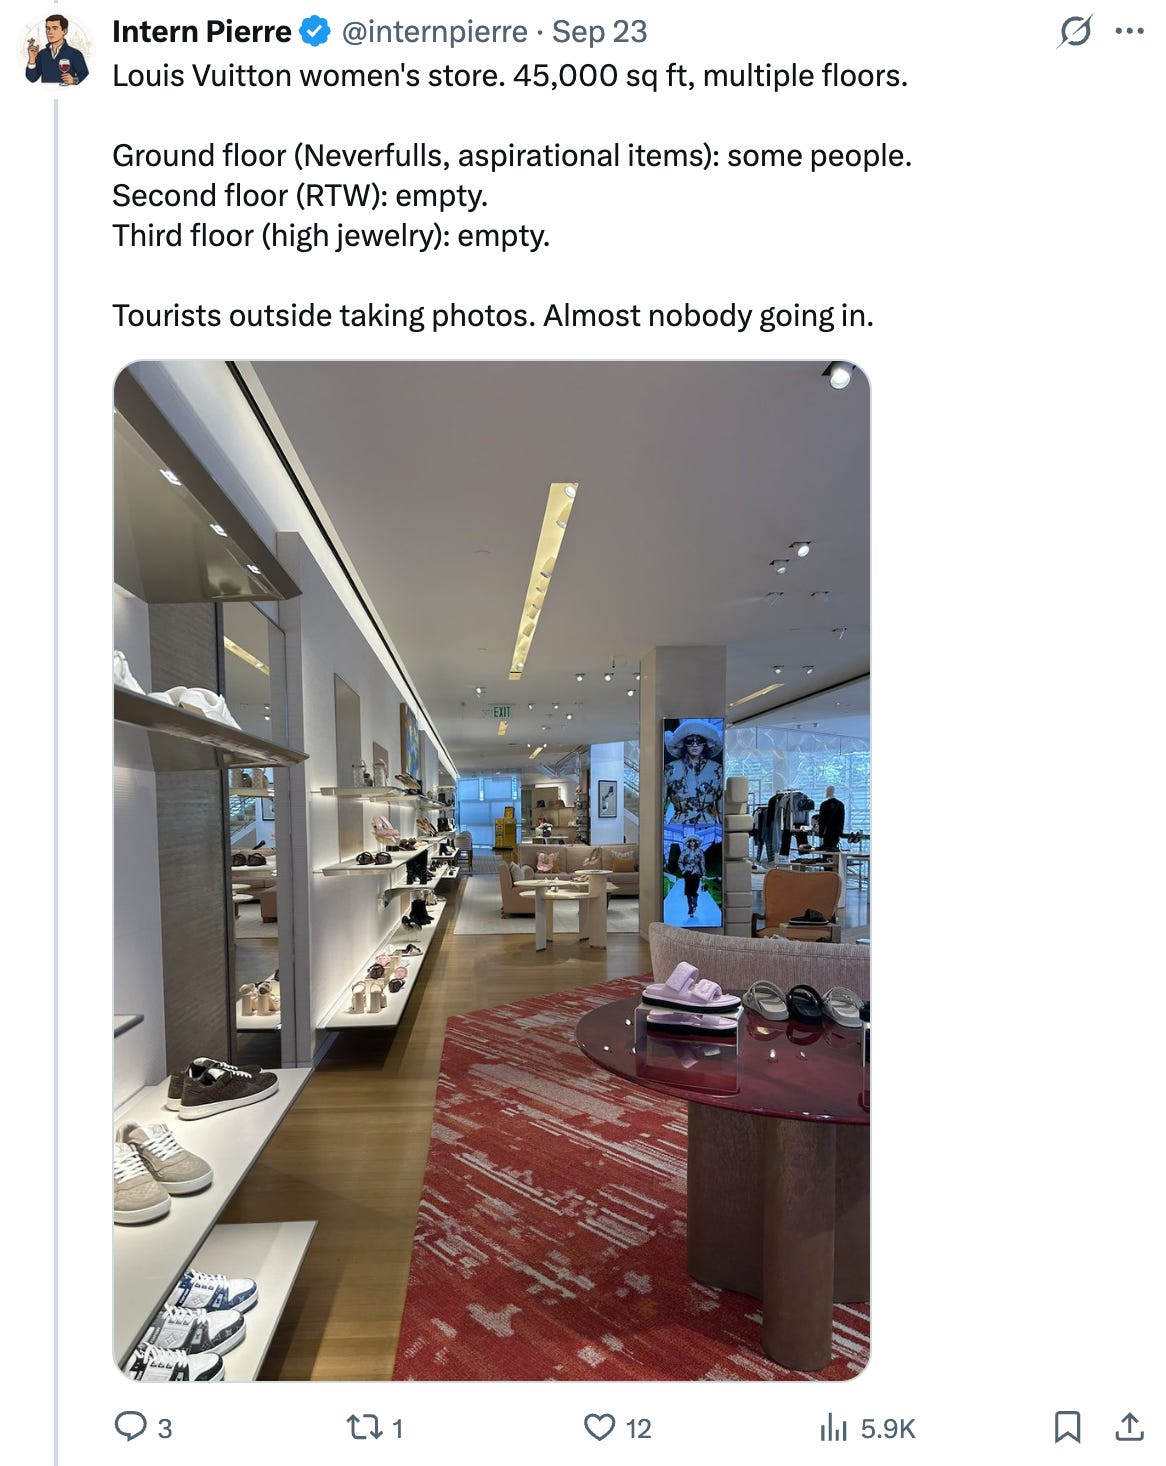
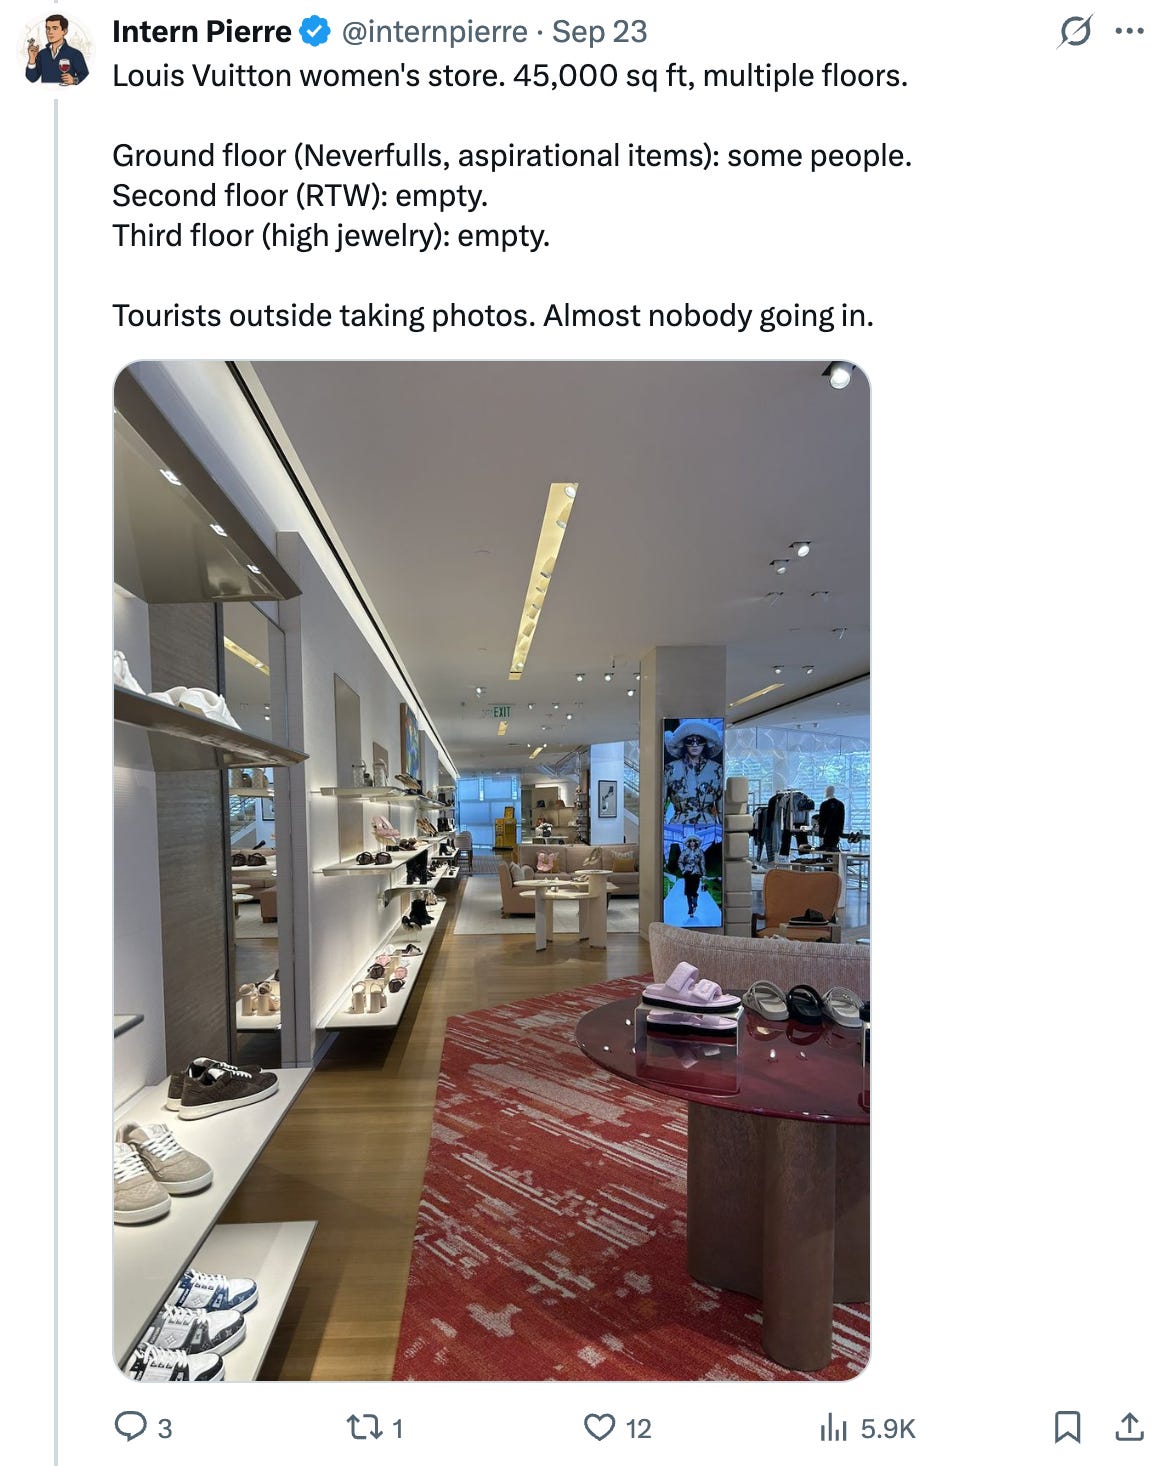
I encourage everyone to follow @internpierre on X and read some of his boots-on-the-ground research threads on the luxury sector (such as this one). They are highly insightful and at the same time very entertaining. Keep in mind that he is short LVMH and possibly some other names. Based on the perspectives he shares, there may in fact be more downside.
The newest risk vector comes from an investigation into the missing Hermès stake of Nicolas Puech, the founding-family heir who says he was stripped of his 6% holding through schemes involving his late wealth manager, Eric Freymond (who died by suicide in 2025 at the age of 67). In a June court filing, LVMH firmly denied ever trying to buy Puech’s shares. According to documents Reuters reviewed, however, LVMH signed a 2002 agreement to buy those shares in a deal crafted with Freymond, and LVMH and the Arnault family holding paid Freymond’s firm at least $20 million in commissions and fees between 2001 and 2009 while he helped LVMH quietly build its Hermès position. LVMH maintains the agreement was never executed and says the document was destroyed in 2010, the year it revealed its Hermès stake. Puech is seeking €14bn in damages, and LVMH and Bernard Arnault are named as defendants. The market may well have been aware of this case all along, and nobody knows yet how it ends. Still, a worst-case outcome could be worth something in the order of a full year of LVMH’s free cash flow, and the reputational side of a criminal probe that keeps circling the company’s past dealmaking is harder to model.
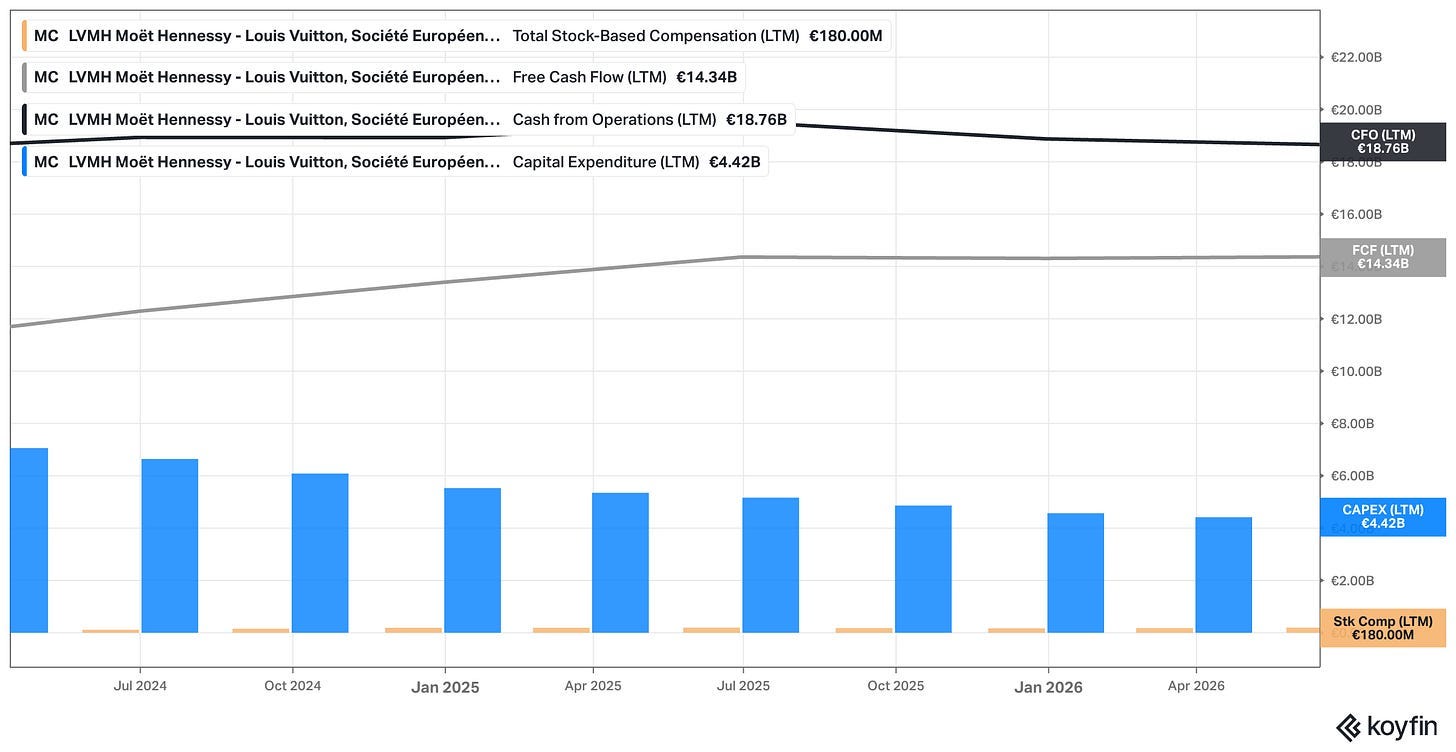
The chart above shows that LVMH generated €14.3bn of free cash flow over the last twelve months. Note how much of that resilience comes from capital expenditure falling from roughly €7bn to €4.4bn, which fits the picture of a group that overexpanded its store network during the boom years and is now pulling back (I encourage you to think through what this means for expected margins going forward 😉).
At the same time, the Arnault family has announced a plan to simplify its control structure. Financière Agache would be absorbed by Agache, Agache by Christian Dior, and Christian Dior would then become a limited partnership with shares (SCA) under the name Agache. The resulting Agache SCA would be the single listed vehicle holding the bulk of the family’s LVMH interest, with 49.76% of the capital and 65.55% of the voting rights. Minority shareholders in Christian Dior can tender into a withdrawal offer at 95% of revalued net asset value – an illustrative €469.05 per share as of September 23, which is a 27.3% premium to the prior close – or stay on as shareholders of the new holding. For LVMH shareholders, I read this mainly as a further cementing of family control, since an SCA structure makes the controlling shareholder essentially unremovable. That has worked out well under Bernard Arnault. It also means whatever discount the market applies to LVMH for governance and succession is unlikely to close anytime soon – at least I certainly wouldn’t model it –, and anyone considering the new Agache SCA will have to think carefully about the discount at which a holding company like this trades to its net asset value. The shareholder votes are scheduled for December 2026, and the tender offer is expected in the first quarter of 2027, with no squeeze-out planned.
A risk I think is underappreciated is currency. Luxury goods benefited from dramatic currency weakness in Asia until various points this year, around June for the Korean won and the Japanese yen. Moves of that size tend to pull spending forward, because consumers arbitrage temporarily lower prices, so organic growth during such periods is not always a true signal of underlying demand. Asia has been weak for several years, but it had shown signs of recovery in recent quarters, and my suspicion is that the weak currencies propped up a good part of that. Since June, those currencies have been reversing.
China deserves its own discussion. In the 2010s, European luxury brands were strongly associated with status, wealth, quality, and modernity, and a logo or a heritage story carried significant value on its own. Since 2020, sentiment has become more rational. Economic uncertainty, repeated price increases, and weaker perceived value have reduced the willingness to pay purely for a foreign label. The rise of Guochao, for instance – a cultural and consumer phenomenon in modern China characterized by a surge in pride and the embrace of domestic brands incorporating traditional Chinese aesthetics – has made Chinese heritage, design, and local identity desirable, particularly among younger consumers, and Chinese brands have moved from being seen as cheap imitations to credible alternatives with good quality, cultural relevance, and often much better value. I would be careful not to overstate this, though. European luxury has kept its moat, you cannot just replicate a century+ brand history, and few Chinese brands have reached anything close to global luxury status. The real threat, as I see it, is that Chinese consumers – representing a massive growth market for LVMH – no longer grant an enormous brand premium automatically, which forces Western houses to earn it through desirability, craftsmanship, design, and exclusivity.
Louis Vuitton has just shown how fragile that goodwill can be. It won a trademark case against the Chinese tea chain Molly Tea over a four-petal flower logo and was awarded a mere 10.3 million yuan (roughly $1.5 million) in damages, and the win triggered a patriotic backlash online, with critics arguing the motif resembles a traditional Tang dynasty pattern. That matters a great deal for LVMH, because Louis Vuitton accounts for roughly a quarter of group sales and around 60% of EBIT by UBS’s estimates. The damage shows up in the numbers. According to estimates by JL Warren Capital reported by Bloomberg, Louis Vuitton’s sales in China fell about 30% in July, 20% to 25% in August, and around 13% in September. The “improvement” is encouraging, but it also shows how quickly a single court case can turn into a brand problem.
We can also point to a deeper tension in the business model. If a luxury brand gets too popular, its own success becomes its downfall, because scarcity is the product. Louis Vuitton has been dealing with quality complaints for at least two years, and as far as I can tell, they had not been fully resolved last year, which is part of the reason it lost so much ground in China. The group likely overexpanded its store network during the boom years, and I would expect a reasonable number of closures over the coming years, which may impact profitability. I’d encourage management to play the long game here, though, and accept short-term growth headwinds to rebuild desirability; it’s LVMH’s greatest asset.
There also seems to be a growing preference among high-end consumers for bespoke and custom-made goods over big brands, whether in handbags, shoes, suits, or ties. That is probably not a big hit to Hermès yet, but if you can get a bespoke bag for a third of the price or less, it could become a headwind for the more accessible end of LVMH’s portfolio. What tempers this risk somewhat is that LVMH and Hermès have often locked down the manufacturers themselves, either by owning them outright or through exclusive deals with the tanneries and workshops that supply them. A bespoke maker still needs access to the best materials such as finest hides and to artisans who have trained for years, and a meaningful share of that capacity already sits inside or closely alongside the two groups. In my view, this craftsmanship moat is not very well understood and is often overlooked, since most discussions of luxury stop at brand power and rarely reach the supply of skill and materials underneath it.
The portfolio itself is another source of skepticism. One of our community members would, in fact, like to see LVMH spin off the drinks business, which I thought was an interesting angle. He argues there are no real synergies with fashion and leather goods, and the spirits market has continued to suffer. I do not expect a spin-off to happen, and that is part of the conglomerate discount you have to accept.
The group owns some excellent smaller brands, but most are too small to move the needle (see Louis Vuitton’s contribution I mentioned above), and their successes are about as likely to be offset by underperformers elsewhere.
LVMH was also slow to push any of its houses into the ultra-luxury segment to compete with Hermès; we discussed this above.
Sephora is the clear bright spot and might be the asset of LVMH I’d be most bullish on going forward – you can see how well it works every time you walk past a store, or simply talk to some female friends in your social circle about it.
Welcome to Compound with René. You can find an overview of the companies I shared a deep dive on in the visualization below.
If you haven’t subscribed, you can join 5,100 readers who enjoy the quality of the deep dives, the process-oriented pieces, the analytical insight, and the valuation discipline, here:
Final Verdict:
Chart-wise, there is no clear sideways base or V-shaped recovery yet, and the stock keeps making lower lows, most recently below €400.
None of the aspects discussed above make LVMH uninvestable in my view. LVMH has multiple issues which have contributed to the share price performance. It remains however one of the best-run groups in the sector, and the question that matters for me is how much of this is already reflected in the price. Currency headwinds, a China reset, store rationalization, and a legal overhang are all visible today. If we are closer to the bottom than the top, the setup could turn out to be more interesting than the current sentiment suggests, especially if the Asian currency effect proves temporary and Louis Vuitton regains its footing in China. I would want to see evidence of both before getting more constructive.
So, pulling the threads together, the price is telling me to be patient. Both long-term uptrends are broken, the stock trades well below two intact downtrends, and none of the volume spikes so far has marked a low that held. Sentiment is clearly poor, and the valuation sits below its historical average. Compared with past crises, however, the multiple is still far from distressed, and the list of risks keeps getting longer.
What would change my mind is a combination of price and business evidence. On the chart side, I would want to see a sideways base form, ideally on fading volume, followed by a break above the January 2026 downtrend line that holds on a retest from above.
On the business side, I would want to see the Asian currency effect prove temporary and Louis Vuitton’s sales in China stabilize. If both show up together, LVMH could turn into the kind of setup in which a bombed-out price requires only modest business success.
Beyond the chart, I would encourage readers to think carefully about two things:
How much LVMH can grow from here and what steady-state, normalized margins look like.
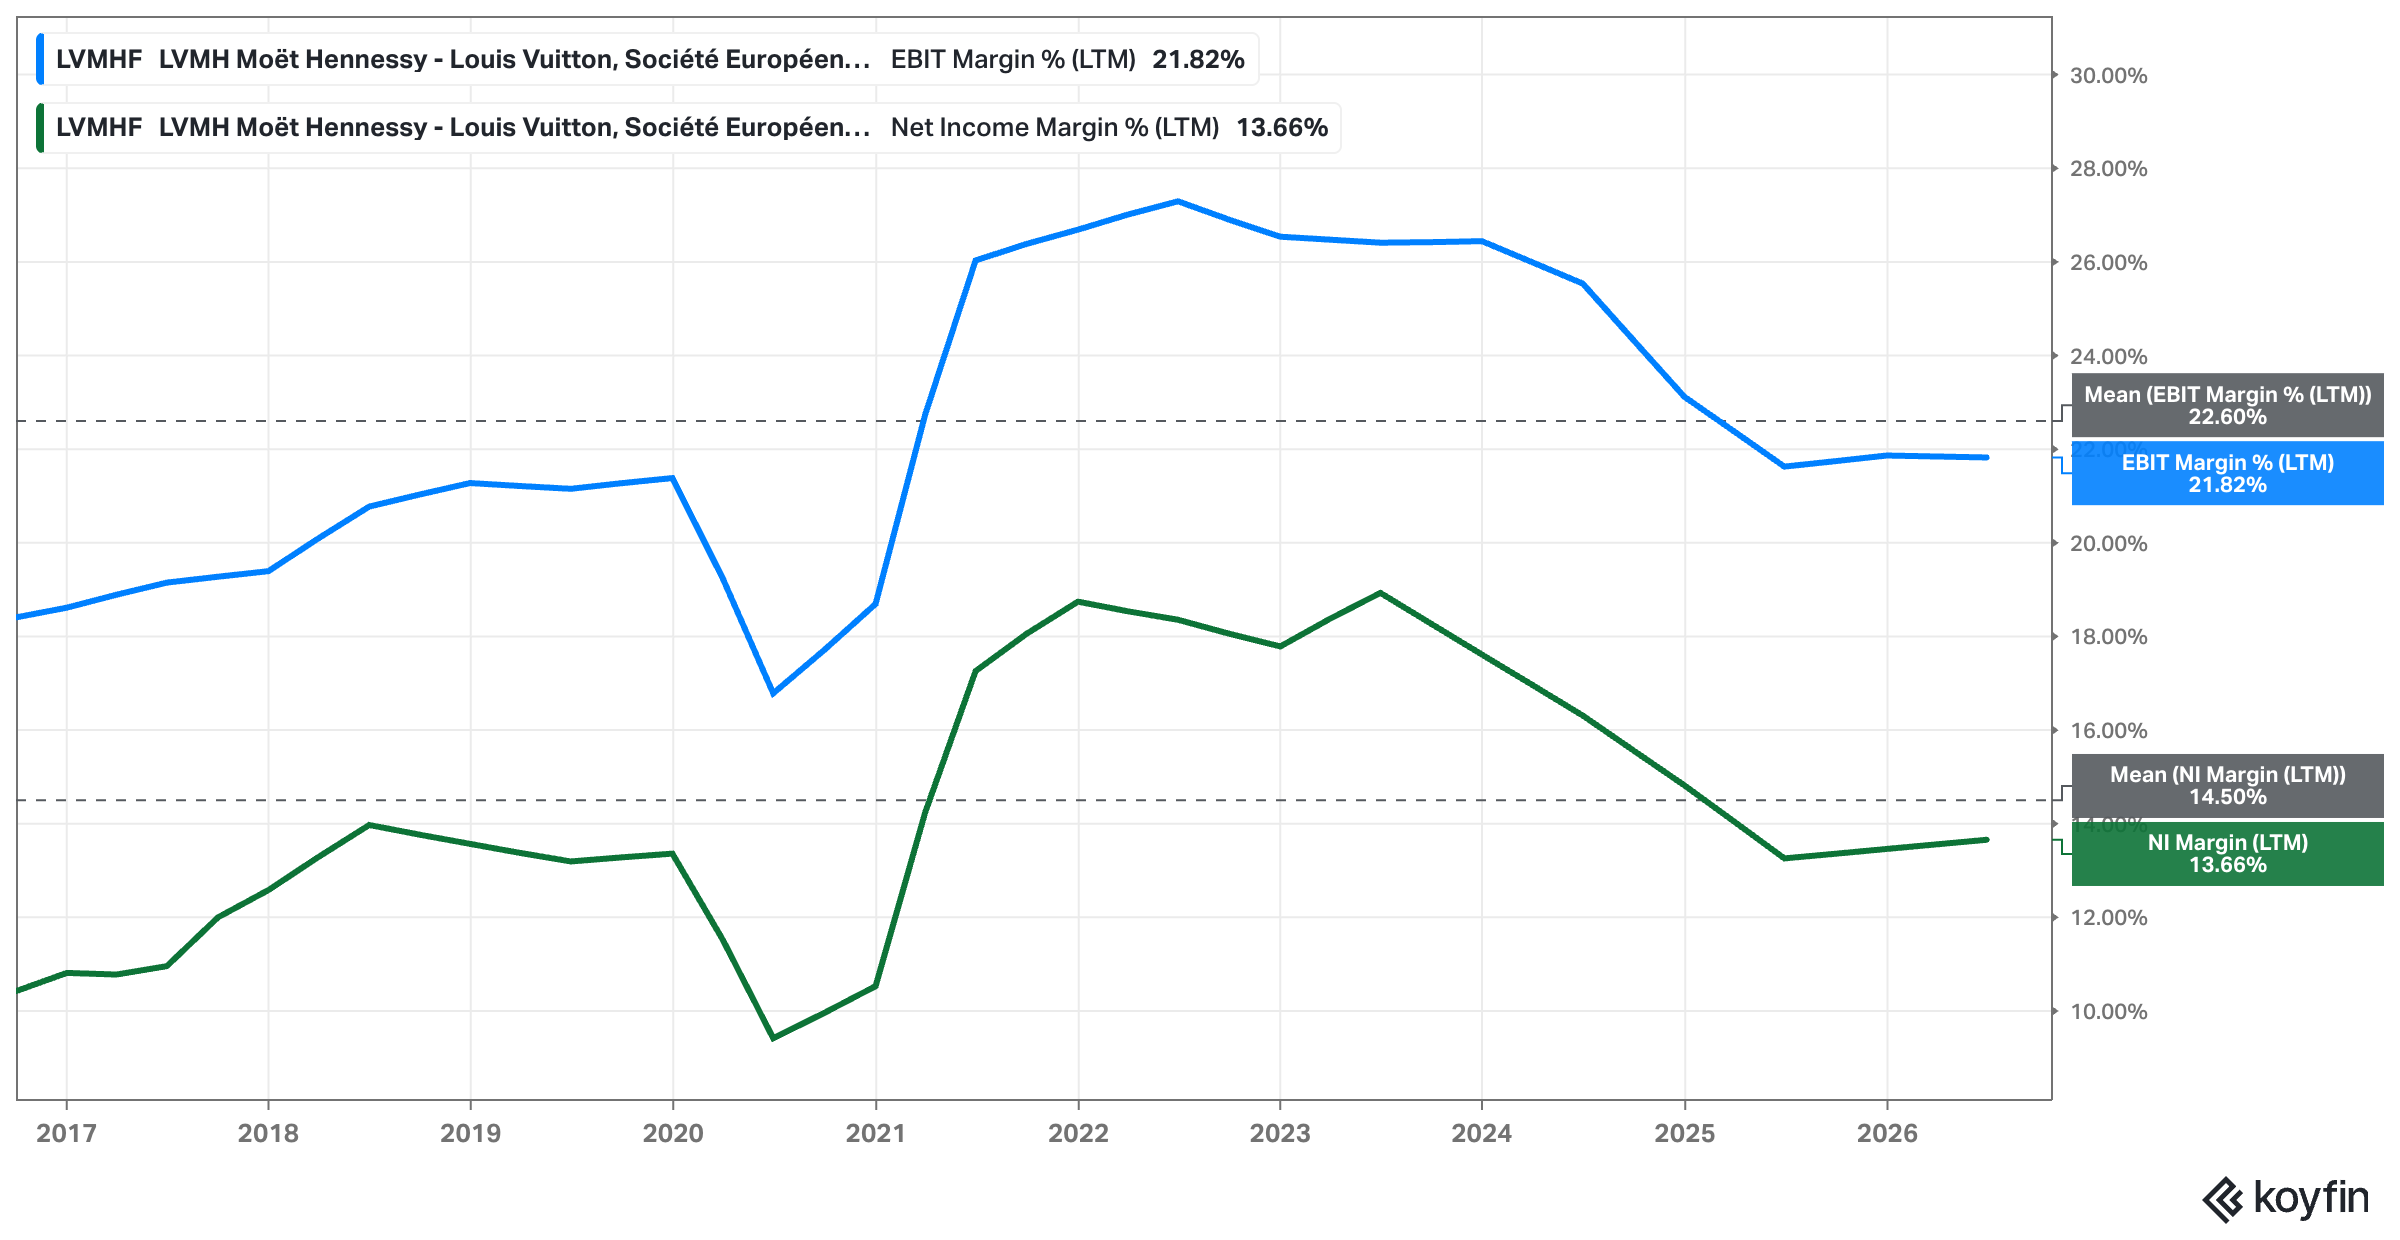
If you believe an EBIT margin of around 20% reflects LVMH’s normalized profitability, then on roughly €80 billion in revenue and a market capitalization of about €187 billion, you are paying around 11.7 times normalized EBIT.
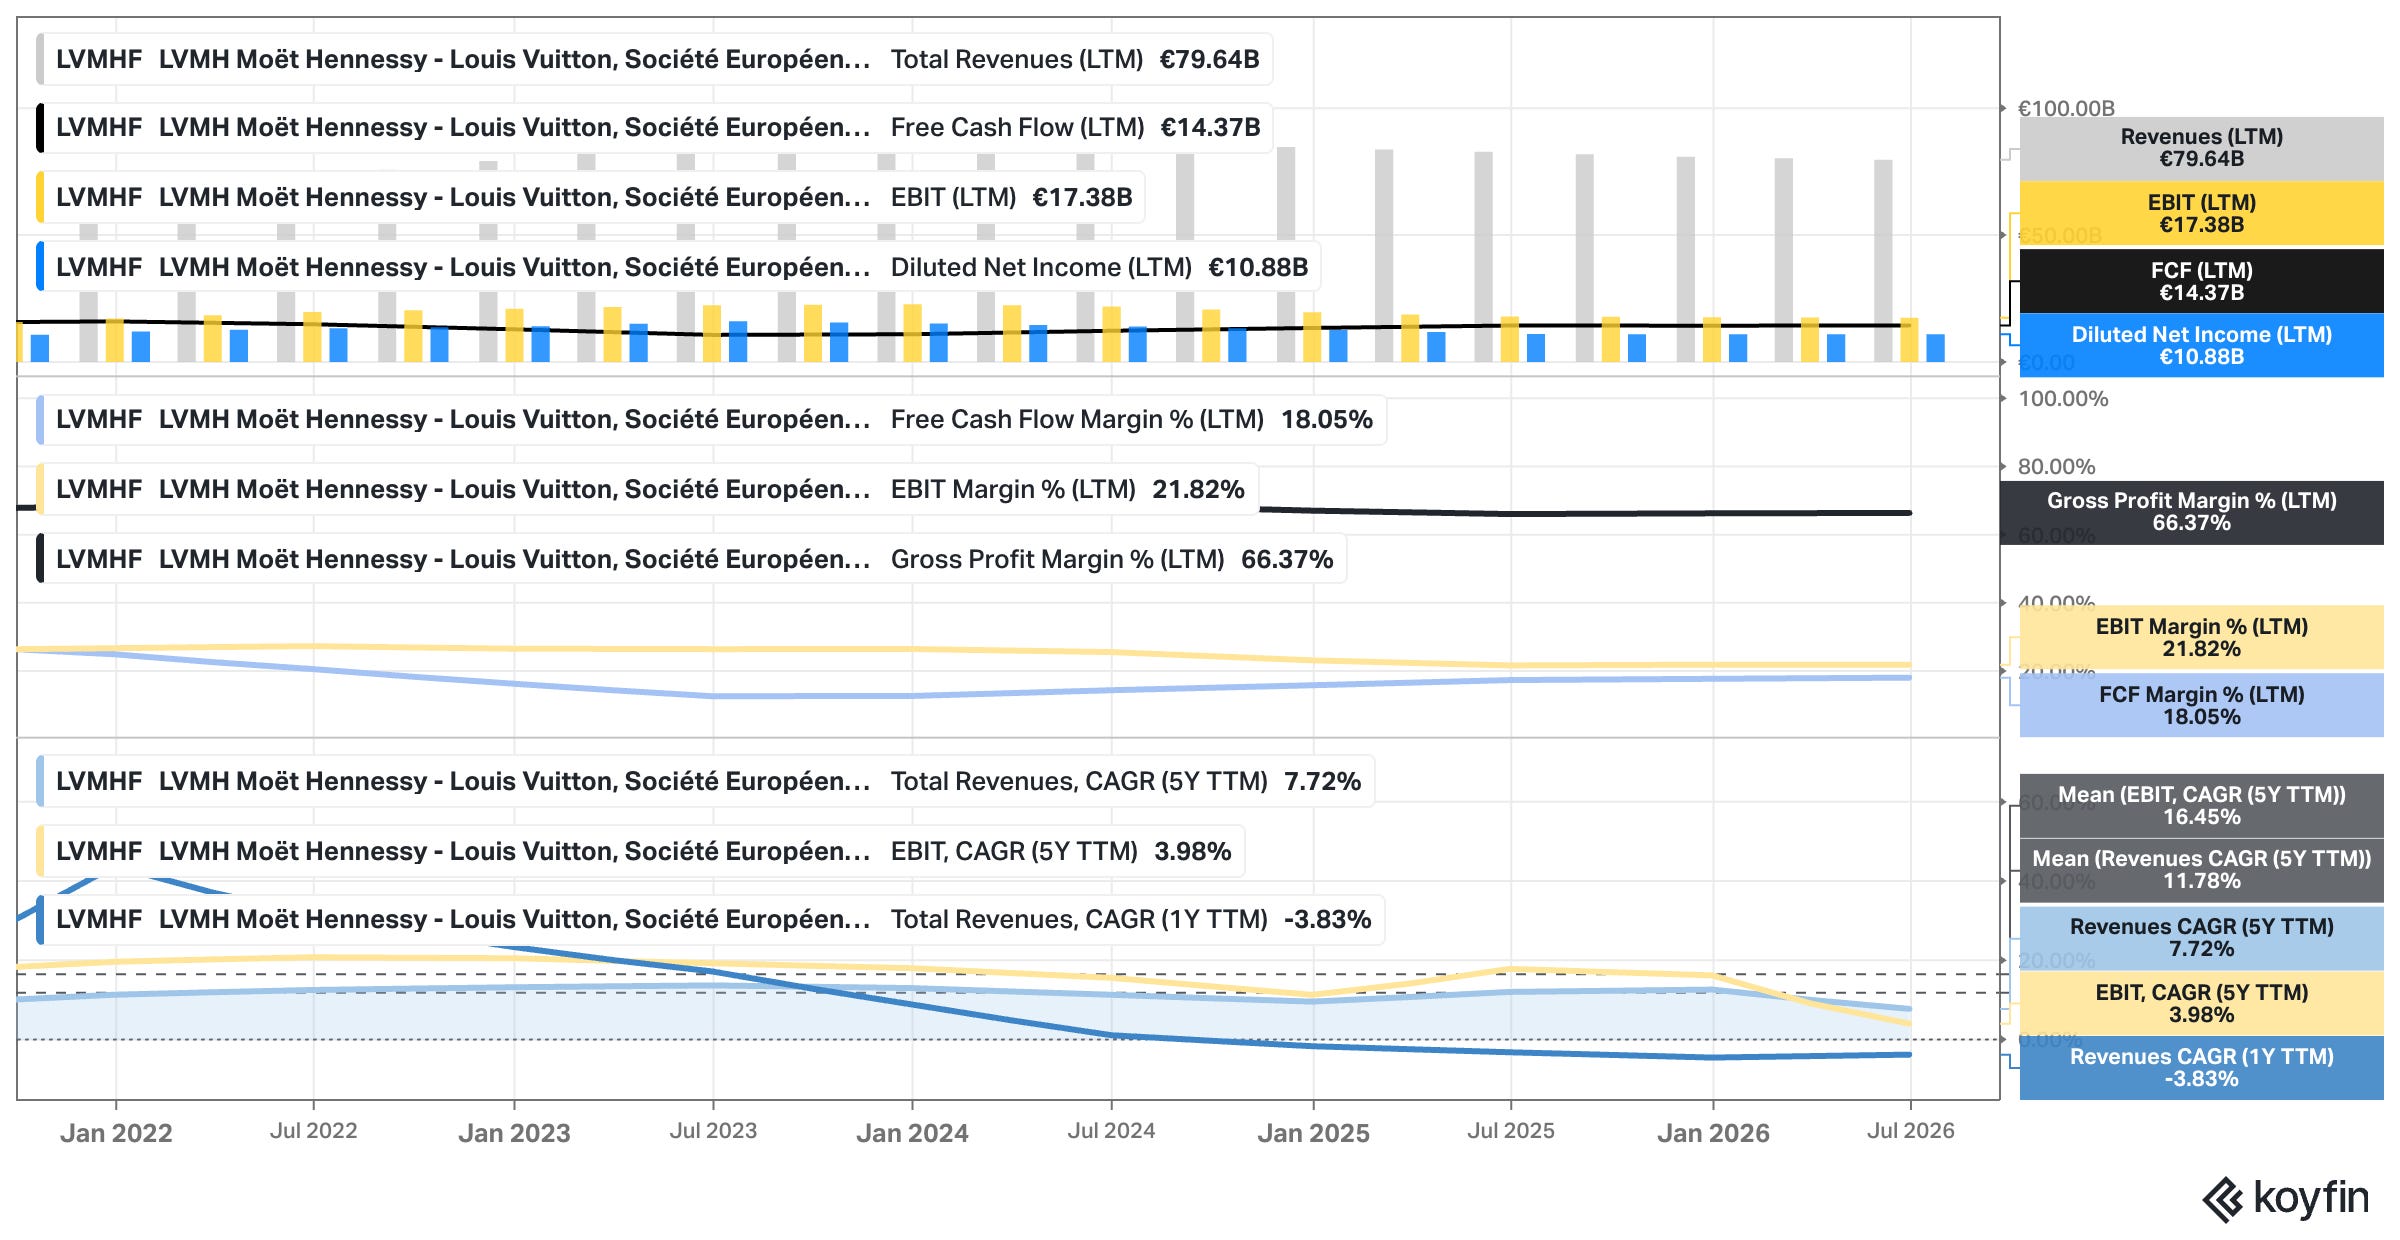
That looks undemanding – unthinkable only a few years ago – for a business of this quality.
It is, however, also worth thinking about the special surtax France imposed on its largest companies. Remember that EBIT stands for earnings before interest and taxes, so an EBIT multiple tells you nothing about how much of that profit the state claims before it reaches shareholders. For most companies that gap is fairly stable and easy to ignore, but a structural change in the tax rate widens it, and with it the distance between the headline multiple and the multiple you are actually paying on owner earnings.
The surtax was presented as an exceptional, temporary measure, yet I am inclined to think it will prove more permanent than initially announced. France, like many of its European peers, is running persistent budget deficits and struggles to legislate true structural reforms; instead, milking large and profitable cash-cow companies are a politically convenient source of revenue, and taxes introduced as temporary have a long history of quietly outliving their original deadlines. If that turns out to be the case, LVMH’s effective tax rate is structurally higher than it was before, and any valuation built on pre-tax profitability flatters the stock.
The tax burden is high, and once you look at the earnings that actually reach owners after taxes, the picture becomes less flattering. At a net margin of around 14%, net income comes to roughly €11.2 billion, which puts the stock at close to 17 times earnings. That is still reasonable if growth can eventually be reignited, though a fair bit further from bargain territory than the EBIT multiple suggests.
I raise all of this because I am a value investor at heart, and if the stock gets cheap enough on a fundamental basis, I will probably not be able to help myself and will buy it regardless of what the chart is doing.
Disclaimer
As of the date of publication the author owns no shares in the company; but that may change. My wife and my parents portfolio, which I oversee, have LVMH in it though and I may thus be biased. The analysis presented in this blog may be flawed and/or critical information may have been overlooked. The content provided should be considered an educational resource and should not be construed as individualized investment advice, nor as a recommendation to buy or sell specific securities. I may own some of the securities discussed. The stocks, funds, and assets discussed are examples only and may not be appropriate for your individual circumstances. It is the responsibility of the reader to do their own due diligence before investing in any index fund, ETF, asset, or stock mentioned or before making any sell decisions. Also double-check if the comments made are accurate. You should always consult with a financial advisor before purchasing a specific stock and making decisions regarding your portfolio.
This is very hard work to find a happy ending for this company and Novo Nordisk. The analysis of WK, AMADY, and TOST all seemed like they needed less work to call a winner. I understand picking up something that's been beat up but is a winner is good, but sometimes if it's too hard find the secret story...
LVMH used to be valued like a growth business with extraordinary margins and cash flows. That was the result of the 2021-23 expansion. But China business and the luxury sector normalized that left LVMH looking a bit weaker on growth and profitability.
The balance sheet is still strong but the regime has changed and high multiples are no longer acceptable. I see it as a HOLD.