Today, I am going to write about the concept of “half a lost decade”-stocks as an adjustment to the “lost decade”-stocks mental model, because the original version doesn’t fit my investing style or the kind of business I want to be a part-owner in.
The adjustment itself is small. What it does to the list of names that end up on my watchlist is not.
A friend told me Mercado Libre might be the next cycle’s loser
I started thinking about all of this while discussing my bet on Mercado Libre with a friend of mine.
His argument is a rule of thumb rather than a company view, and he’d be the first to say so. He avoids overcrowded trades and long-running popularity contests on the grounds that this cycle’s biggest winner tends to become the next cycle’s biggest loser, and Meli fits that description almost too neatly.
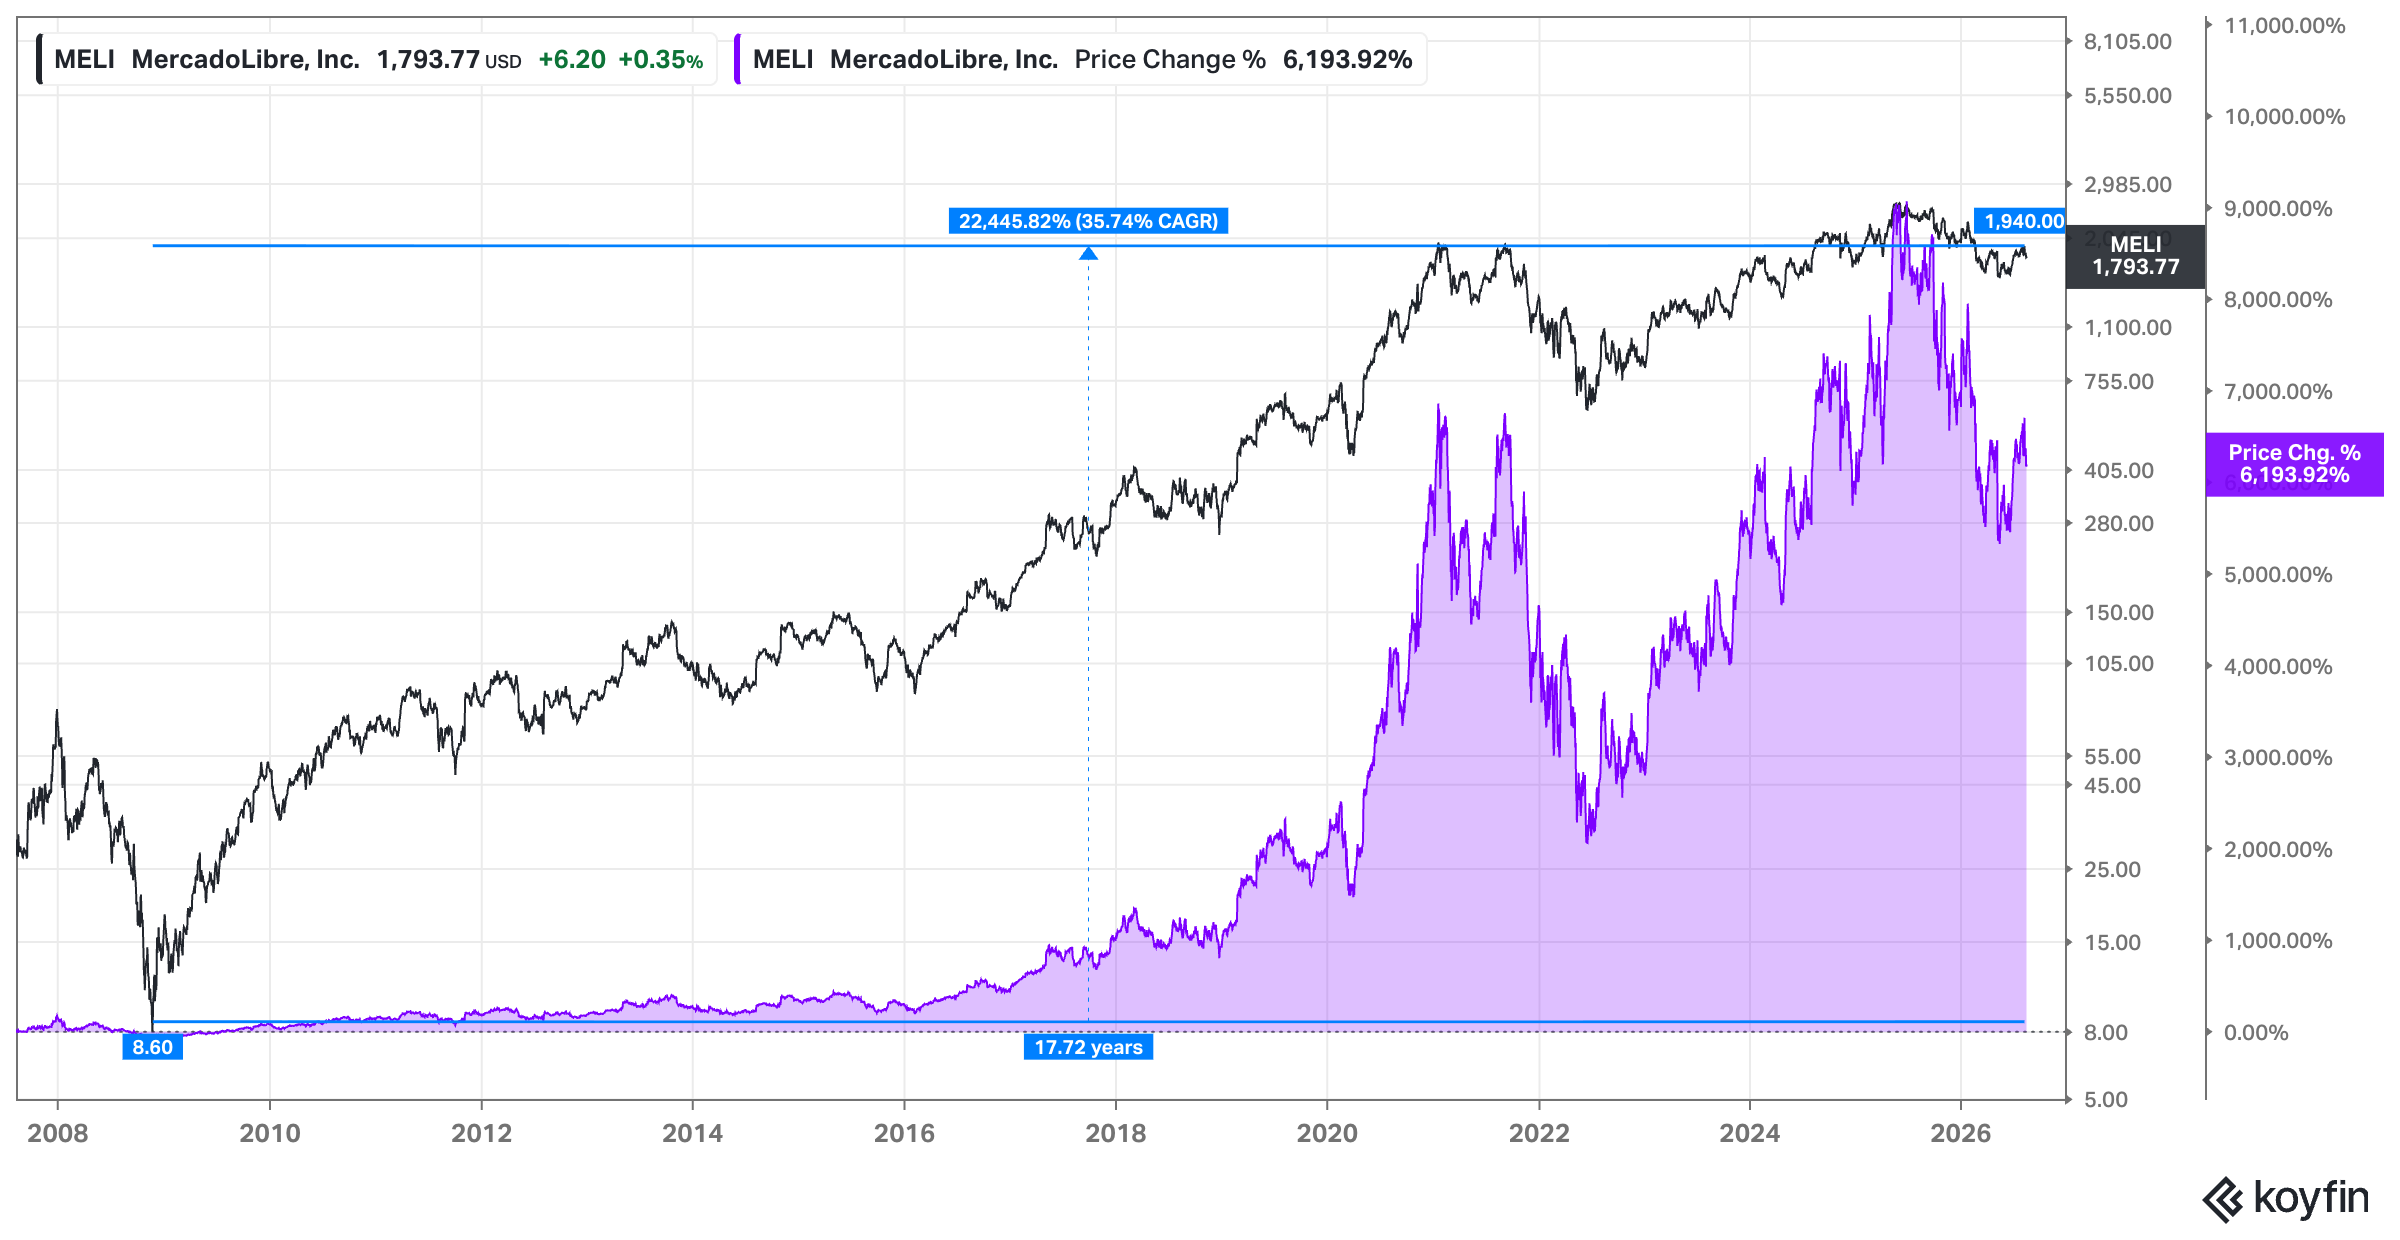
Compounding at roughly 35% a year for 17 years – taking the GFC bottom as the starting point – is the sort of number that makes him nervous rather than excited, because nothing compounds like that forever and the market has to mean revert eventually.
I agree.
Trees don’t grow to the sky. His concern is that Mercado Libre may now experience something like a lost decade, and that the starting point may have been in 2021.
He even made the point that will leave many investors – and MELI owners specifically, I guess – genuinely confused (or even make them angry – I should place a trigger warning here):
Meli could sit completely dead for fifteen years from the 2021 peak, and the stock would still have compounded at 20% a year since the 2009 lows.
That is how much return has already been “pulled forward.”
To be fair, I see his point, and I’m not in strong disagreement with the general point he is making. High growth for a long period of time coupled with absolutely marvellous stock performance, and on top of this, being the darling of the investing community … that’s the kind of setup I tend to avoid too.
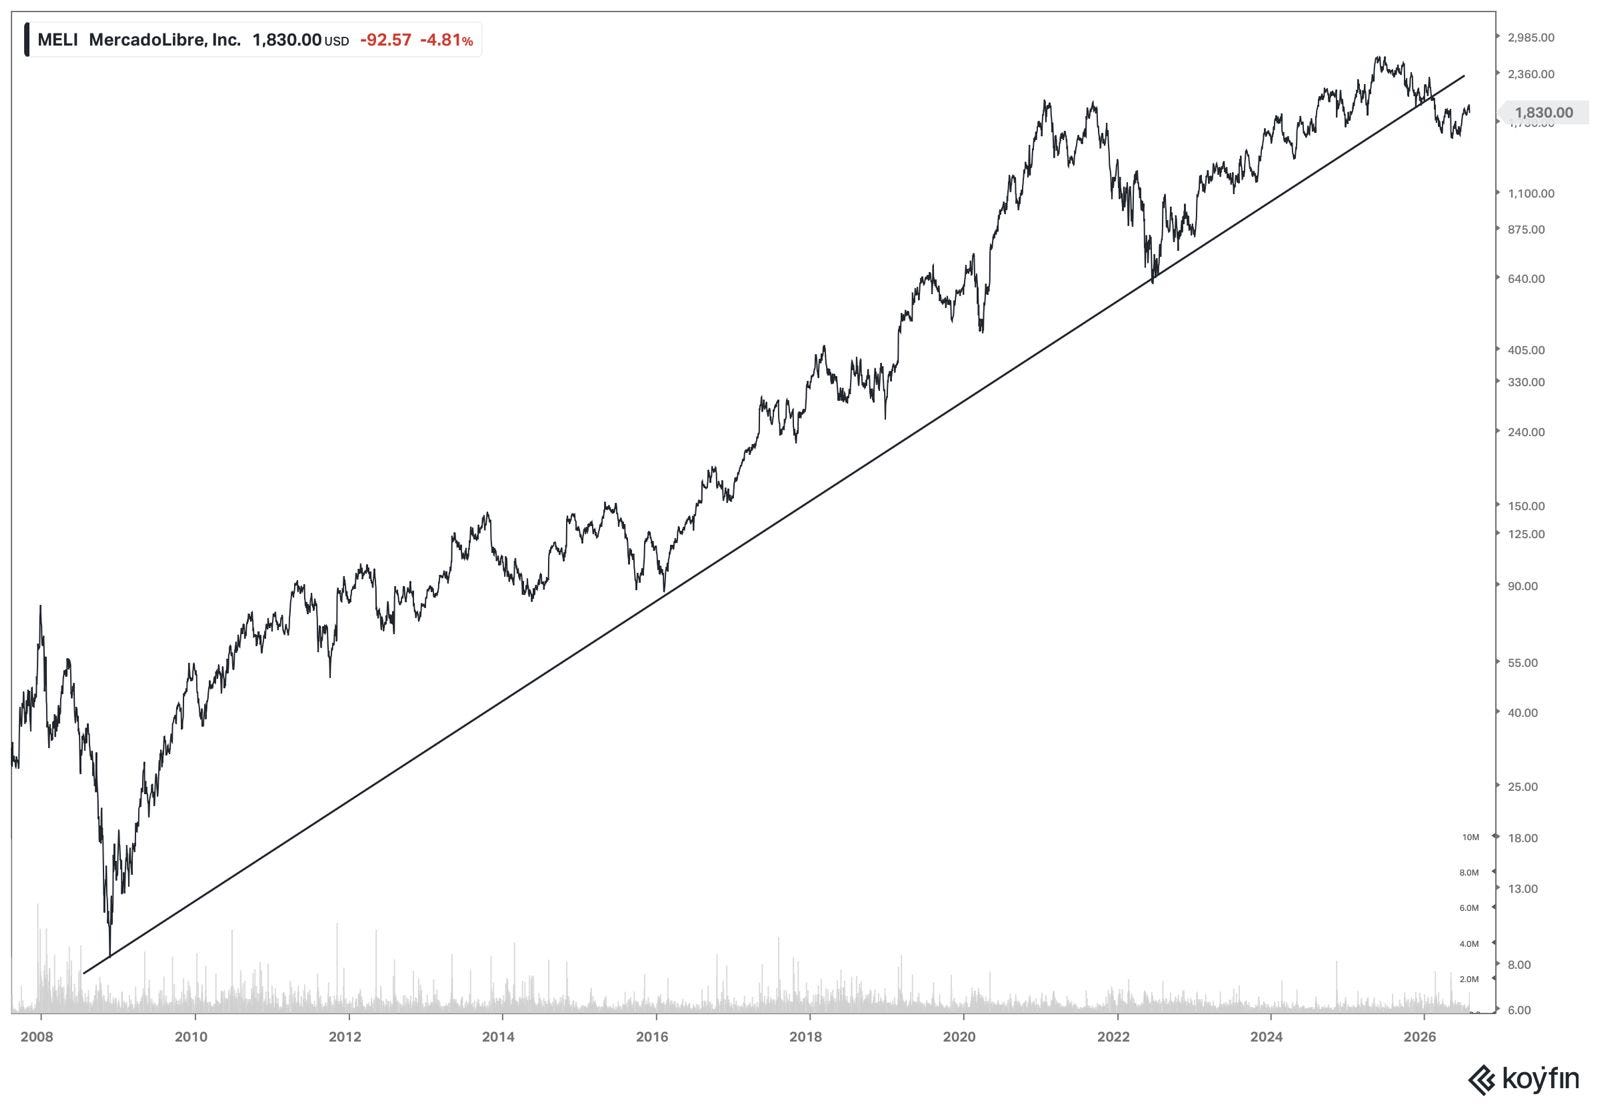
Also, I’ve become more open to the idea that a stock’s price can move in a very different direction from the business for quite a period of time, for all sorts of reasons, and that tracking it matters. Seeing signals in price – like in Meli’s stock (to be discussed below) – can be incredibly powerful too. And I’ve learned the following: a trend in price that has held for several years carries far more information than one that formed a few weeks ago.
You might want to bookmark my perception change framework to read next:
If you had asked me a few years ago whether technical analysis had a place in a fundamentally driven investment process, my answer would have been polite but skeptical.
This ties back to how markets move. Downtrends tend to be faster and more compressed. They often reflect fear, forced selling, or rapid reassessment, and they resolve quickly, because panic has a short half-life.
Uptrends, by contrast, can persist for very long periods. Five, ten, even fifteen years is not unusual for strong businesses. That’s why breaks in long-term uptrends deserve attention. They don’t happen often, and when they do, they usually signal a meaningful change in perception, and they often “break hard.”
As a rule of thumb:
The longer and steeper the uptrend, the more violent the reversion when it finally breaks.
And that’s a pattern you can spot with Meli’s stock too.
At the same time, price is one of many things to look at, and it’s the only input on the list that describes the crowd rather than the company.
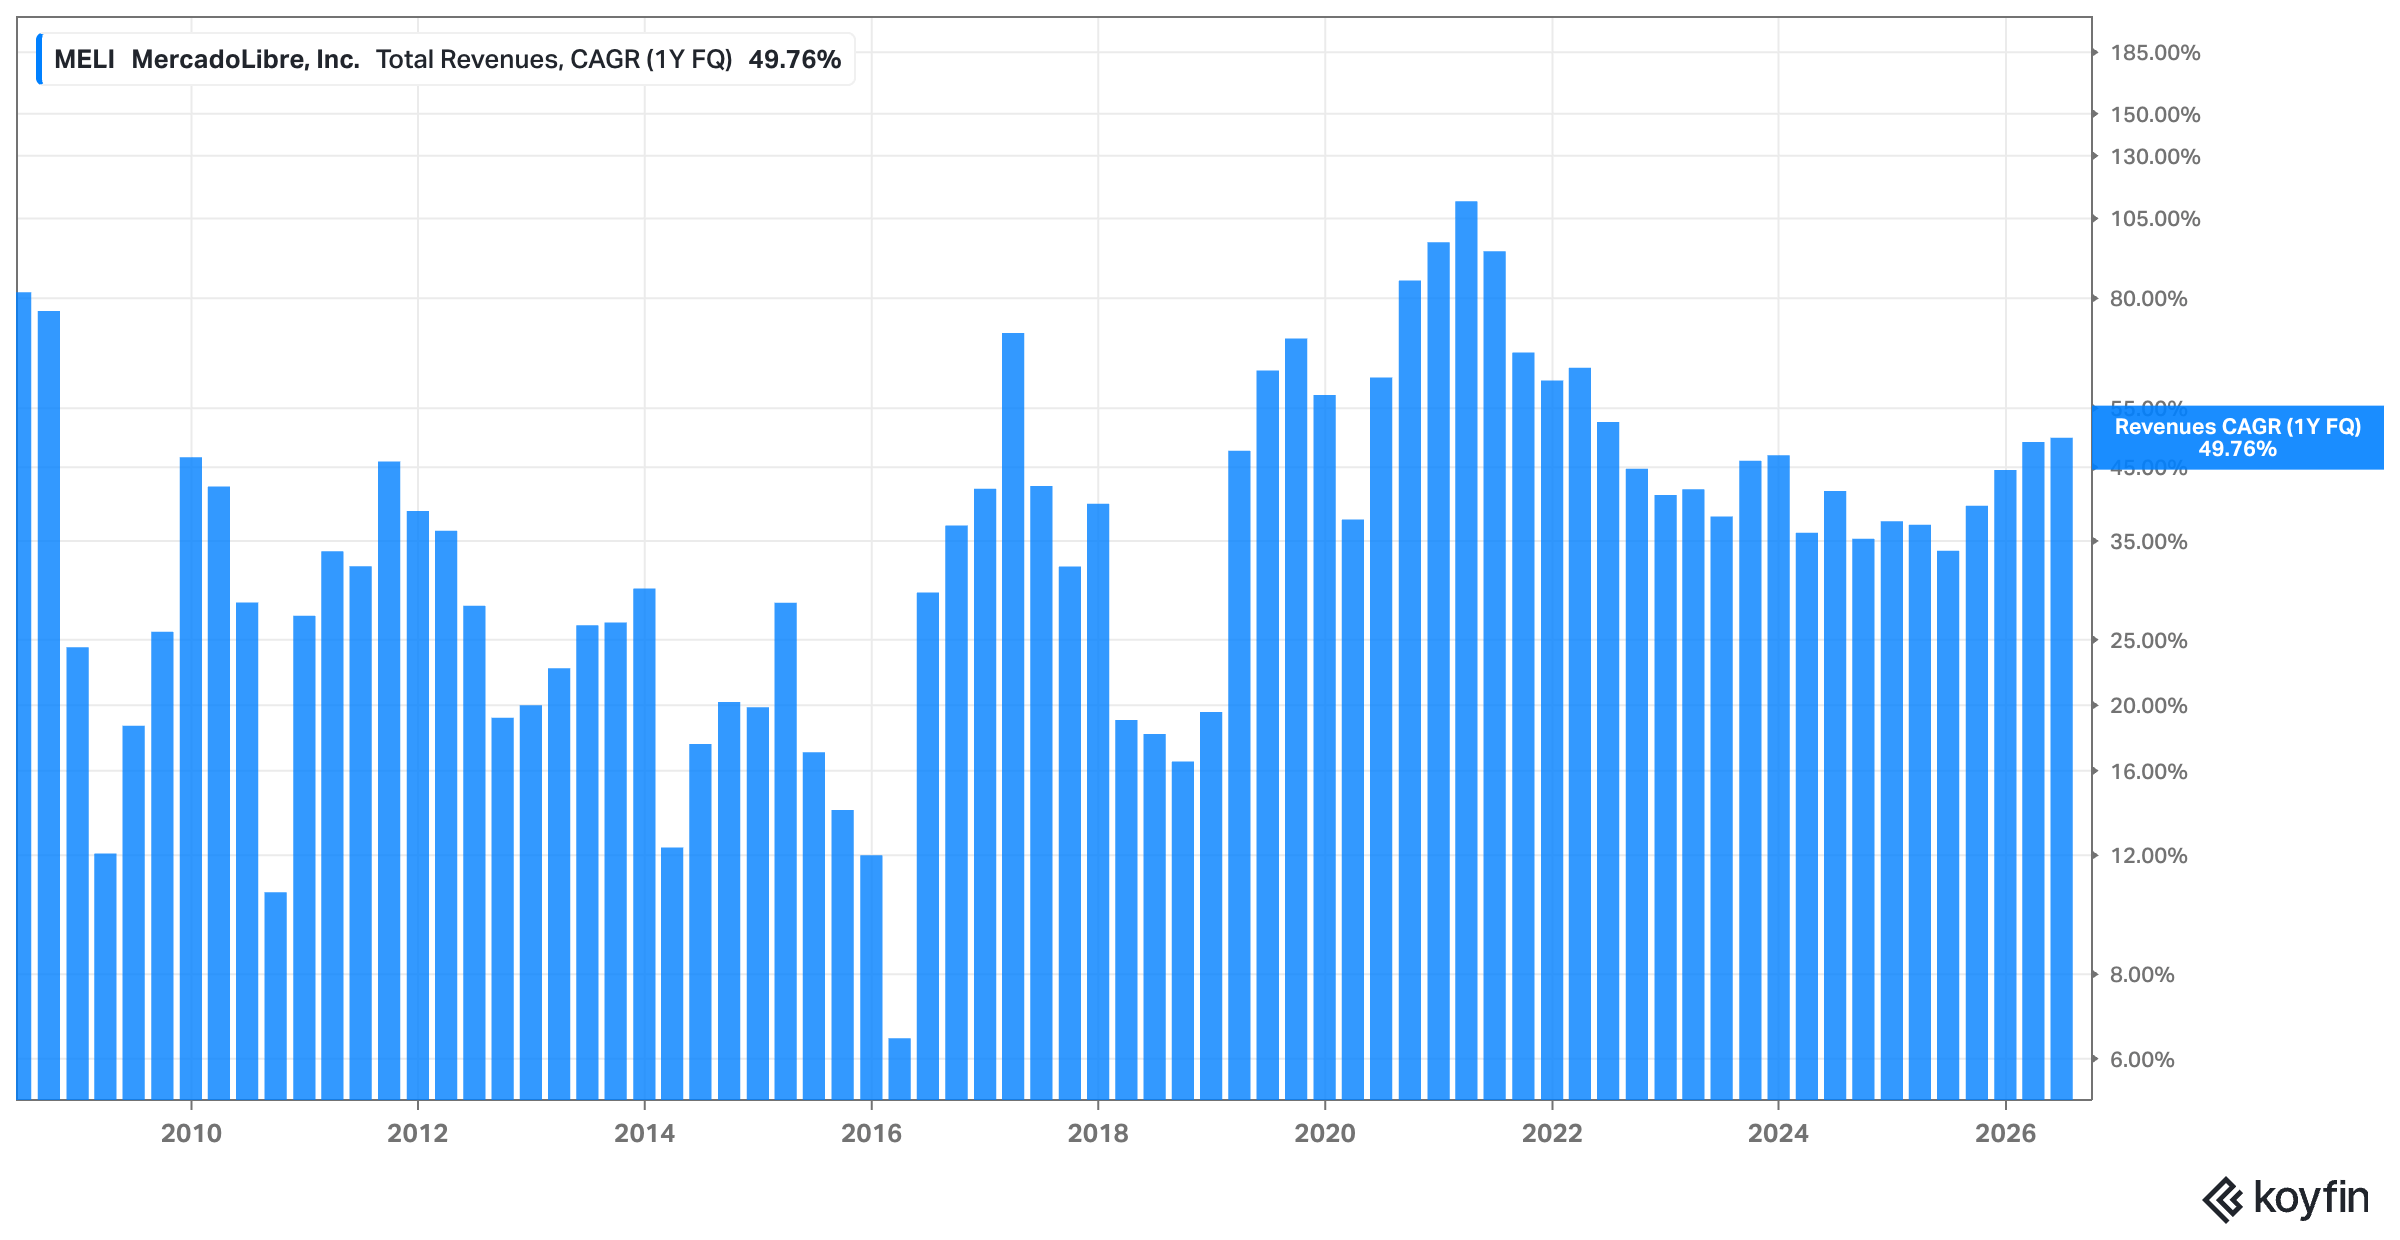
Importantly, Meli has now grown revenue more than 30% for 30 straight quarters (LTM YoY figures).
Thirty!
Look at this chart of beauty – UNFATHOMABLE!
That is an incredible rate of growth, and most people are unable to truly grasp what it means. So take a moment for a thought experiment. Compounding at 30% for 7.5 years, what is $1 of earnings power turned into if you compound at that rate for such a short period of time? The answer is $7.15.
So it’s not like Mercado Libre’s stock just went bananas for no reason. The stock crushed the market because the business crushed the averages and what base rates would suggest.
And the second quarter of 2026 was the fastest quarter in four years. Net revenue and financial income of $10.2 billion, up 50% year over year and 43% FX-neutral.
Let me repeat: 50%!
At an annualized revenue base north of $40 billion. The credit book grew 75% to $16.4 billion, advertising grew more than 70%, and cross-border GMV rose about 60%. Operating margin came in at 6.7%, down 550 basis points from a year ago, and that’s the line most people point at when they call the quarter “soft.”
When I bought Meli earlier this year, it traded at a market cap of about $80 billion. If you believe the company is intentionally under-earning by reinvesting back into the business and earns a 10% margin at steady state, you are paying a lower 20s multiple for a business still growing incredibly fast. In my deep dive, I wrote:
“Looking five to ten years out, operating margins could be materially higher than the depressed levels of 7–10% observed more recently. I would estimate that their current reinvestment posture is intentionally ‘under-earning’ by roughly 4–6 percentage points.”
So if you believe in higher steady-state margins, the starting multiple drops into the teens.
When I think about e-commerce and fintech in Latin America, one name keeps surfacing: Mercado Libre. Founded in 1999, it’s far more than just an online marketplace. Over the last two and a half decades, it has evolved into a fully integrated, infrastructure-heavy commerce ecosystem around logistics, fulfillment, payments, etc. – an indispensable hub where consumers and merchants converge.
Just Don’t Try to Be Brilliant! Hunting for Lost Decades?
But Mercado Libre should really not be the centerpiece of this post!
Rather, it is a perfect example to illustrate the broader concept I want to write about in today’s write-up.
So my friend, he’s hunting for stocks that have just experienced a lost decade. A few months ago I wrongly attributed this quote to Charlie Munger, which is in the same spirit:
“If all you ever did was buy high-quality stocks on the 200-week moving average, you would beat the S&P 500 by a large margin over time.”
After doing some more research, I couldn’t confirm Munger actually said that, but I think he’d underwrite the general spirit of it: Be crazy patient and bet in size when no-brainers present themselves.
So my friend, he tries to play games where the stock has done nothing for 10 to 15 years but has the potential to turn around and do well for the next 5 to 10.
It is not perfect by any means, but history shows those occurrences are much more common.
Charlie Munger said it best. Most people try to do amazingly brilliant things; Berkshire just avoids stupidity and does simple common-sense things, which essentially is buying very cheap (relative to intrinsic value) businesses.
Essentially, all of this is important because stocks are not businesses; they are only a proxy for a business. And stocks go through cycles, and their returns ebb and flow.
And the “ebbs” are far more common than most people assume. J.P. Morgan’s “The Agony and the Ecstasy” looked at every company that was ever a member of the Russell 3000 since 1980, roughly 13,000 names, and found that about 40% of them suffered what the authors call a catastrophic loss: a decline of 70% or more from the peak with no meaningful recovery afterward.
Two-thirds underperformed the index outright. For technology specifically, the catastrophic loss rate was closer to 60%.
So a decade of going nowhere isn’t an exotic tail event that happens to other people’s stocks.
Now clearly, you don’t want to hunt for stocks that never recover. So here’s an important distinction: A lost decade is first and foremost a symptom, and symptoms have different causes. It’s worth separating them, because only some of them are worth buying into.
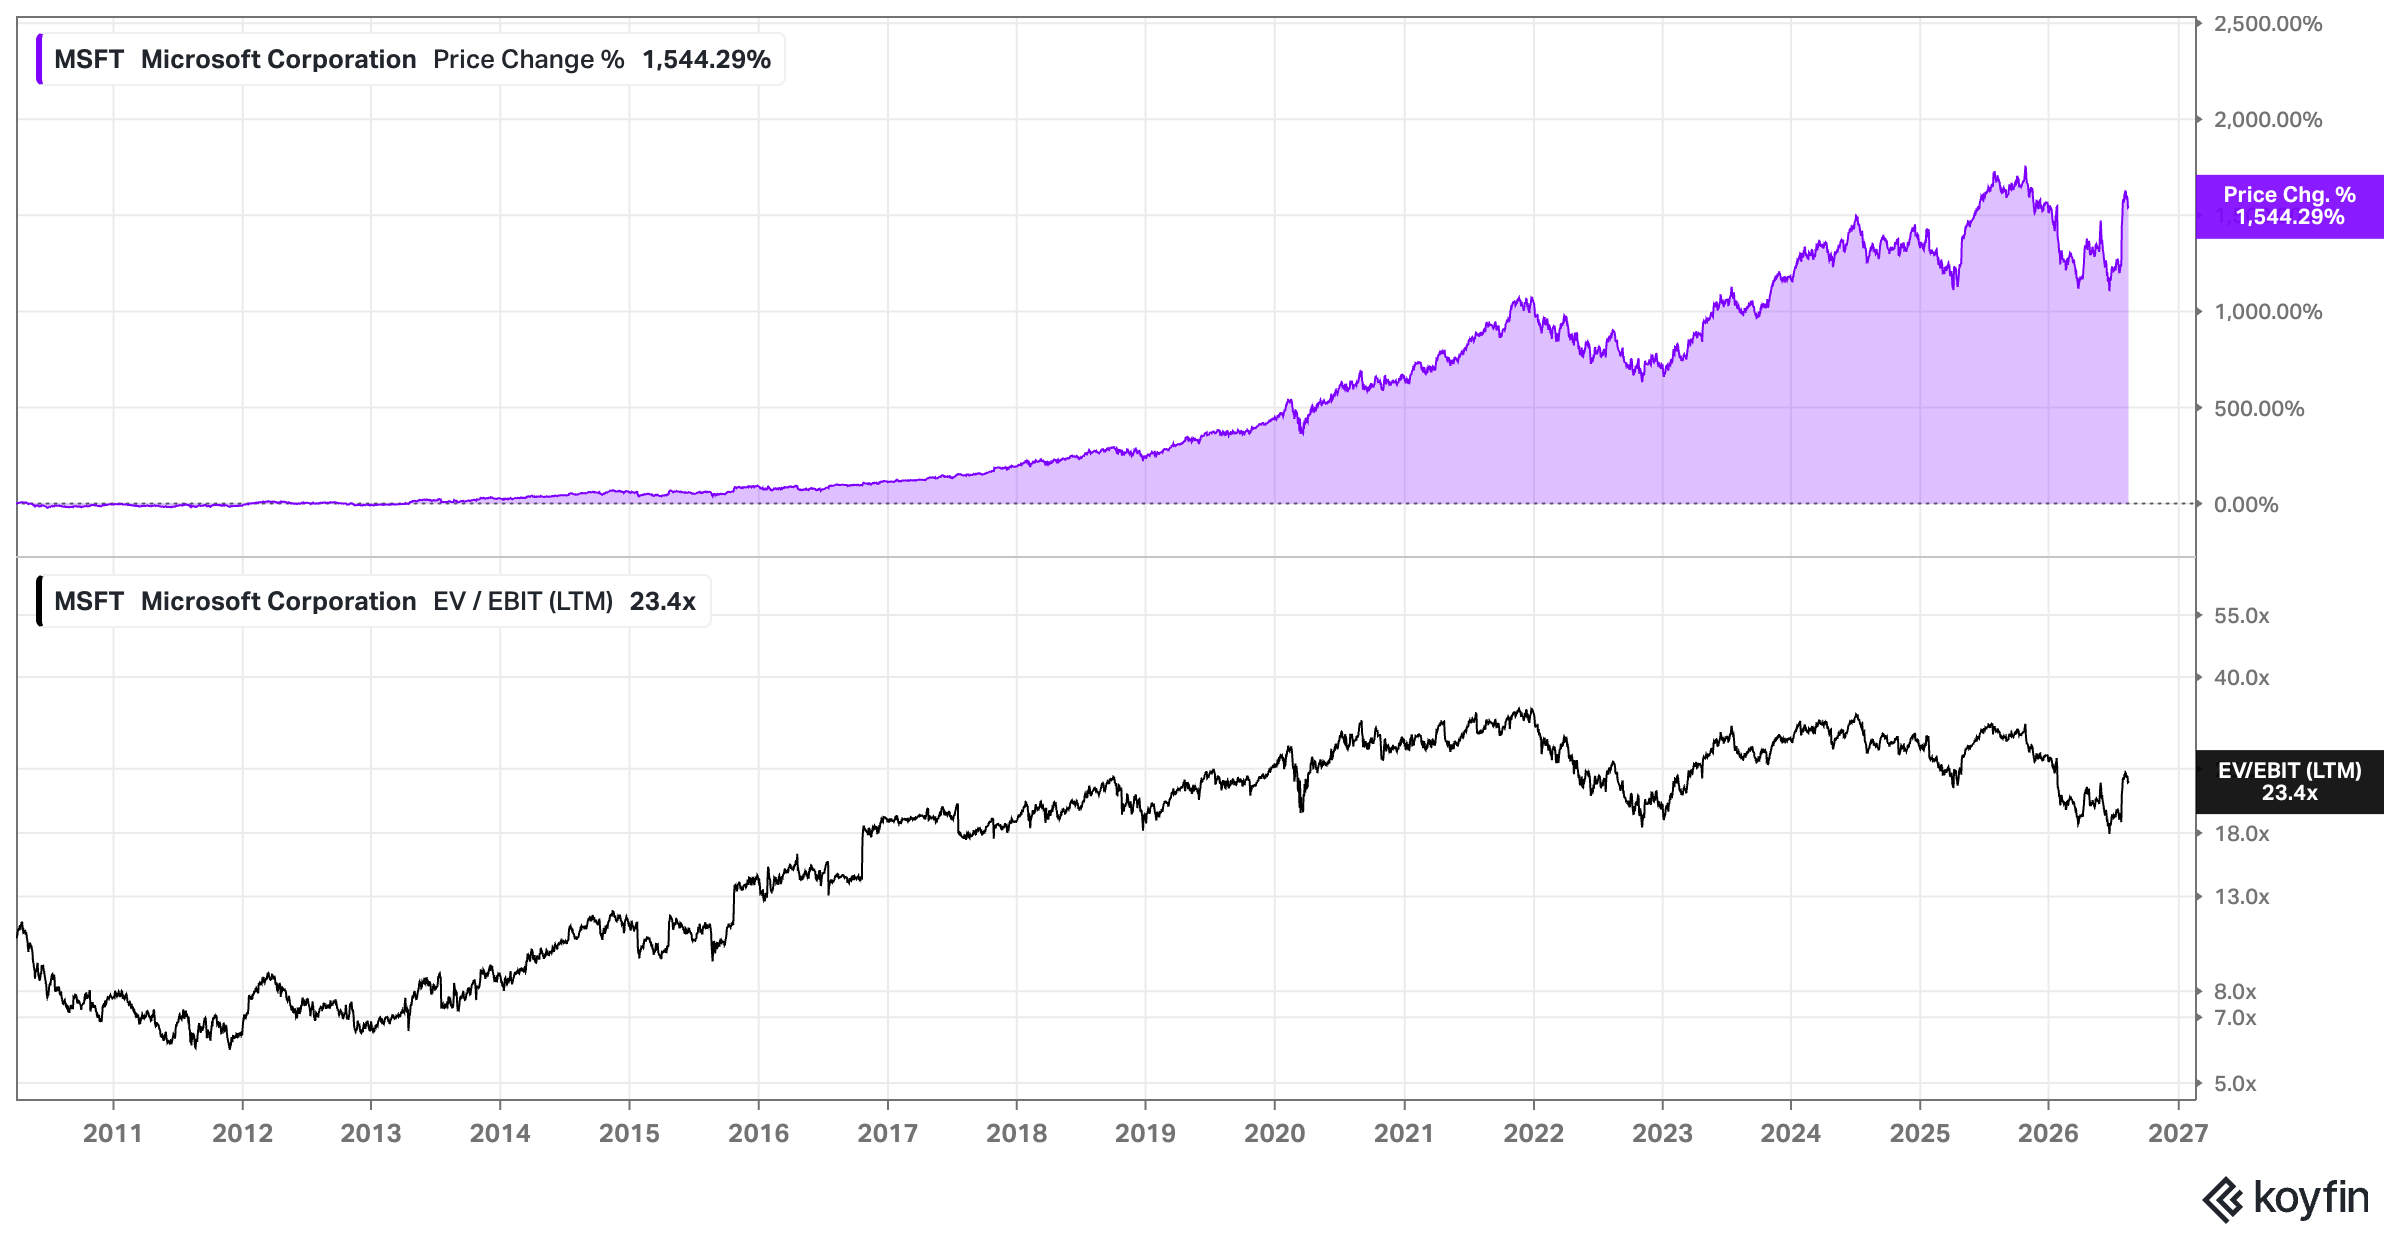
The first cause is that the starting multiple was absurd and the business was basically fine. Microsoft is maybe the most prominent example in the entire market. From 2000 to 2010 it grew earnings per share at 11.7% a year, roughly double the rate of the S&P 500, and the stock still went nowhere until 2013. Nothing broke. But the company started at close to 60 times earnings and then spent thirteen years growing into that number. Whoever bought in 2011 or 2012 at around 10 times earnings collected the entire re-rating on top of the growth in the subsequent years.
This is the version you want.
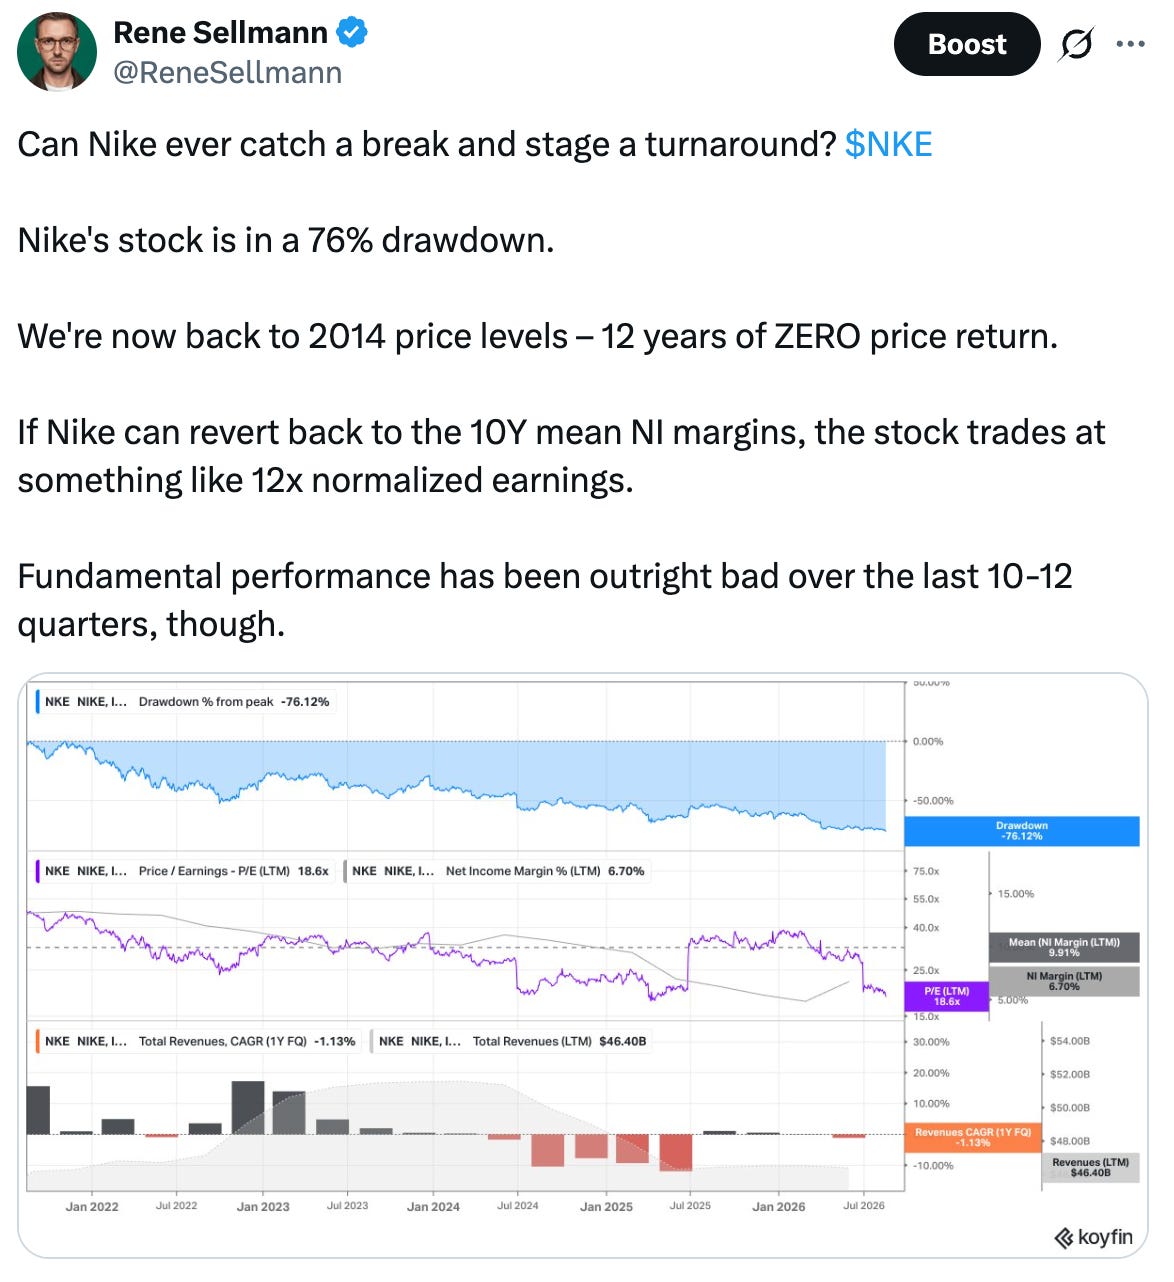
The second is that the underlying business gets genuinely damaged. Technological disruption, a moat that turns out to have depended on one particular distribution regime, commoditization of the product, or a management team that misallocates its way out of a strong position (Nike, wink wink).
The third is capital allocation at the corporate level, which almost nobody talks about in this context. A company can perform perfectly well at the operating line and still hand you a lost decade by buying back stock at peak multiples, overpaying for acquisitions with its own inflated paper, or running enough leverage that it is forced to issue equity at the bottom.
And running underneath all of them is sentiment, which is perfectly capable of being its own cause. Rate regimes reprice long-duration cash flows without asking anyone’s permission. Country and currency discounts get applied and removed for reasons that have nothing to do with the specific company you own. Regulatory overhangs sit on a multiple for years, and can disappear just as quickly as investors slowly forget about them.
Of course it can be a combination of several of these. But ideally, you want to look for stocks where the problem is temporary and solvable, or where uncertainty is elevated but bounded, and the sentiment has just turned completely sour.
Put differently, the multiple will get completely crushed, which in turn may enable you to earn an outsized return when the sentiment flips to the positive again. The software selloff in late 2025 and early 2026 might be a good recent sector example for this, and of course things like that happen in individual stocks all the time too (Adobe, Paycom, Novo Nordisk, Nike to name just a few off the top of my head).
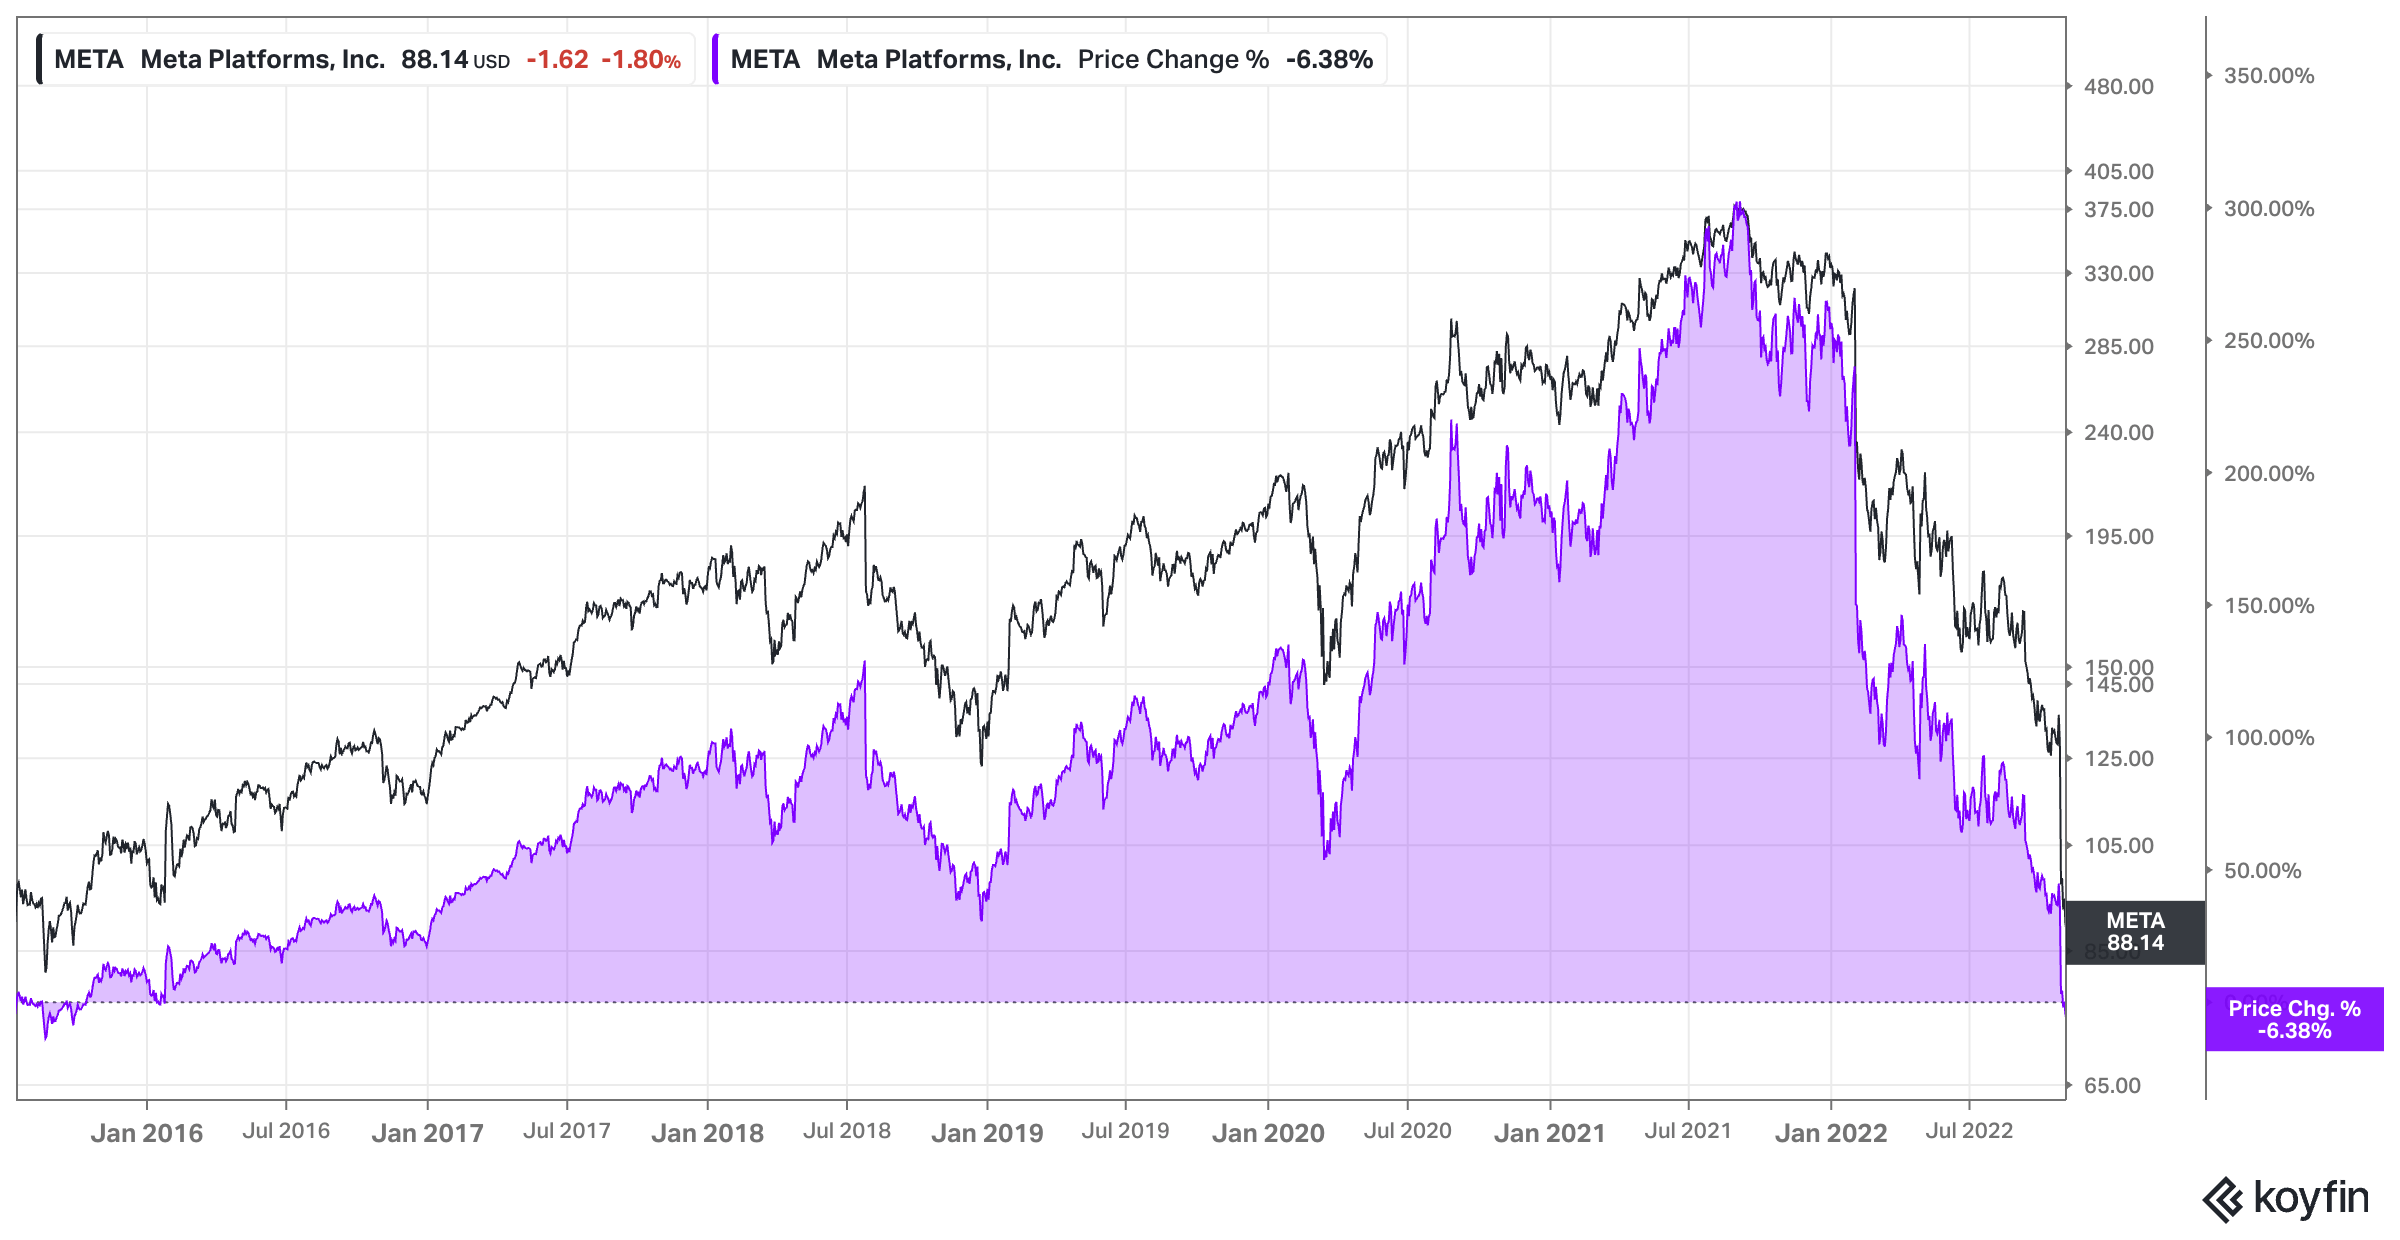
My best investment ever in absolute terms was my bet on Meta. Guess what … At the bottom, the stock had gone nowhere – zero price return – for more than 7 years. What a dud! ;-)
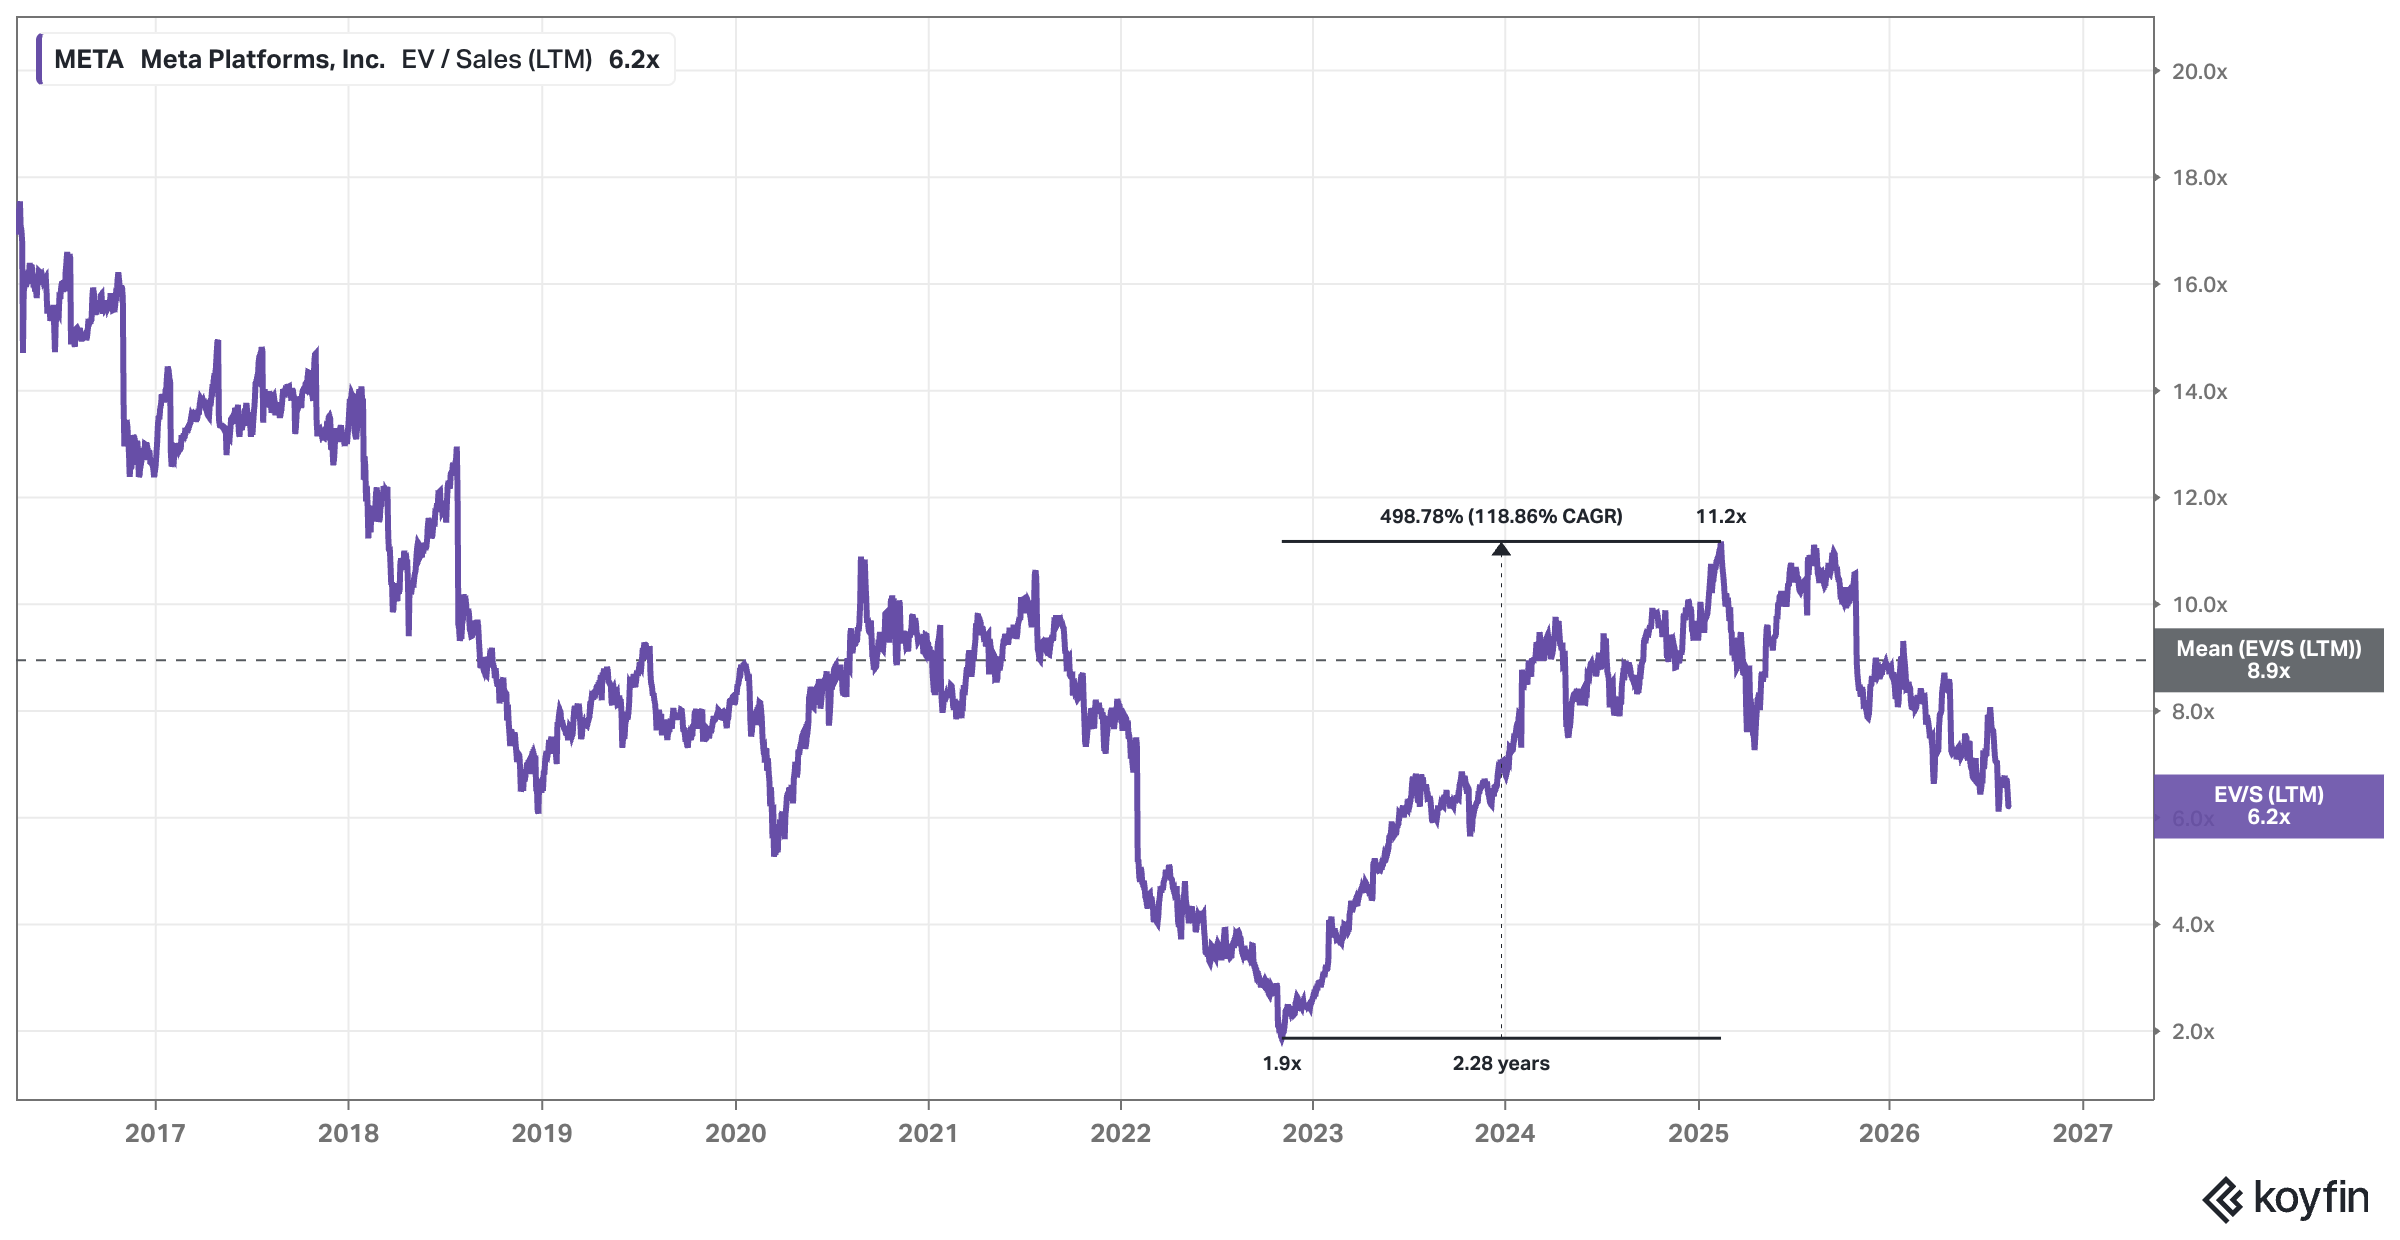
What followed was the sales multiple expanding from 1.9x at the bottom in late 2022 to more than 11x in 2025. Almost a 6x expansion over a little over two years, translating into close to a 120% CAGR.
That’s how you crush the market!
Before we move on:
You can read this article entirely for free. If you find value in this research, consider becoming a Premium Member for less than €1/day to support my work and unlock our full archive and join our growing circle of investors (I highly recommend checking out “The Library” to see what’s inside; you can find it right on the homepage).
Why join the community, you may ask? Our library is fast approaching 70 comprehensive deep dives, providing institutional-level research on some of the world’s most fascinating businesses. Most recently, we’ve dissected companies like Mercado Libre ($MELI),Grab Holdings ($GRAB), Fair Isaac ($FICO), and Topicus.com ($TOI).
As a member, you get:
Complete Access: Every deep dive in our library (65+ and counting). The most thorough analyses you will be able to get your hands on (including downloadable models).
Access to my 150+ Global Watchlist: And How To Use It to Outperform the Market!
Slide Decks: Every deep dive now comes with a companion slide deck. It’s the whole argument in compressed form – the hypothesis, the business, the competitive position, the valuation, and the case against – for the days when you don’t have an hour to spare but still want the shape of the thing. Paid subscribers get both, the long piece and the deck.
More Content: Company updates; AI tools I built (like my AI superforecaster); powerful valuation spreadsheets, frameworks, and processes; regular portfolio updates (insights into my investing decisions); market commentary; etc.
The WhatsApp Community: Real-time discussion and networking with like-minded investors.
Digital Investing Conferences: About three times a year, we also hold digital conferences where members present and share stock ideas, and discuss broader themes, and we’d love for you to join in!
Incredible Value: Full access to all of this for less than 1€/day.
Still not convinced? I received this lovely feedback just yesterday:
Why the Concept of “Lost Decade Stocks” Should Be Internalized
Look, I’m the biggest proponent of placing a lot of emphasis on business quality. It’s top of mind for me all the time. And when I appeared on the podcast of The Dutch Investors – (listen to it here) –, I was asked what quality actually means to me?
I could write multiple books on this, but at a very high level, what I said is
“predictable and durable above-average intrinsic value growth.”
And in the quality investing bubble specifically, people point out that changes in multiples don’t matter over the long term. One quote you frequently encounter then is again from Munger, who rightly and famously stated:
“If the business earns 6% on capital over 40 years and you hold it for that 40 years, you’re not going to make much different than a 6% return – even if you originally buy it at a huge discount.”
Yes, he is right. BUT (!) 40 years is a looong time. Almost nobody actually invests over 40 years. We invest over the 15 or 20 years in which we have capital to deploy, a career to fund the fun, and the stomach to hold.
And what you may overlook is how big of an impact multiples do have for a loooong period of time! (20 years plus) Let me just illustrate it for you:
If the multiple you buy the stock at expands by 50%,
... over five years, the CAGR contribution is 8.45%
... over ten years, the CAGR contribution is 4.14%
... over twenty years, the CAGR contribution is STILL more than 2%
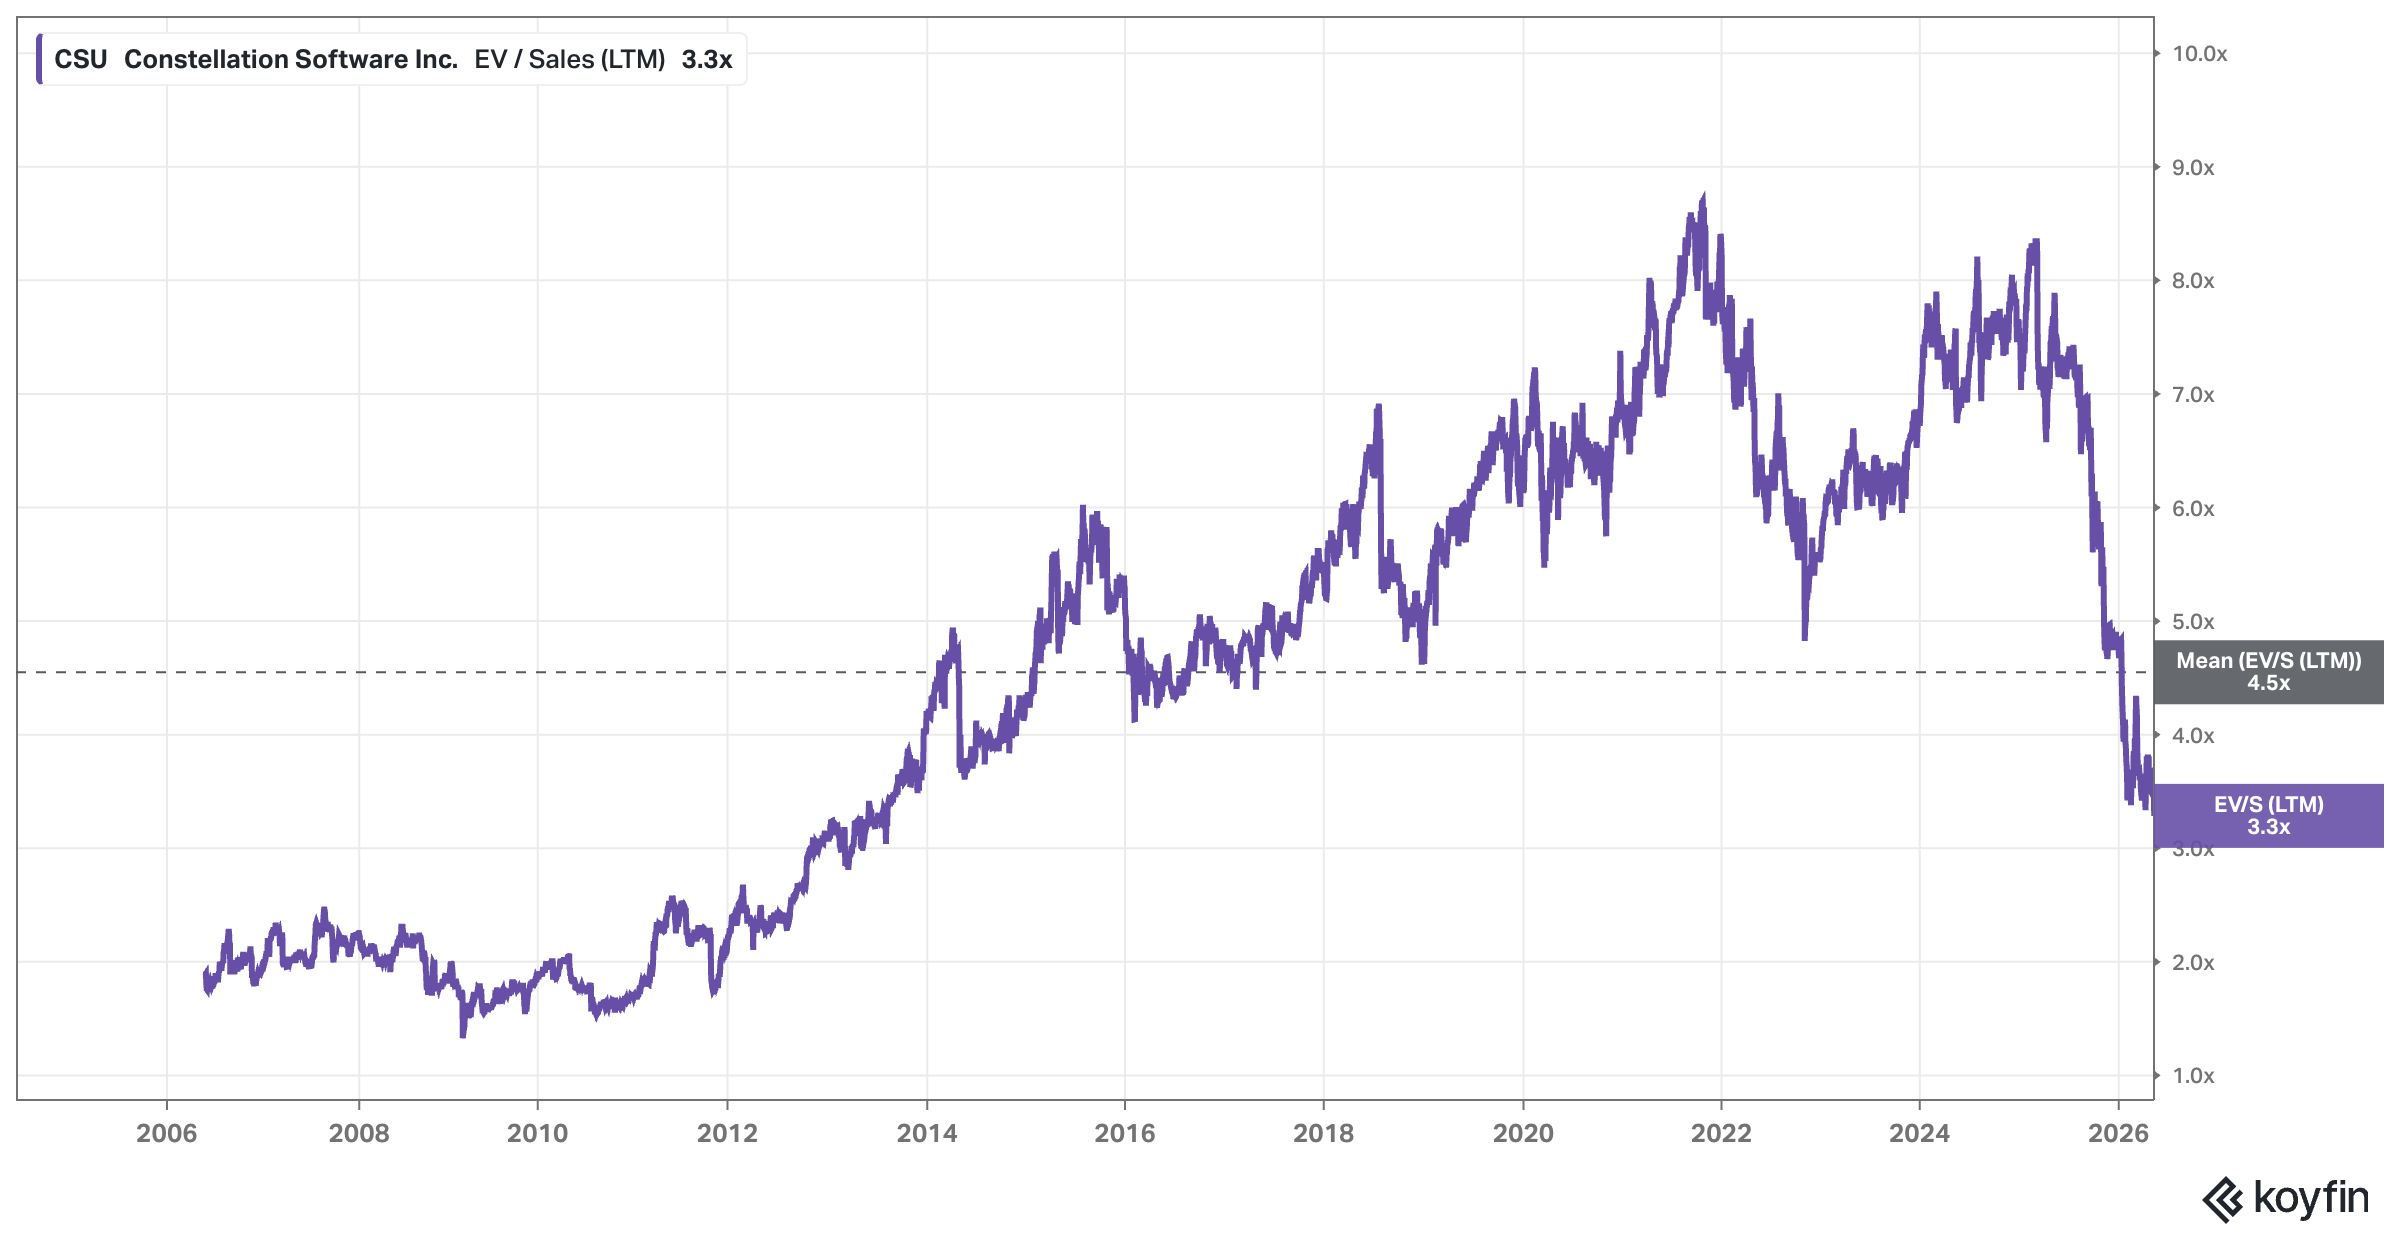
Let’s say you can find a stock where the multiple expands by threefold. If you buy cheap enough, that happens more than you think! It’s effectively a 5x earnings multiple stock expanding to a below-average multiple of 15x, or a 9x earnings multiple stock going to 27x. Constellation Software’s sales multiple went from below 2x (1.6x) to almost 9x (more than a 5x!).
If the multiple you buy the stock at expands by 200%,
... over five years, the CAGR contribution is 24.6% (!!!)
... over ten years, the CAGR contribution is 11.6% (that alone is a market-beating performance btw!)
... over twenty years, the CAGR contribution is STILL more than 5.65%
Two things are worth pulling out of those numbers before we move on.
Patience is required to get the re-rating, and patience is also what taxes it. The same 200% expansion is worth 24.6% a year over five years and 11.6% over ten, so half the annualized benefit evaporates simply by taking twice as long to arrive.
The second is that these are contributions, not returns. They stack on top of whatever the business itself does. A threefold re-rating over five years alongside a perfectly ordinary 15% earnings growth rate is a 43% CAGR.
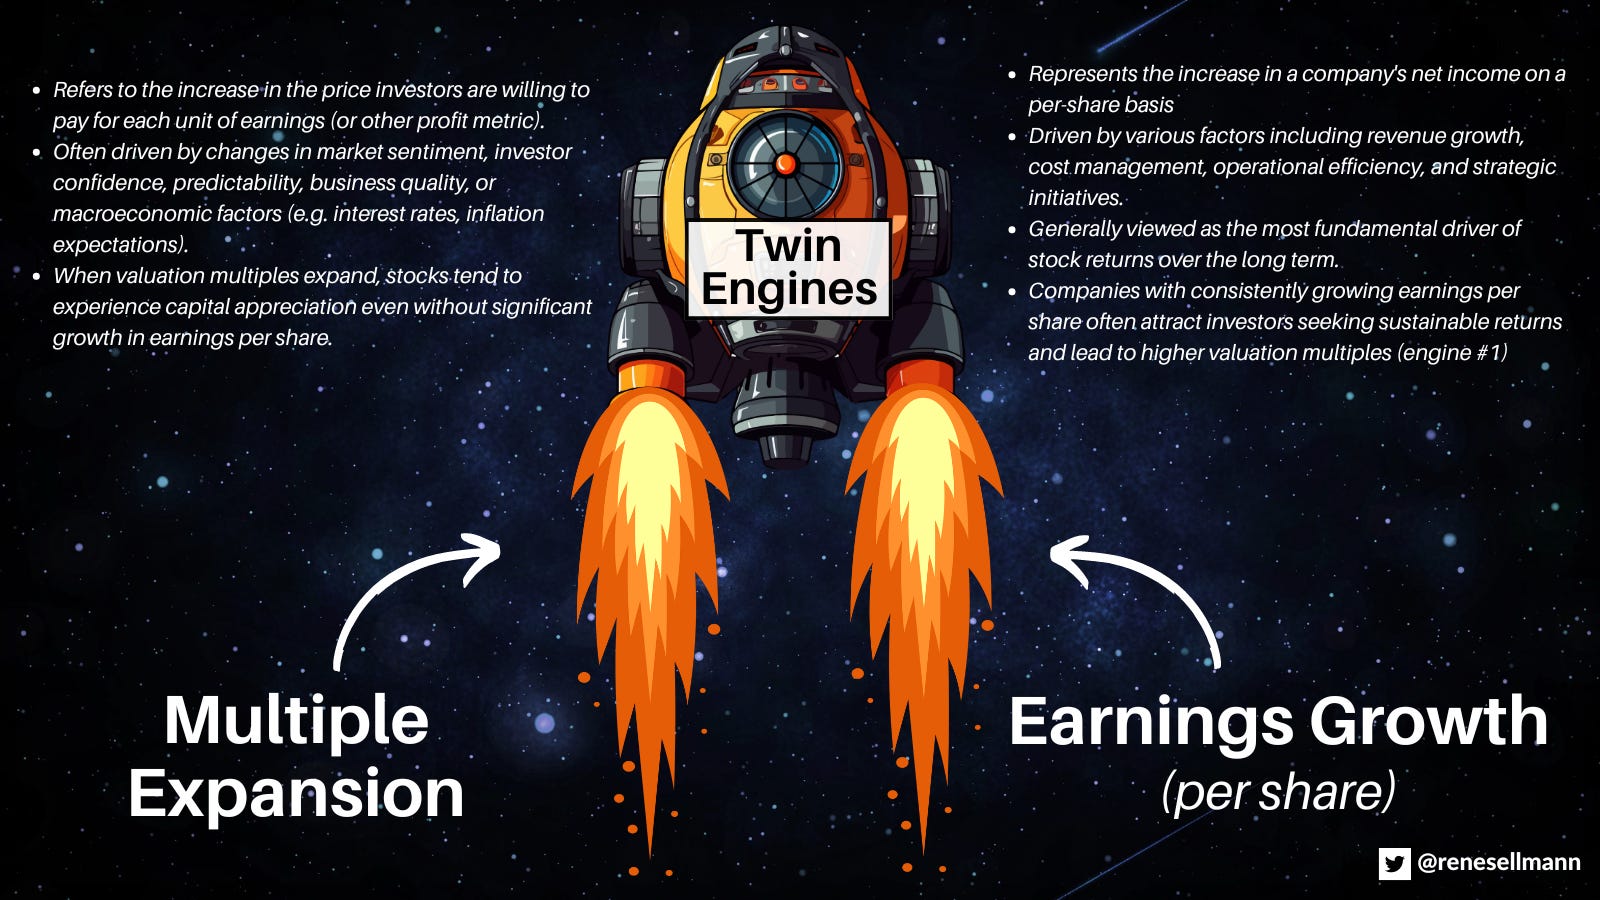
That’s what happens when the two engines – Chris Mayer’s concept of the twin engines – fire at once, and it’s the entire reason I care about entry multiples despite spending most of my time thinking about underlying business quality.
So if you want to consistently beat the market and not wait until you’re 90 to get rich, you really have to buy reasonably cheap (or even better: dirt cheap!) or earnings have to grow damn fast for a sustainable period of time (like Meli did, but that’s less reliable to get right than just buying a pretty damn cheap stock).
And importantly, all of this works in the opposite direction too! So if you pay too high a price, the business can grow and grow and grow, compound at 15% for a decade, but if the multiple gets cut in half, you still end up underperforming the market.
Also, while all of this sounds so easy in theory, chances are you will not perfectly time the bottom (and you might have to sit through a further 20-30% drawdown, or more), and/or it takes two years for the momentum to swing. Thus, in practice, this can be really hard.
In theory, theory and practice are the same. In practice, they are not.
The rest of this post is FREE to read. I only ask that you subscribe, which costs nothing and can be undone with a single click whenever you like.
The wall also helps keep my writing from being freely scraped by AI crawlers, so I hope you understand the small extra step.
In return, you get every deep dive, earnings review, and process piece I publish, straight to your inbox.
Subscribe for free to continue reading
Enter your email and get every post from Compound with René.