

You can read this article entirely for free. If you find value in this research, consider becoming a Premium Member for less than $1/day to unlock our full archive and join our growing circle of investors (I highly recommend checking out “The Library” to see what’s inside; you can find it right on the homepage).
Why join the community, you may ask? Our library is fast approaching 70 comprehensive deep dives, providing institutional-level research on some of the world’s most fascinating businesses. Most recently, we’ve dissected companies like Mercado Libre ($MELI), Grab Holdings ($GRAB), Fair Isaac ($FICO), and Topicus.com ($TOI).
As a member, you get:
Complete Access: Every deep dive in our library (65+ and counting).
More Content: Company updates; powerful valuation spreadsheets, frameworks, and processes; regular portfolio updates (insights into my investing decisions); market commentary; etc.
The WhatsApp Community: Real-time discussion and networking with like-minded investors.
Digital Investing Conferences: About three times a year, we also hold digital conferences where members present and share stock ideas, and discuss broader themes, and we’d love for you to join in!
Incredible Value: Full access to all of this for less than $1/day.
If you want to see the level of research we provide before committing, the following deep dives are, for instance, free to read (access them via The Library):
InPost ($INPST) - generated an IRR of >400% as an acquisition offer emerged 2-3 months post-write-up
DigitalOcean ($DOCN) - up 5x in less than a year post write-up release
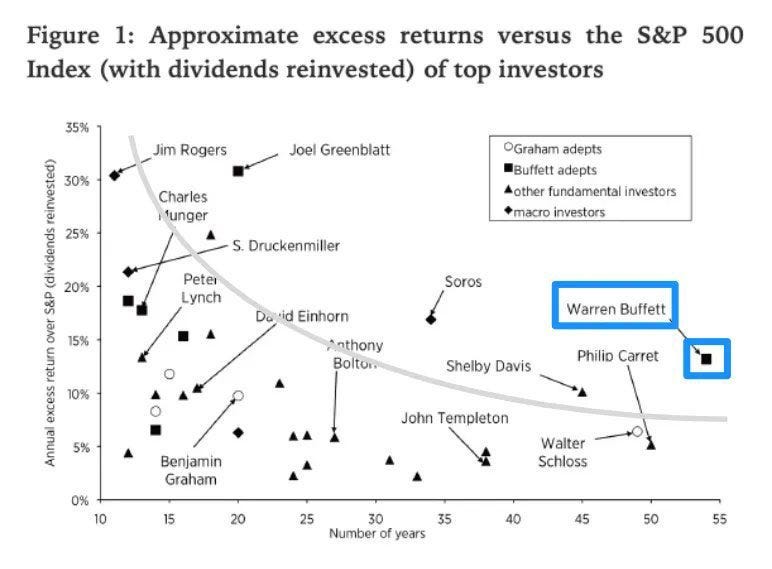
Warren Buffett compounded capital at roughly 20% a year for more than six decades.
Sit with that number for a moment, because almost nothing in the history of markets rivals it. Buffett is an absolute outlier in the chart below.
Part of the explanation is temperament, part is structure, part is the simple arithmetic of a very long runway.
Buffett’s edge was real!
But a meaningful slice of it, especially in the early partnership years, came from something we’d now call an analytical edge. He read the Moody’s manuals nobody else bothered to open. He found the net-nets, the obscure insurance floats, the mispriced stubs that were sitting in plain sight because the work of finding them was tedious, and the audience for that work was small.
"[Warren] expends a lot of energy checking out details and ferreting out nuggets of information, way beyond the balance sheet. He would go back and look at the company's history in depth for decades. He used to pay people to attend shareholder meetings and ask questions for him. He checked out the personal lives of people who ran companies he invested in. He wanted to know about their financial status, their personal habits, what motivated them. He behaves like an investigative journalist. All this stuff about flipping through Moody's Manual's picking stocks, it was a screen for him, but he didn't stop there." Alice Schroeder
That world is gone.
You know this already. Investing has been democratized. Every 10-K is a click away. Every transcript is transcribed, indexed, and searchable within minutes of the call ending. Calls are available in podcast-like apps. Screeners that would have been science fiction in 1965 are free inside your brokerage account. The manuals Buffett had to physically hunt down now arrive pre-digested. Investors share their processes freely online.
And so the intuition almost everyone holds, seasoned investors included, is that the analytical edge has been arbitraged down to something close to zero. The skill ceiling rose so high, and access became so universal, that being smart and diligent stopped being enough. Everyone is smart now. Everyone is diligent.
Then AI arrived, and the intuition hardened into something like certainty.
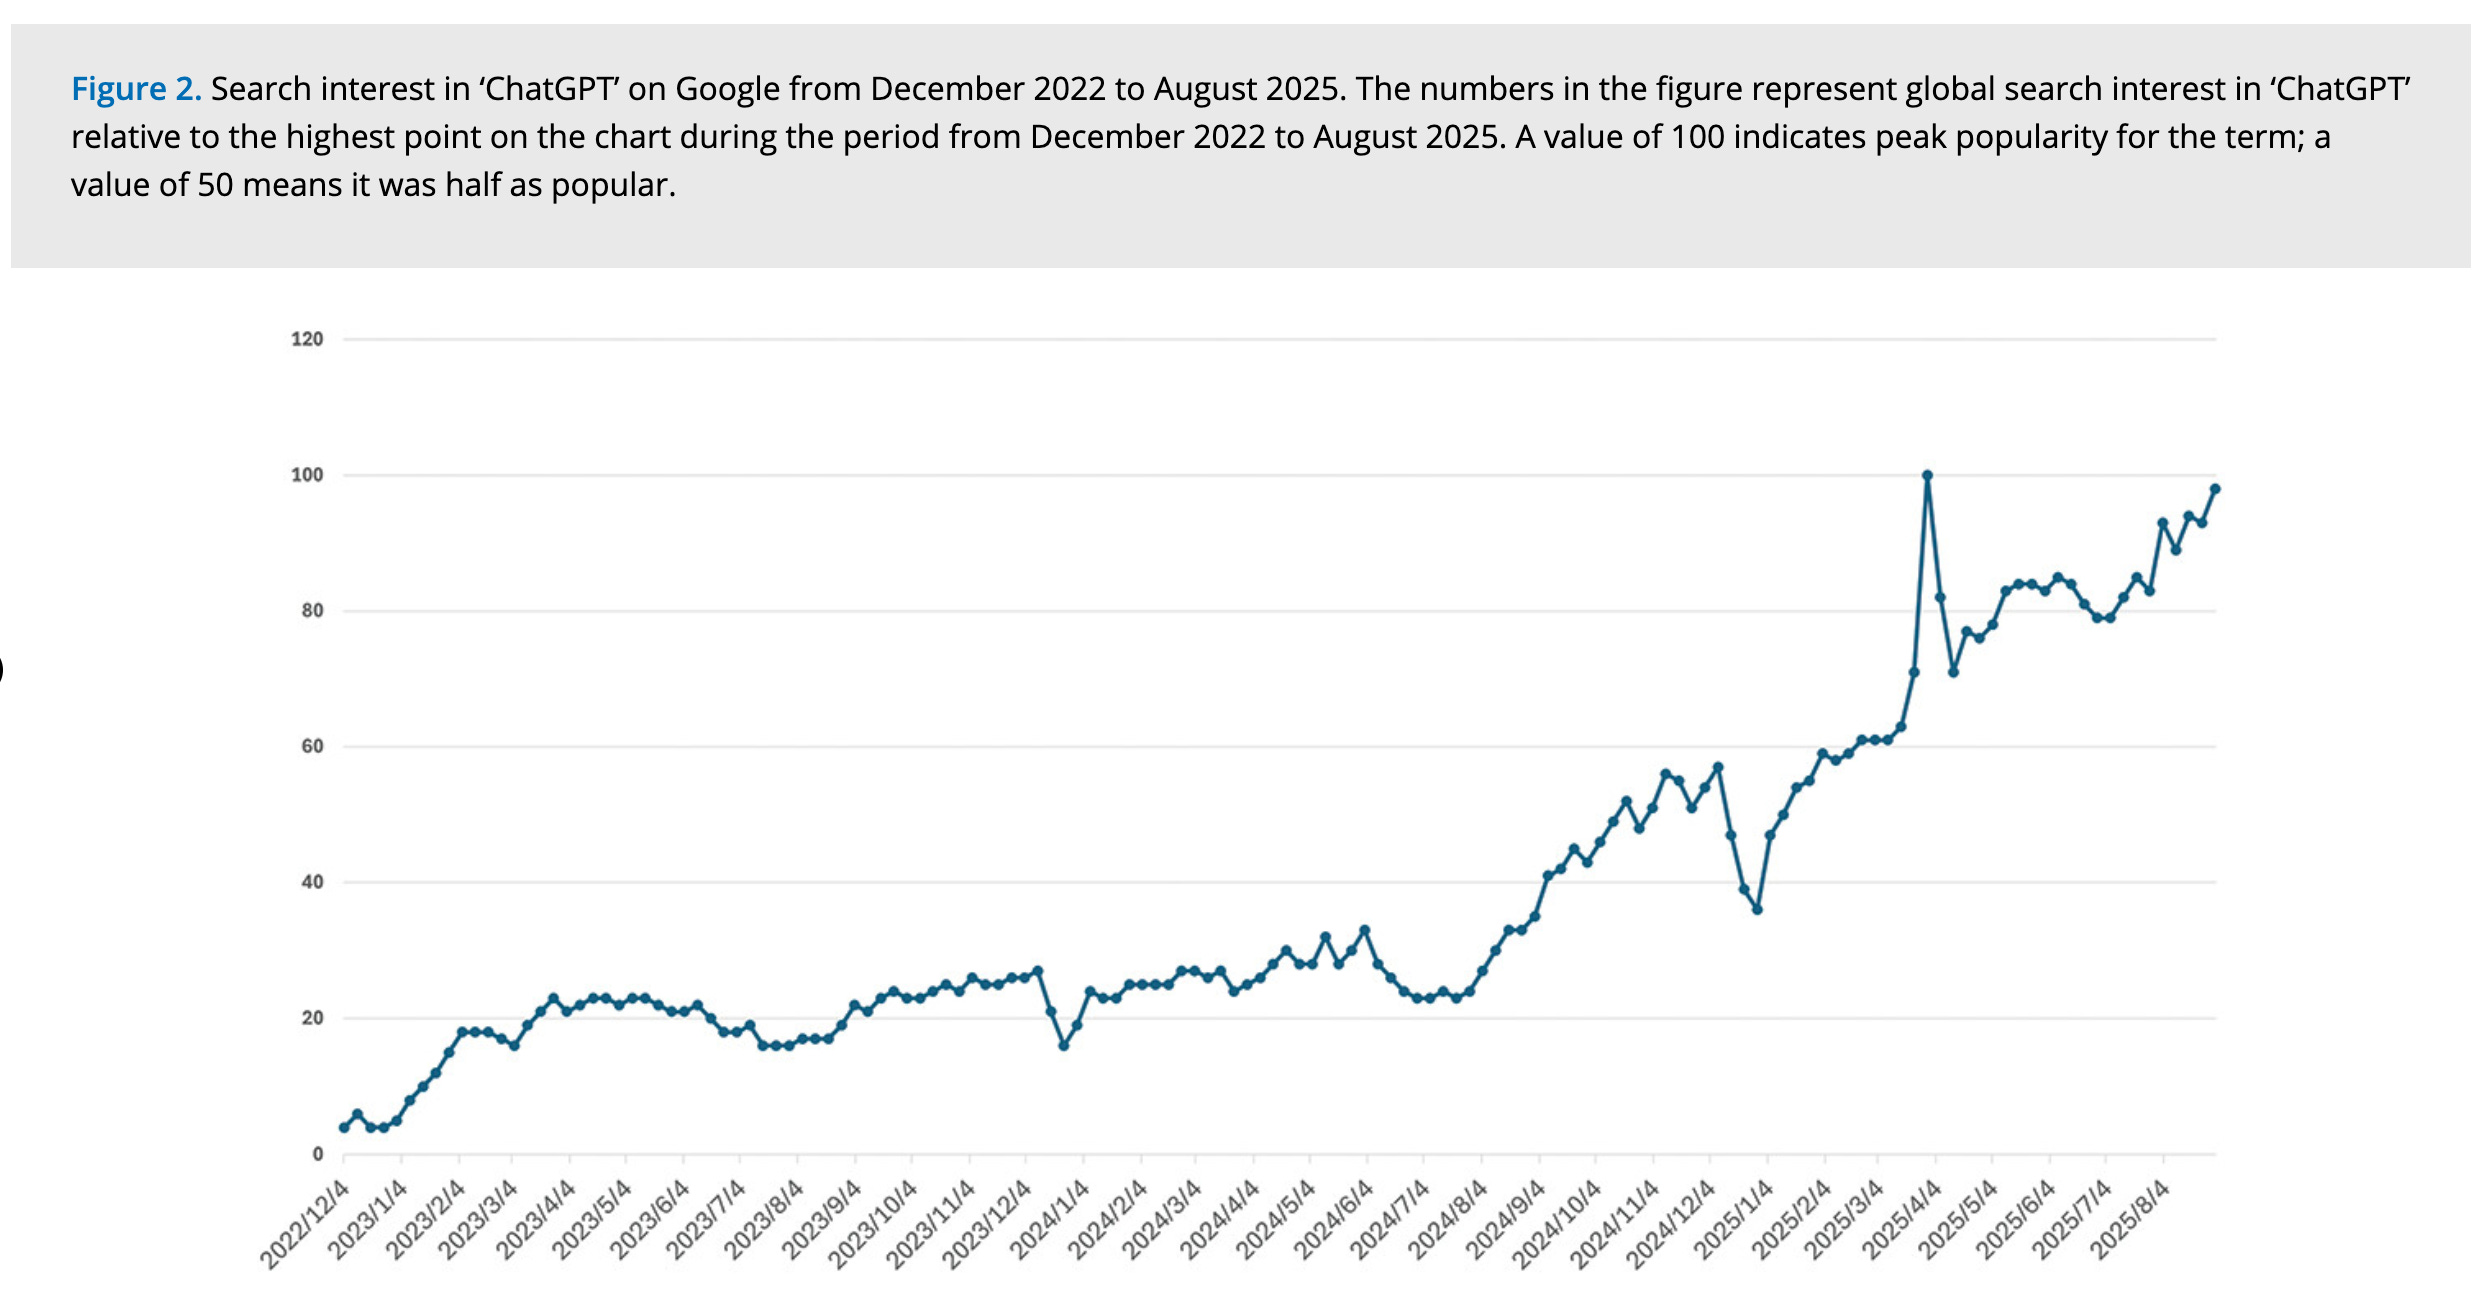
If the internet flattened the information advantage, generative models look poised to flatten the analytical one. A tool that can read a 300-page filing in seconds, build a discounted cash flow model on request, and summarize the bear case before you’ve finished your coffee would seem to be the final erasure of any thinking advantage a human might once have held. The machine does in ten seconds what took a diligent analyst a week.
Where’s your edge now?
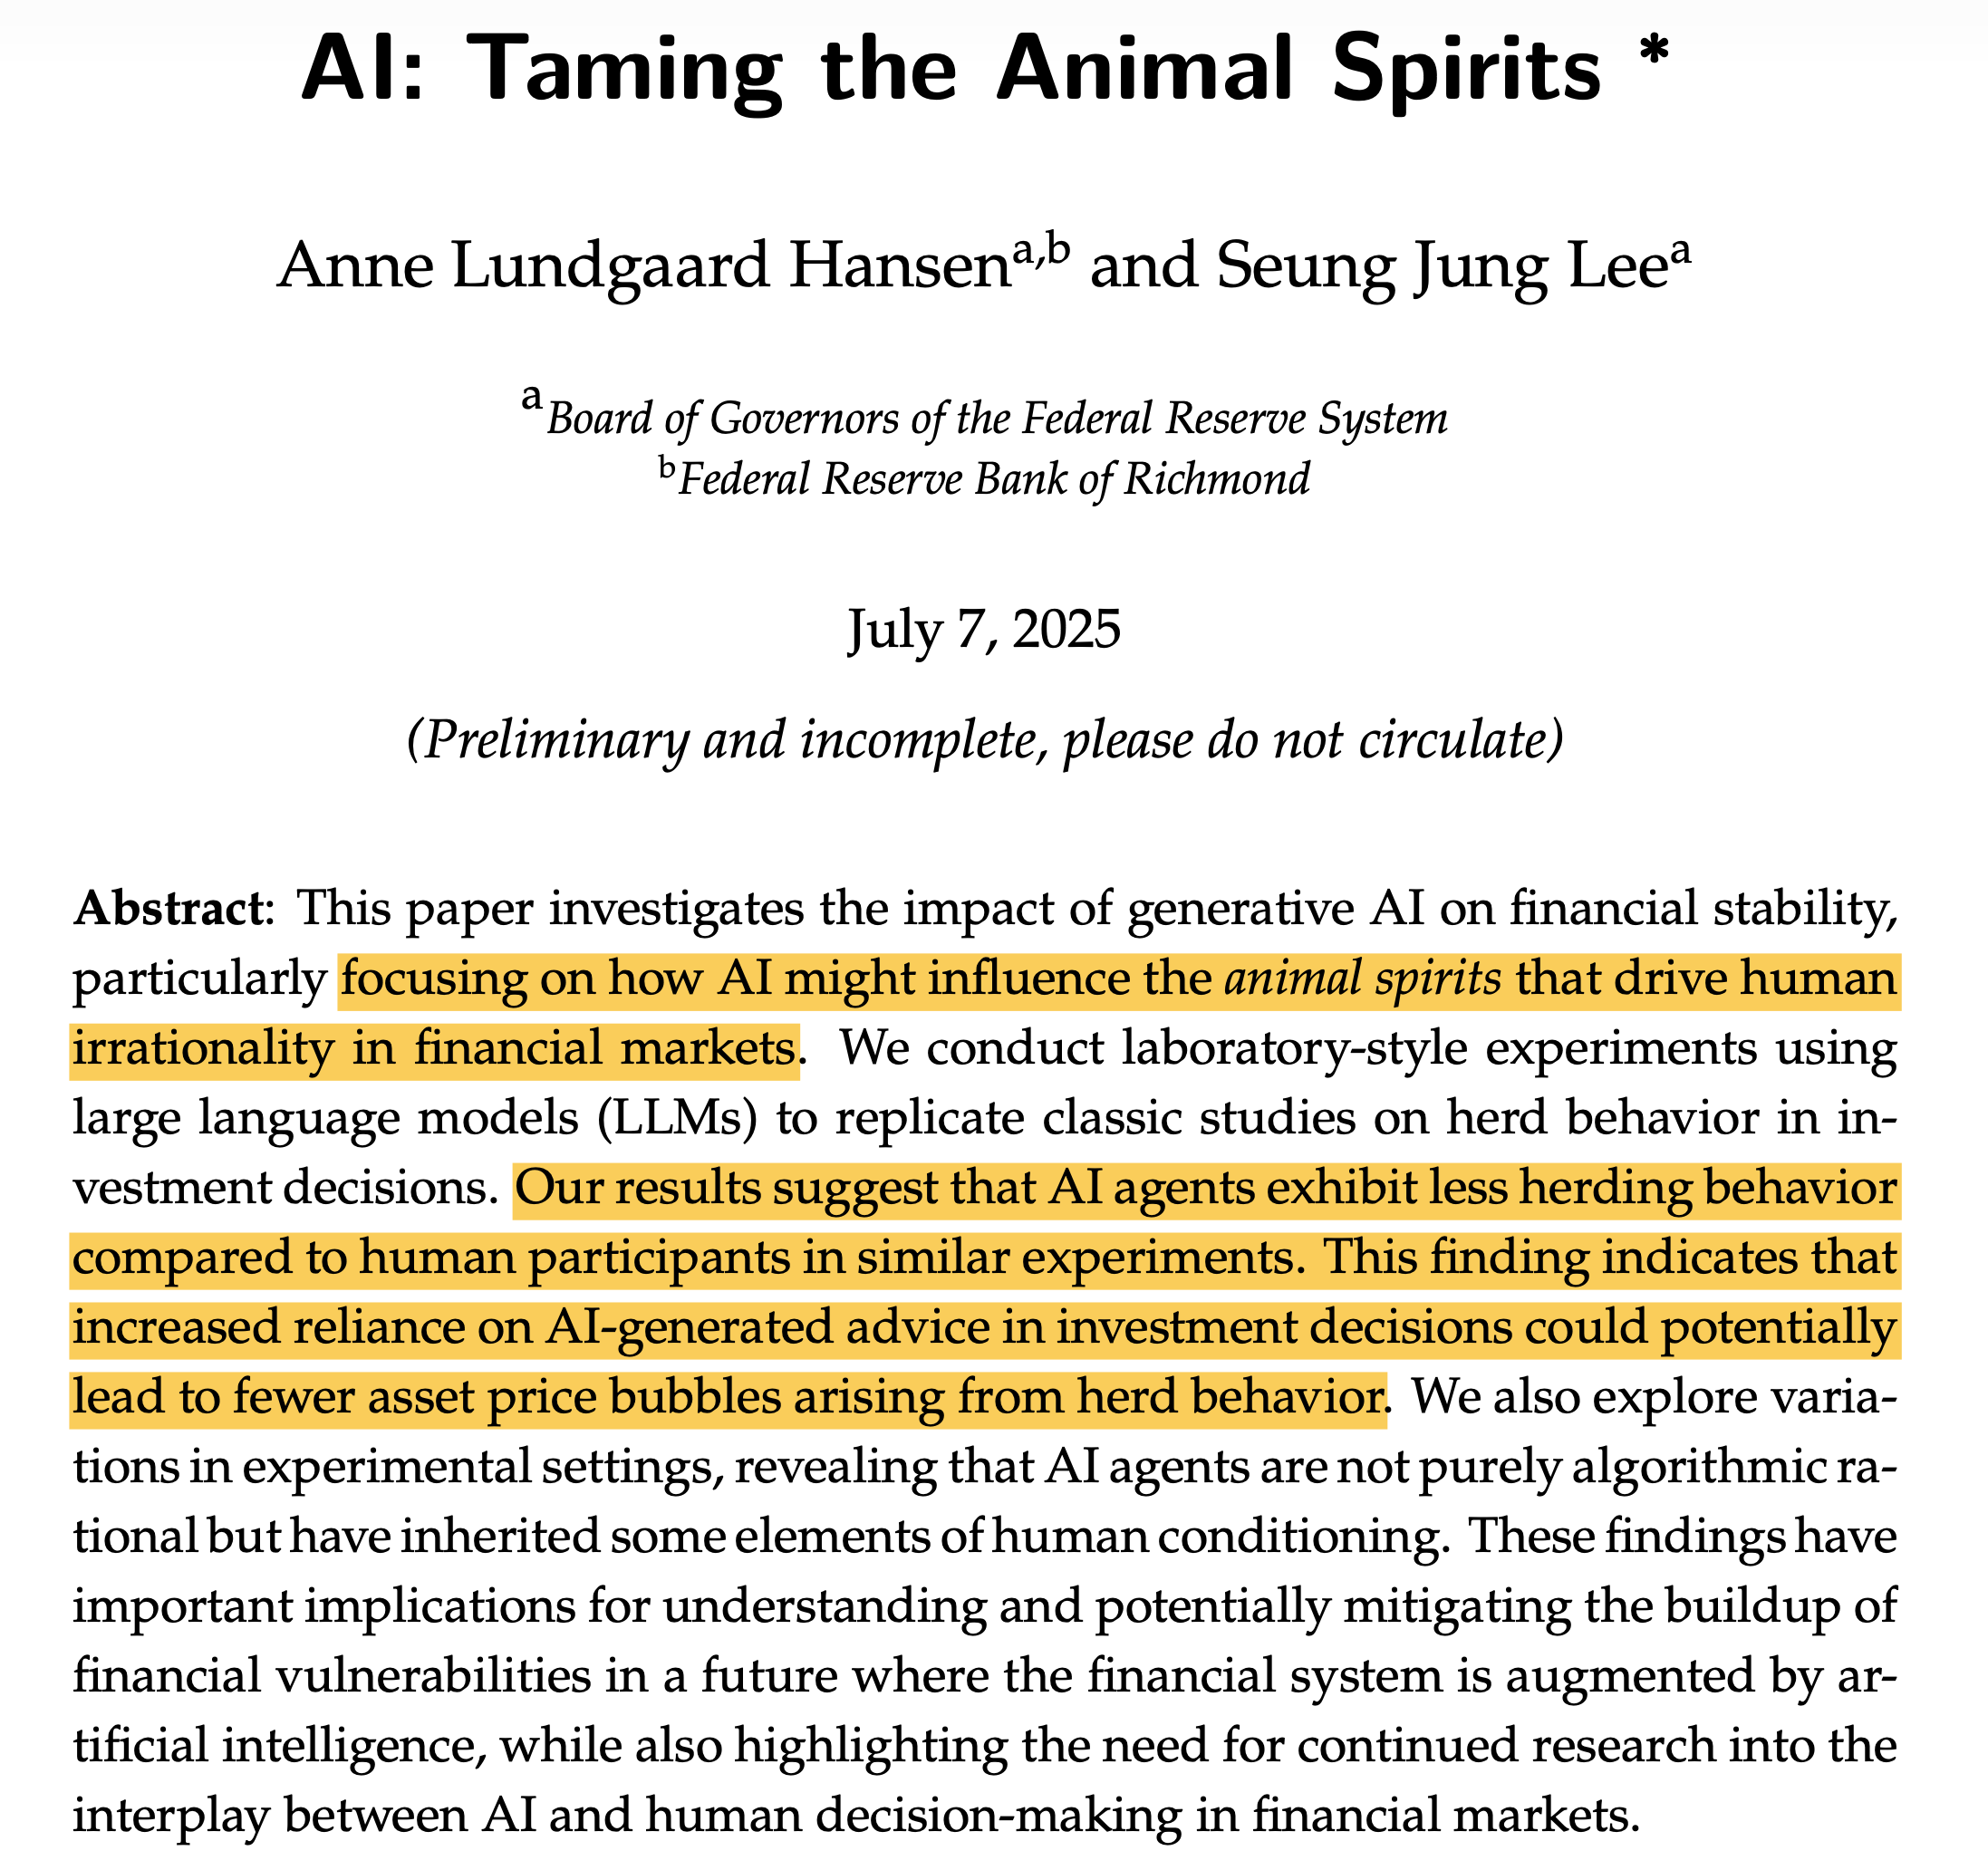
Anne Lundgaard Hansen and Seung Jung Leea thus propose that widespread AI adoption may lead to more efficient markets as bubbles driven by human behavior become less likely.
I want to propose the opposite.
Not as a settled conclusion, because I haven’t arrived at one, but as a hypothesis I think is badly underdiscussed.
The widespread, homogenizing adoption of AI in analysis may not bury the analytical edge. It may be digging it back up. It may not lower volatility, but increase it. It may not lead to less herding, but more crowded trades.
“… when teams simultaneously consult homogeneous AI systems, they unknowingly undergo a process we term Invisible Groupthink. Invisible Groupthink is an AI-mediated conformity that operates without the social pressure or directive leadership that classical groupthink requires, and which is therefore structurally invisible to the organizational safeguards designed to prevent it.“ - Invisible Groupthink: AI Homogenization, Epistemic Diversity, and Organizational Decision Resilience
A quick word on what an edge actually is …
I’ve written at length in a recent post about the distinction between skill and edge, so I won’t rebuild that whole argument here. You can read that piece here:

The short version, for anyone who hasn’t read it: you possess skills, but you do not possess an edge. An edge is external. It’s a situational setup, a behavioral inefficiency, or a structural quirk in the market landscape that appears for you to exploit. It’s an event, not a trait. And the uncomfortable corollary is that you cannot out-skill a bad environment. All the analytical horsepower in the world does nothing if there’s no inefficiency for it to act on.
That framing is highly relevant here, because I believe whether AI makes you more skilled isn’t even a question. Obviously, it does. It makes everyone better.
The question is whether AI creates or destroys the external conditions under which skill converts into excess return.
It helps to be precise about the kinds of edges available. Bill Miller framed it cleanly, and Nick Sleep later paraphrased him well: there are broadly three competitive advantages in investing.
Informational, where you know a meaningful fact nobody else does.
Analytical, where you take the same public information everyone has and cut it up to reach a superior conclusion.
And psychological, or behavioral, where you are able to think and act rationally when others cannot.
Sleep added the observation that sustainable advantages tend to come from the analytical and psychological buckets, because pure informational edges are fragile and, in regulated markets, often illegal. There’s a fourth edge worth naming, the technical or structural one (I’ll again point you to the write-up linked above).
The informational edge, for the ordinary investor, is mostly dead. Regulation and the internet saw to that. Which leaves the analytical and the behavioral as the only edges a fundamental investor can realistically build a career on.
And the analytical one is precisely the edge everyone now assumes AI has finished off.
The edge that eroded before anyone typed a prompt
To understand what AI might do, it’s worth being honest about what already happened without it. The analytical edge didn’t wait for large language models to start decaying. It had been thinning for decades.
Think about the sequence. Decimalization narrowed spreads. Regulation FD, back in 2000, killed the selective-disclosure game where a favored analyst got the nod on the quarter before everyone else. EDGAR put every filing online for free. Then came the screeners, the aggregators, the transcript services, the research terminals, and eventually a generation of investors raised on all of it who think of a fully-built reverse DCF as table stakes.
The barrier to competent analysis fell and fell.
Here’s the thing that gets missed, though. When a skill becomes universal, it stops being an edge, but it doesn’t stop being necessary. You still have to do the work. You just no longer get paid for doing it, because so does everyone else.
“Financial firms are contending with the most significant overhaul of technology capabilities in a generation. AI-driven digital transformation is reshaping job roles and investment processes, prompting professionals to reconsider the boundaries between human and machine cognition, while firms work to upgrade their technology stacks and human capital to remain competitive. Amid this shift, firms and professionals must reevaluate the skills needed for success.“ - CFA Institute in “AI in Finance: Changing Workflows, Growing Demand for Human Judgment“
So by the time AI showed up, the patient was already pale. Most thoughtful investors had made a quiet peace with the idea that their durable edge, if they had one at all, was behavioral. Time arbitrage for instance. The willingness to be patient when the institutional world structurally cannot be, to hold through drawdowns that force a fund with quarterly redemptions to sell. To step in the ring when everyone is panicking.
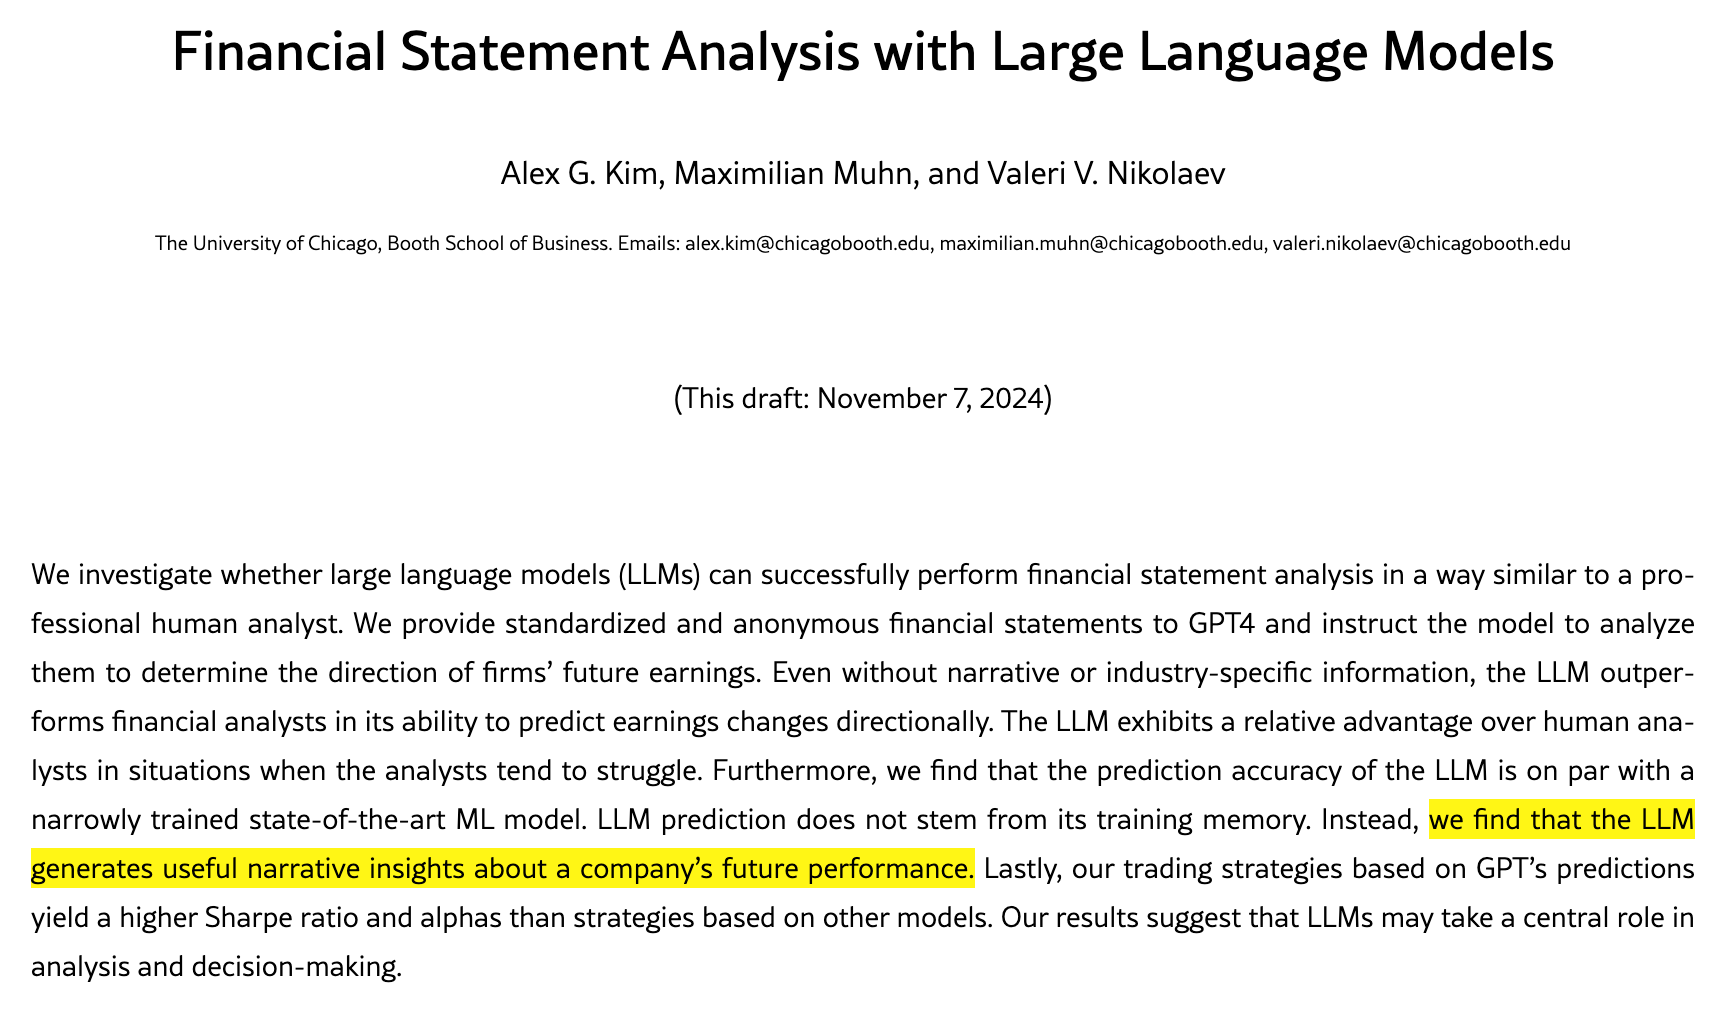
If universal access to information compressed the informational edge, and universal access to analytical tooling compressed the analytical edge, then generative AI looks like the same movie with the resolution turned up. The tool doesn’t just hand you the filing. It reads the filing, cross-references it against eight years of prior filings, flags the change in revenue-recognition language, drafts the model, writes the bear thesis, and stress-tests your bull one.
What took a skilled analyst a focused week now takes an afternoon, and the analyst on the other side of your trade has the same afternoon.
The empirical trend supports the worry. There’s a growing body of research, and a growing chorus on Wall Street, warning that as more investors lean on similar models they converge on the same conclusions. From hedge funds to wealth managers, the industry has embraced AI in search of an edge, and researchers are now asking what happens when everyone turns to similar models to find one: buying the same stocks, reacting to the same headlines, and making the same mistakes. Several recent studies suggest widespread adoption could shorten the lifespan of profitable trading signals as investors converge on the same opportunities. If a signal that once took years to arbitrage away now gets crowded out in months, the shelf life of any analytical insight collapses. You did brilliant work, the model agreed with your brilliant work, and so did every other model, and the opportunity was gone before you could size into it.
That’s the steelman. Faster synthesis, universal tooling, accelerating alpha decay, everyone converging on the same answer at the same time. If you stop the story there, the analytical edge isn’t just dead. AI held the pillow over its face.
But notice the word doing all the work in that paragraph. Converge.
The rest of this post is FREE to read. I only ask that you subscribe, which costs nothing and can be undone with a single click whenever you like.
The wall also helps keep my writing from being freely scraped by AI crawlers, so I hope you understand the small extra step.
In return, you get every deep dive, earnings review, and process piece I publish, straight to your inbox.