

“The longer I invest, the more I come to respect the efficiency of markets.”
That line, from a blog post by Matt Newell, hit home for me. It’s such a simple statement, but it captures something profound that many investors only come to understand with time and experience.
Early on in my investing journey, I used to think the market was filled with idiots. Now I think it’s filled with people who are mostly... not. And that shift in perspective changes everything.
Here’s the fuller passage that grabbed me [emphasis added]:
“The longer I invest, the more I come to respect the efficiency of the stock market. I think a good chunk of the value investing community is stuck in the past — a past where all an investor needs is the right mindset (buying stocks as if you were buying the whole company; be greedy when others are fearful) and the right approach (good business, good management, reasonable valuation). The past in which Buffett, Lynch and others delivered 25% annual returns for decades on end. I think that time is over, and I doubt it's coming back. Most market participants were fucking boneheads back then. Market participants today are a hell of a lot smarter, and a lot more of them have more of a long-term, fundamental approach. Perhaps not a majority, but it needn't be a majority — only enough to push up the price of the really good stuff.”
That hits hard because it says what a lot of investors may be quietly thinking…
The game has changed. It’s not 1965 anymore. It’s not even 2012. The average market participant today is sharper, better-informed, and more process-driven. And with that, alpha has become harder to generate.
Newell’s “solution” is to lean into microcaps – to go where the market is less efficient, where there’s less coverage, less liquidity, and a better chance to find real informational edges. He writes about companies with no analyst coverage, no institutional ownership, and sometimes virtually no trading volume. And I’m not disagreeing with him here. It’s a compelling approach in a more efficient market environment IF you’re wired for it.
But I’m not.
I Choose a Different Edge
Personally, I attempt to lean into something else: the behavioral edge. Not because I dismiss the informational edge – I respect it deeply – but because I find the risk/reward profile in the microcap space a little too binary for my taste. The trajectory of outcomes tends to be (very) wide, and the average business quality tends to be lower compared to larger-cap companies.
Now, I firmly believe even the world’s LARGEST, most closely followed companies get mispriced. And not just occasionally – it happens all the time!
I’ve written about this before, but I keep returning to a passage Rob Vinall shared in one of his investor letters (see below). It’s one of the most articulate rebuttals to the idea that only small caps can be massively mispriced.
He argues that large- and even mega-cap stocks, while surrounded by round-the-clock coverage and swarms of analysts, can become trapped in consensus narratives that harden into assumptions – price drives narrative. In his own experience, investing in Google during its mobile transition or Facebook amid rising regulatory fear wasn’t about discovering unknown facts – it was about seeing the same facts differently.
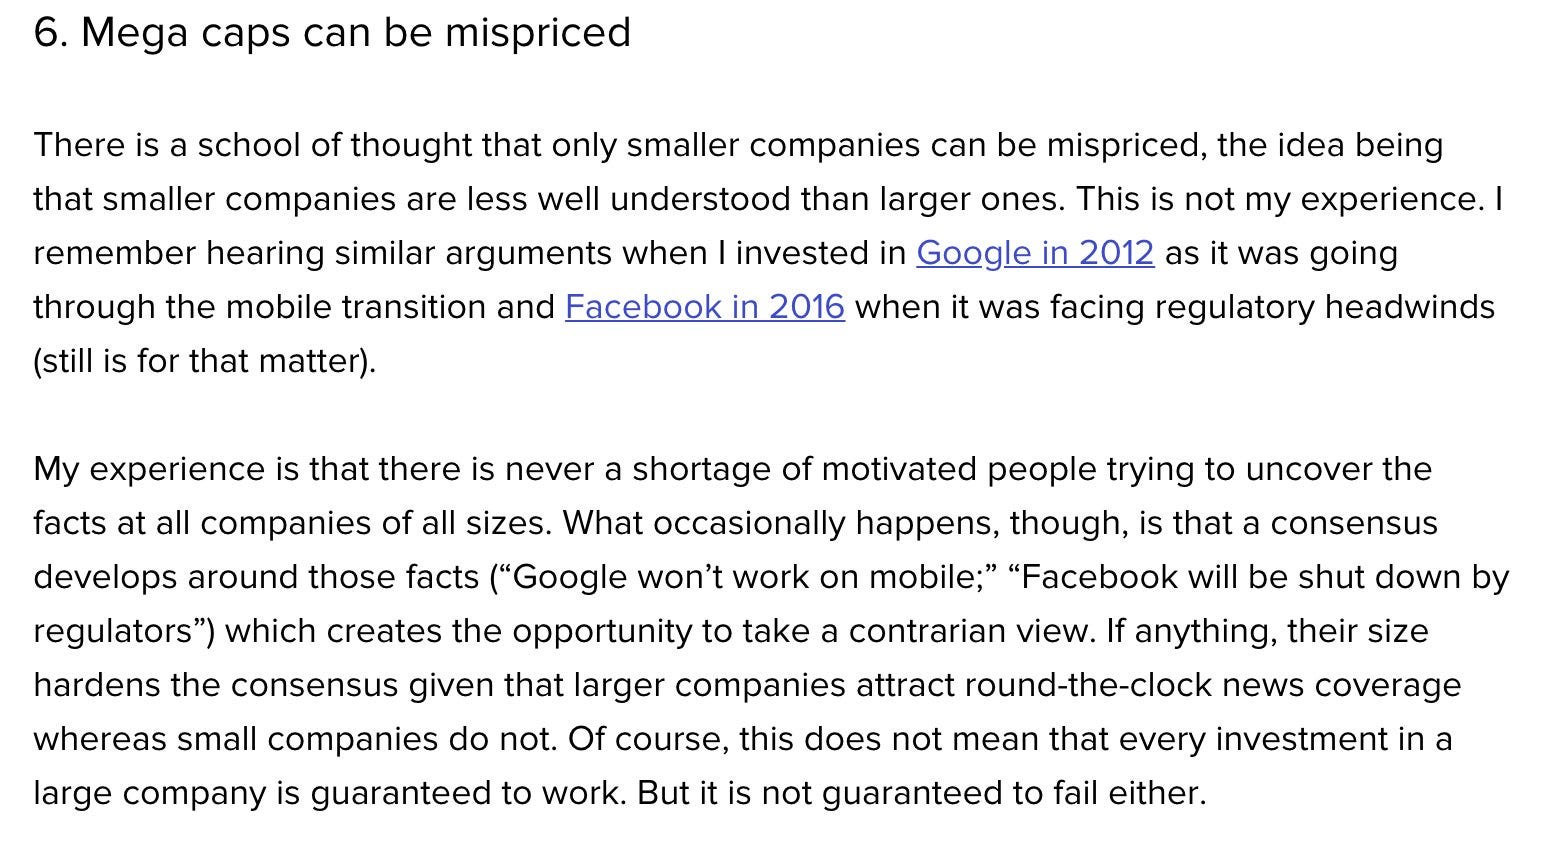
Meta’s more recent stock performance may be the best case study to prove his point. The stock is up 7x from the 2022 lows, up 7x over just around 2.5 years, compounding at a triple-digit rate over this period… that reflects some major market inefficiencies (at least when it comes to Meta back in 2022).
When enough people agree on a flawed interpretation, mispricings emerge even in the most visible corners of the market.
That insight has stuck with me. It's not a matter of finding obscure facts – it's a matter of identifying when the dominant interpretation has calcified and detached from reality. That’s where the opportunity lies.
And that brings me to one of the most powerful mental models in investing: the wisdom of crowds – which sometimes break ...
Before we dive back in, a quick note…
Want to compound your knowledge – and your wealth? Compound with René is for investors who think in decades, not headlines. If you’ve found value here, subscribing is the best way to stay in the loop, sharpen your thinking, avoid costly mistakes, and build long-term success – and to show that this kind of long-term, no-hype investing content is valuable.
Thank you for your support!
How Smart Markets Work
Michael Mauboussin has long framed market efficiency through the lens of crowd intelligence. Markets, he argues, function efficiently when three key ingredients are present:
diverse perspectives,
a mechanism for aggregating information (like a stock exchange),
and incentives that reward accuracy and penalize error.
When all three conditions hold, even flawed individuals acting independently can collectively produce remarkably accurate pricing.
The jellybean jar example comes to mind – no single guess is reliable, but the average of many guesses often comes very close to the truth.

But here’s the problem: those conditions don’t always hold.
And the one that tends to fail first is diversity. As soon as people start thinking alike – not just agreeing on outcomes, but using the same mental models, the same inputs, the same narratives – the crowd becomes less of an independent ensemble and more of an echo chamber.
Investors begin standing on the same side of the boat. And that’s when things start to break.
The Fragility of Diversity
What makes this even trickier is that the breakdown is rarely obvious in the moment. Diversity can break down all at once or deteriorate slowly, almost imperceptibly.
The rest of this post is FREE to read. I only ask that you subscribe, which costs nothing and can be undone with a single click whenever you like.
The wall also helps keep my writing from being freely scraped by AI crawlers, so I hope you understand the small extra step.
In return, you get every deep dive, earnings review, and process piece I publish, straight to your inbox.