

Capital allocation is one of those topics that is easy to discuss on a basic level, but which many investors find difficult to truly grasp, as it requires a great deal of nuance and critical thinking to assess how value-accretive capital allocation decisions really are/were.
Everyone agrees it matters – a lot! –, but few investors consistently think in terms of opportunity cost – the silent force that shapes the value accretiveness of every decision a management team makes once new cash hits their balance sheet.
Should they reinvest in the business? Pay down debt? Buy back shares? Raise dividends? On the surface, the options look mechanical, even formulaic. In reality, they require judgment, foresight, sometimes creativity, and sometimes a willingness to do nothing – yes, that’s a capital allocation decision too.
The market tends to reward simplicity. If a company announces a buyback, investors often celebrate. The optics are clean: fewer shares, higher EPS, a tangible signal that management believes the stock is cheap. But as seductive as that narrative is, it can be misleading. A buyback only creates value when the stock trades below intrinsic value. Otherwise, it’s an implicit transfer of wealth from continuing shareholders to those who sell. It’s capital destruction disguised as shareholder friendliness.
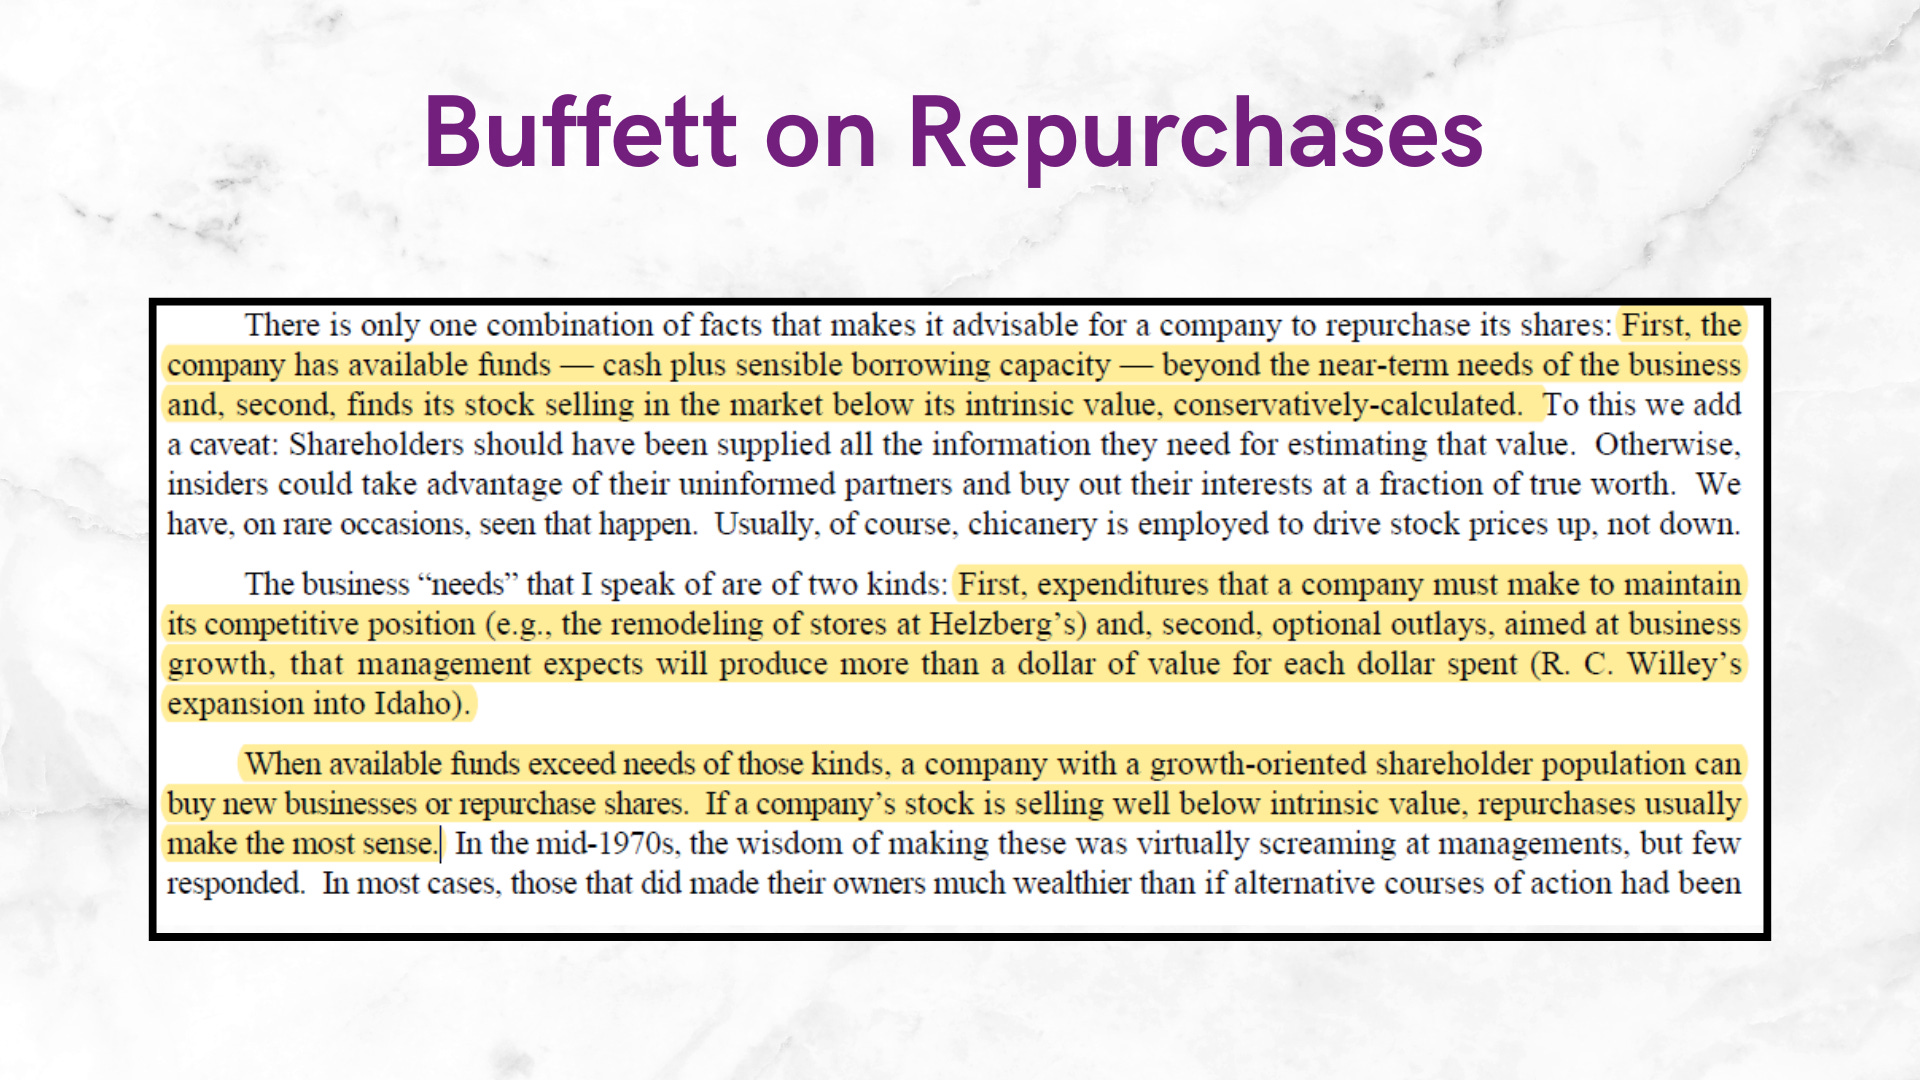
Reinvestments back into the business, on the other hand, are messier. The return earned on this allocation of capital doesn’t show up as neatly in quarterly slides. The payback period can be long, the returns uncertain, the outcomes dependent on execution quality, industry structure, and sometimes macro developments management can hardly control. Yet, often, that’s where businesses strengthen their moats, extend their competitive advantages, and plant the seeds for tomorrow’s cash flows.
As investors, we often fall into the trap of treating capital allocation decisions as binary – buybacks versus growth investments, dividends versus M&A. But what really matters is context. Opportunity cost isn’t a static number on a spreadsheet; it’s a concept, often a moving target, shaped by market conditions, valuation, competitive position, and the set of reinvestment options available at any given time.
When I evaluate management teams, I don’t start by asking whether they’re buying back stock. I ask whether they’re thinking like investors – comparing alternatives, ranking opportunities, and deploying capital where the incremental return per dollar is highest after adjusting for risk and durability. That’s a far higher bar than simply repurchasing shares to signal confidence.
“Do they have an intelligent read on intrinsic value and will they consistently buy back shares at attractive discounts to that intrinsic value? That’s another key way to determine whether they are thinking like owners.” Peter Keefe
Example below
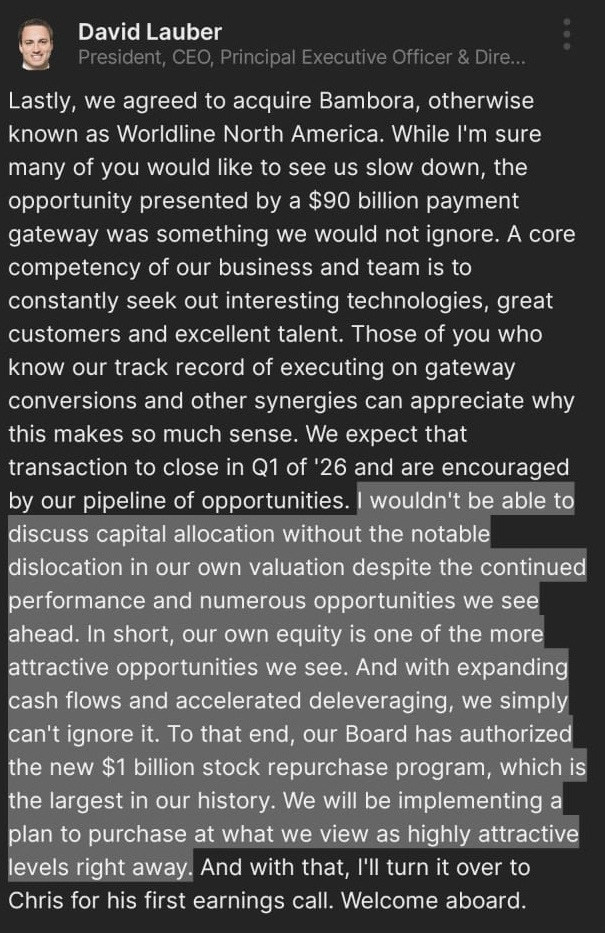
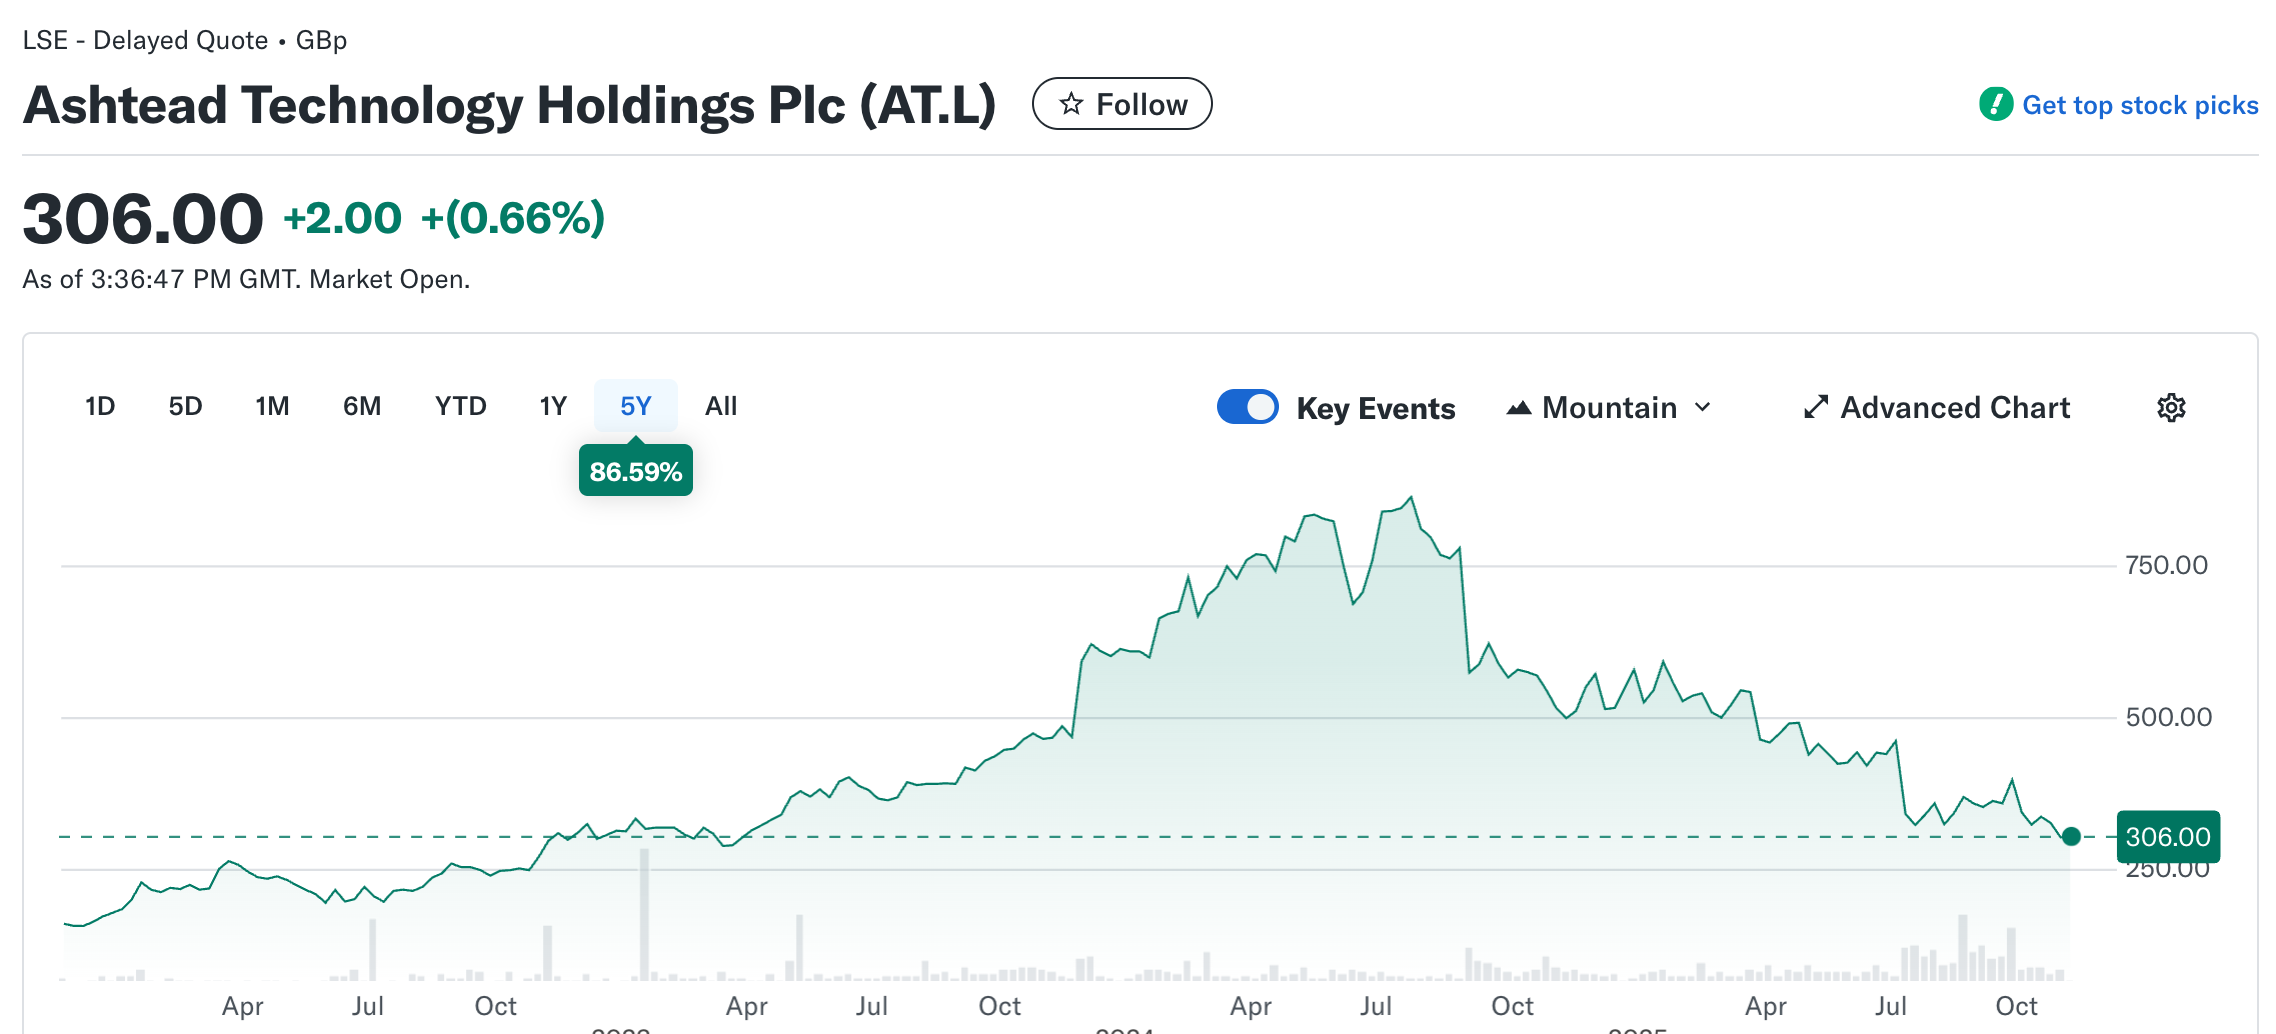
Ashtead Technology is a good example of this nuance. The company’s share price has been under pressure, and it’s tempting to wish for aggressive buybacks.
But when I look at the reinvestment opportunities in front of them – the ability to strengthen their one-stop-shop moat, expand their equipment, deepen customer relationships, I find myself rooting for internal reinvestment instead; despite the poor recent share performance.
Disclaimer: The analysis presented in this blog may be flawed and/or critical information may have been overlooked. The content provided should be considered an educational resource and should not be construed as individualized investment advice, nor as a recommendation to buy or sell specific securities. I may own some of the securities discussed. The stocks, funds, and assets discussed are examples only and may not be appropriate for your individual circumstances. It is the responsibility of the reader to do their own due diligence before investing in any index fund, ETF, asset, or stock mentioned or before making any sell decisions. Also double-check if the comments made are accurate. You should always consult with a financial advisor before purchasing a specific stock and making decisions regarding your portfolio.
The Opportunity Cost Framework
When I think about capital allocation, I think about trade-offs. Every dollar of free cash flow can only be spent once – and every use of that dollar carries an implicit opportunity cost. It’s the return you forgo from the next-best alternative.
In theory, management should always allocate capital to the option with the highest risk-adjusted return.
In practice, this is where things get tricky.
“In theory, there is no difference between theory and practice; in practice, there is.”
The textbook hierarchy goes something like this: first, reinvest in the core business if incremental returns on incremental invested capital (ROIIC) remain attractive; second, pursue strategic acquisitions at attractive prices that enhance the moat; third, pay down debt if leverage is high (+ the interest reduction is a guaranteed return); fourth, repurchase shares if they trade below intrinsic value; and lastly, distribute dividends when no better options exist.
It’s a tidy list. But reality rarely fits the list.
Before we dive back in, a quick note…
Want to compound your knowledge – and your wealth? Compound with René is for investors who think in decades, not headlines. If you’ve found value here, subscribing is the best way to stay in the loop, sharpen your thinking, avoid costly mistakes, and build long-term success – and to show that this kind of long-term, no-hype investing content is valuable.
Sometimes reinvestment opportunities are limited or cyclical. Sometimes management has asymmetric information about intrinsic value. And sometimes, the best capital allocation decision might simply be to wait.
To make this more tangible, I like to share some simple buyback math – and the illustration below of the fictional company “Metavision Inc.” (credits go to Javier Pérez from Edelweiss Capital).
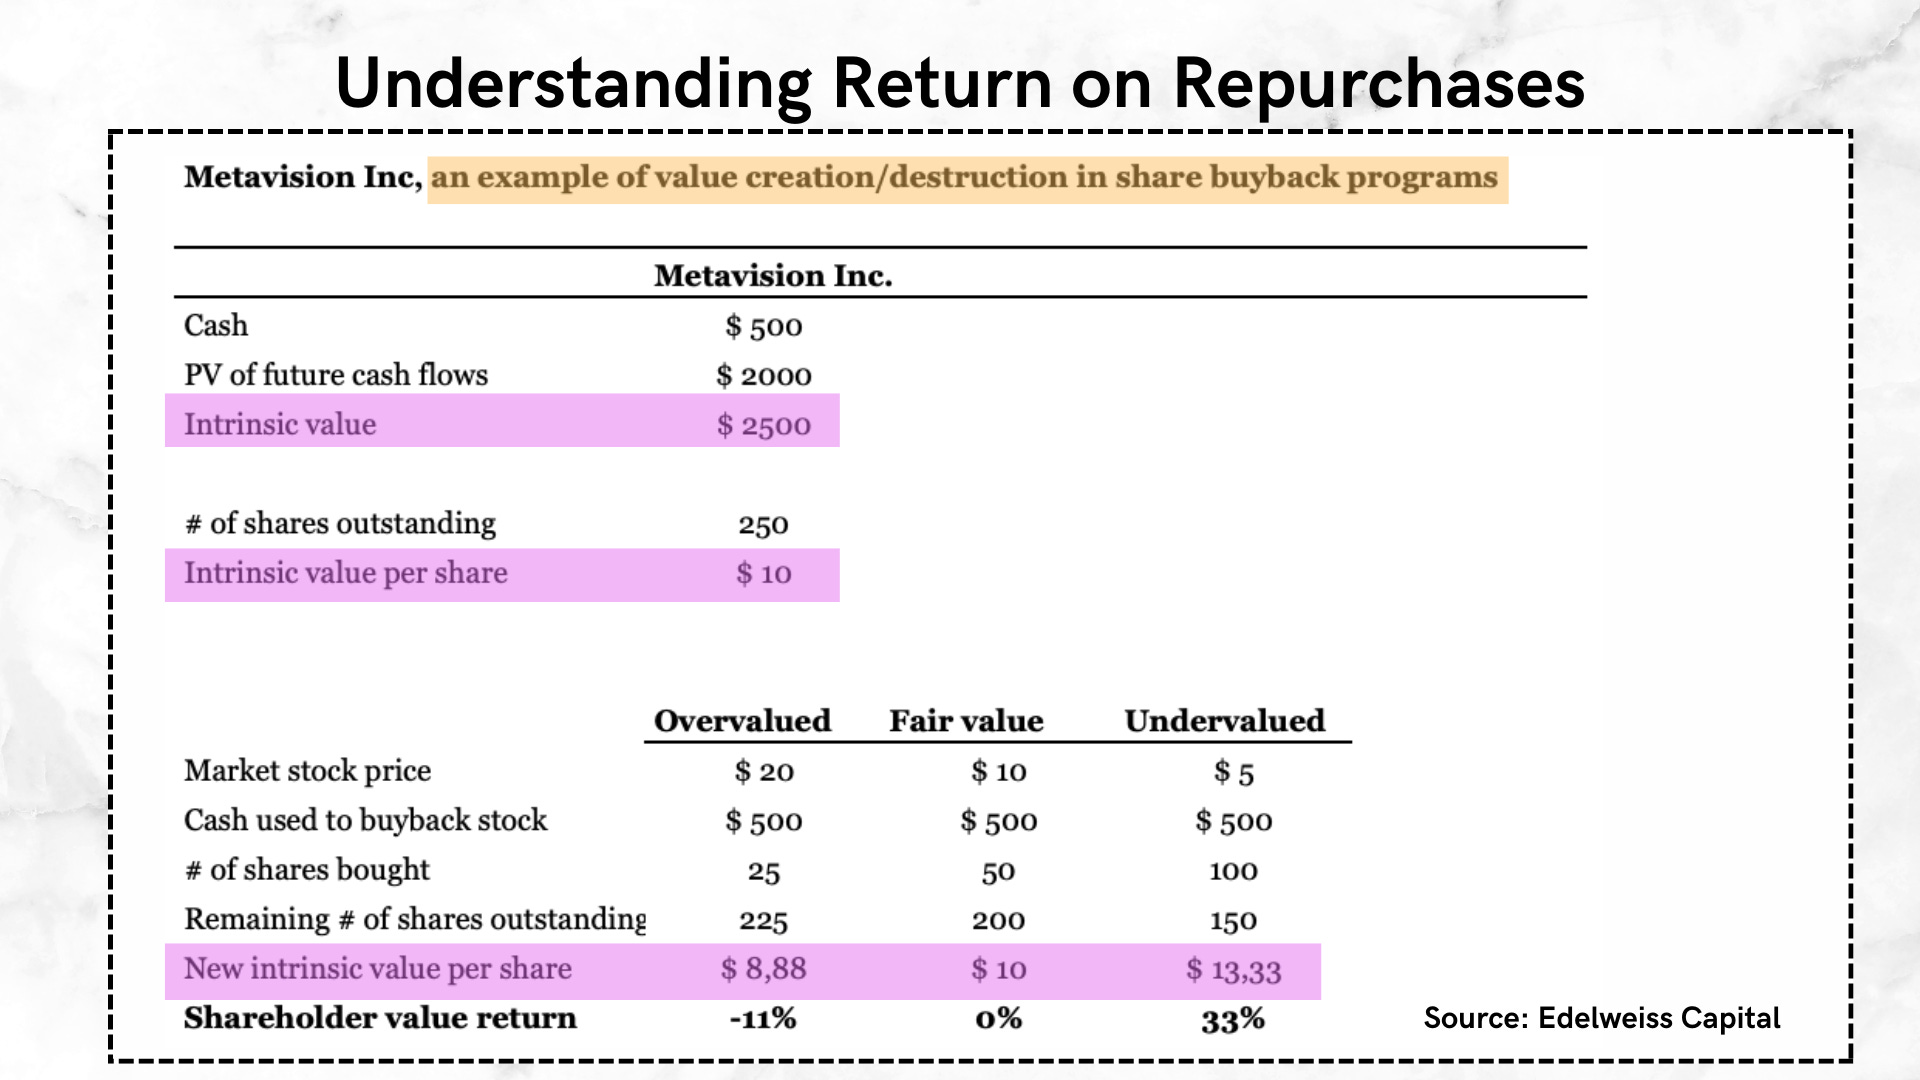
It shows how a $500 buyback can either create, preserve, or destroy value depending on valuation. When shares are overvalued, each dollar used to repurchase stock actually reduces intrinsic value per share. When shares are fairly valued, intrinsic value per share stays roughly the same. And when shares are undervalued, buybacks become a powerful value creation tool.
The rest of this post is FREE to read. I only ask that you subscribe, which costs nothing and can be undone with a single click whenever you like.
The wall also helps keep my writing from being freely scraped by AI crawlers, so I hope you understand the small extra step.
In return, you get every deep dive, earnings review, and process piece I publish, straight to your inbox.