

I find myself returning to a core philosophy of the markets lately, and I decided to write about it, largely because I want to permanently pound this concept into my own brain. Over the past few days, I have been hashing out the nuances of market dynamics with Tiho Brkan, and his perspective on this matter is entirely spot-on. We kept coming back to a foundational distinction that most market participants completely distort or overlook: the difference between internal skill and an external edge.
"First answer the question, 'What's your edge?" - Seth Klarman
The Poker Room Paradox: Why Raw Talent Fails at the Wrong Table
To understand this clearly, I often look back to my late teens and early twenties, a period of my life during which I spent a good amount of hours each week playing poker online.
I believe, in poker, the demarcation between skill and edge is brutally transparent – and easier to grasp than in investing, I believe – because it can be quantified with mathematical precision, and if you play at multiple tables simultaneously, sample sizes are large (in contrast to the handful of bets you place in investing).
You measure your performance in big blinds won per one hundred hands played. If you possess superior technical proficiency, your long-term expected value rises.
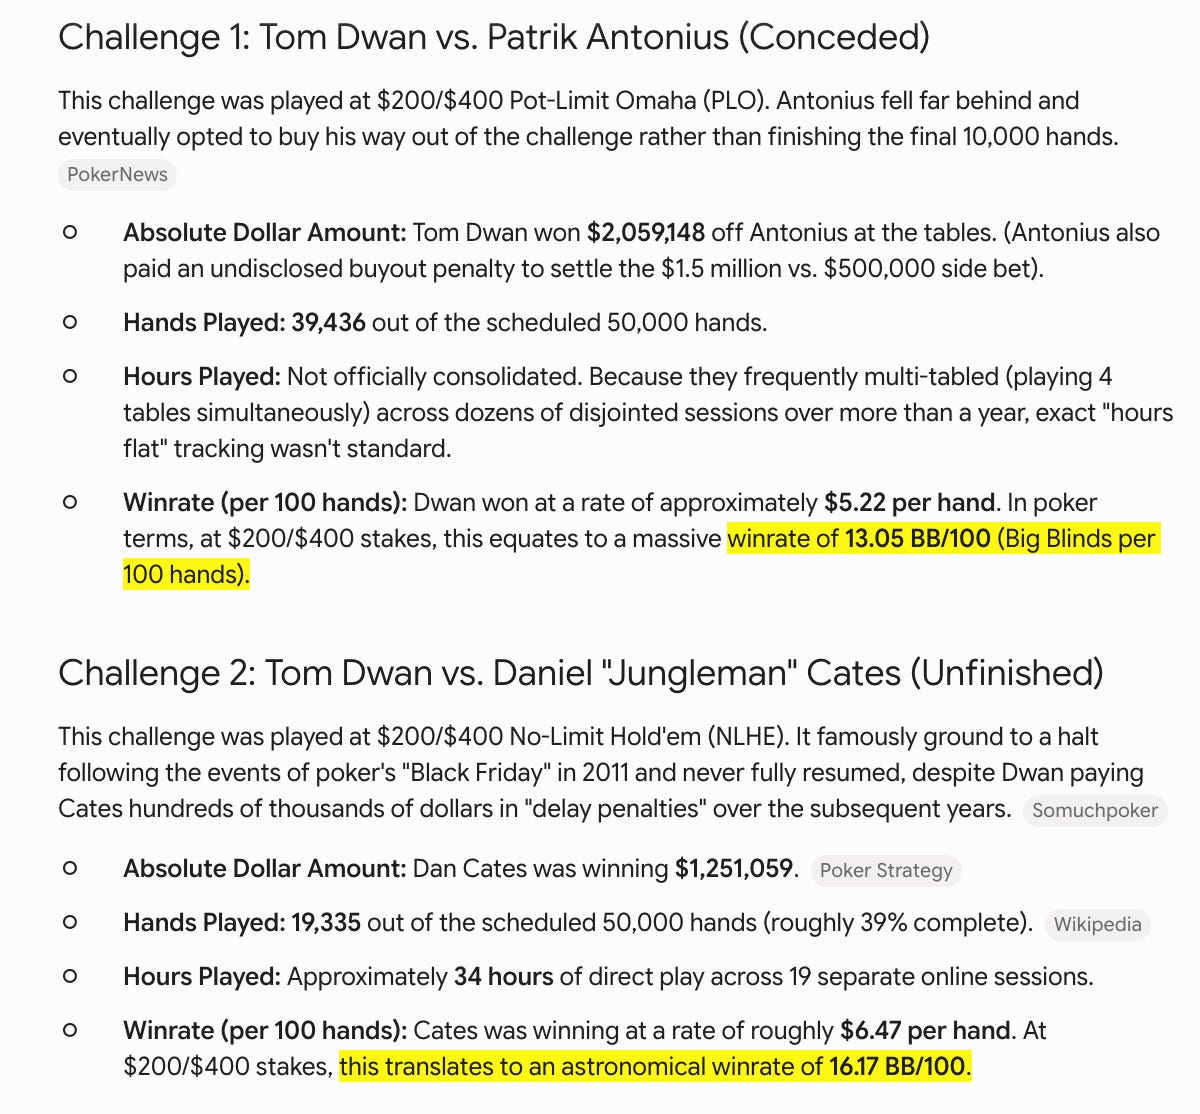
Consider the "durrrr" Challenge, for instance, which was a legendary high-stakes online poker wager issued in 2009 by Tom "durrrr" Dwan, who offered to play anyone in the world (except Phil Ivey) heads-up for 50,000 hands at $200/$400 stakes, backing his confidence with a massive 3-to-1 side bet where he risked $1.5 million against an opponent's $500,000. It became a defining spectacle of poker history that ultimately ended in incomplete drama: Finnish pro Patrik Antonius conceded the first match in 2010 after falling over $2 million behind, while the second match against Daniel "Jungleman" Cates – who was crushing Dwan for $1.25 million – was abruptly halted by the 2011 "Black Friday" shutdown of US online poker and never formally finished.
I’ve attached the final results and the respective win rates (measured in BB/100 hands) below. For context, in modern heads-up poker, a win rate over 5 BB/100 is considered a significant edge. Both of these challenges saw incredibly high win rates, suggesting that while at the beginning the challenge, both players thought they had an edge on the other, in reality, only one of them had (of course, in a heads up setup; it’s more complex at a six-seat table).
In poker, table selection matters.
You could be the tenth-best Texas Hold’em player on the planet, but if you sit at a table with the nine players who are better than you, you are the sucker.
Throw in the casino rake – the structural cut taken by the platform or house – and a hyper-competitive table will easily turn a world-class player into a break-even grinder.
You simply cannot out-skill a terrible environment.
This exact dynamic governs the global stock market. Think of it through the lens of a classic fishing analogy which Charlie Munger frequently referenced: some bodies of water are teeming with fish, meaning you do not even need fantastic talent to walk away with a heavy catch. Other waters are so heavily fished and depleted that no matter how legendary of an angler you are, you are going to struggle to catch anything at all.
When you can locate an attractive setup (which in itself may be a skill) – a market pocket overflowing with fish – you can exploit that external inefficiency comfortably.
Conversely, when competition is fierce and the “paradox of skill” kicks in, the edge vanishes, the game becomes dictated primarily by luck, and even the elite practitioners begin to flounder.
As Michael Mauboussin famously observed, all the investing skill in the world means absolutely nothing if you cannot find an attractive opportunity to exploit or an easy game to play.
“The key is this idea called the paradox of skill. As people become better at an activity, the difference between the best and the average and the best and the worst becomes much narrower. As people become more skillful, luck becomes more important. That’s precisely what happens in the world of investing. […] That said, over longer periods, skill has a much better chance of shining through.”
– Michael Mauboussin
This brings us to a critical, baseline definition. You possess skills; you do not possess an edge. An edge is an entirely external development, a situational setup or a behavioral inefficiency that appears in the market landscape for you to exploit. It is an event.
But it may also disappear! Think of a broader market panic for instance, where the wisdom of the crowd turns into the madness of the crowd.
Hence, it is not necessarily a repeatable part of the investment process. You can spot “edge-favoring” setups and lean into them, but they may be temporary.
Security selection skill, on the other hand, is an internal attribute. It is comprised of technical sub-skills like parsing complex financial statements, understanding corporate accounting, assessing competitive dynamics or management integrity, modeling cash flows, and analyzing chosen competitive strategies or incentives embedded in compensation packages. Mastering these disciplines makes you a highly competent analyst.
But while these “sub-skills” are essential, they represent internal capability rather than a market edge, which only manifests when a structural breakdown creates a deep mispricing.
Unless you are a political insider with an uninterrupted, asymmetrical flow of corporate data – a rare, controversial exception that someone like Nancy Pelosi or the Trump family might enjoy – you cannot personally own an edge. It belongs strictly to the environment.
The BAIT Framework & How it Defines Your Counterparty’s Mistakes
To truly exploit an edge, you must transition from broad philosophy to a rigorous taxonomy. If you want to actively look for setups that may present an edge, you have to isolate exactly how these setups manifest in the wild.
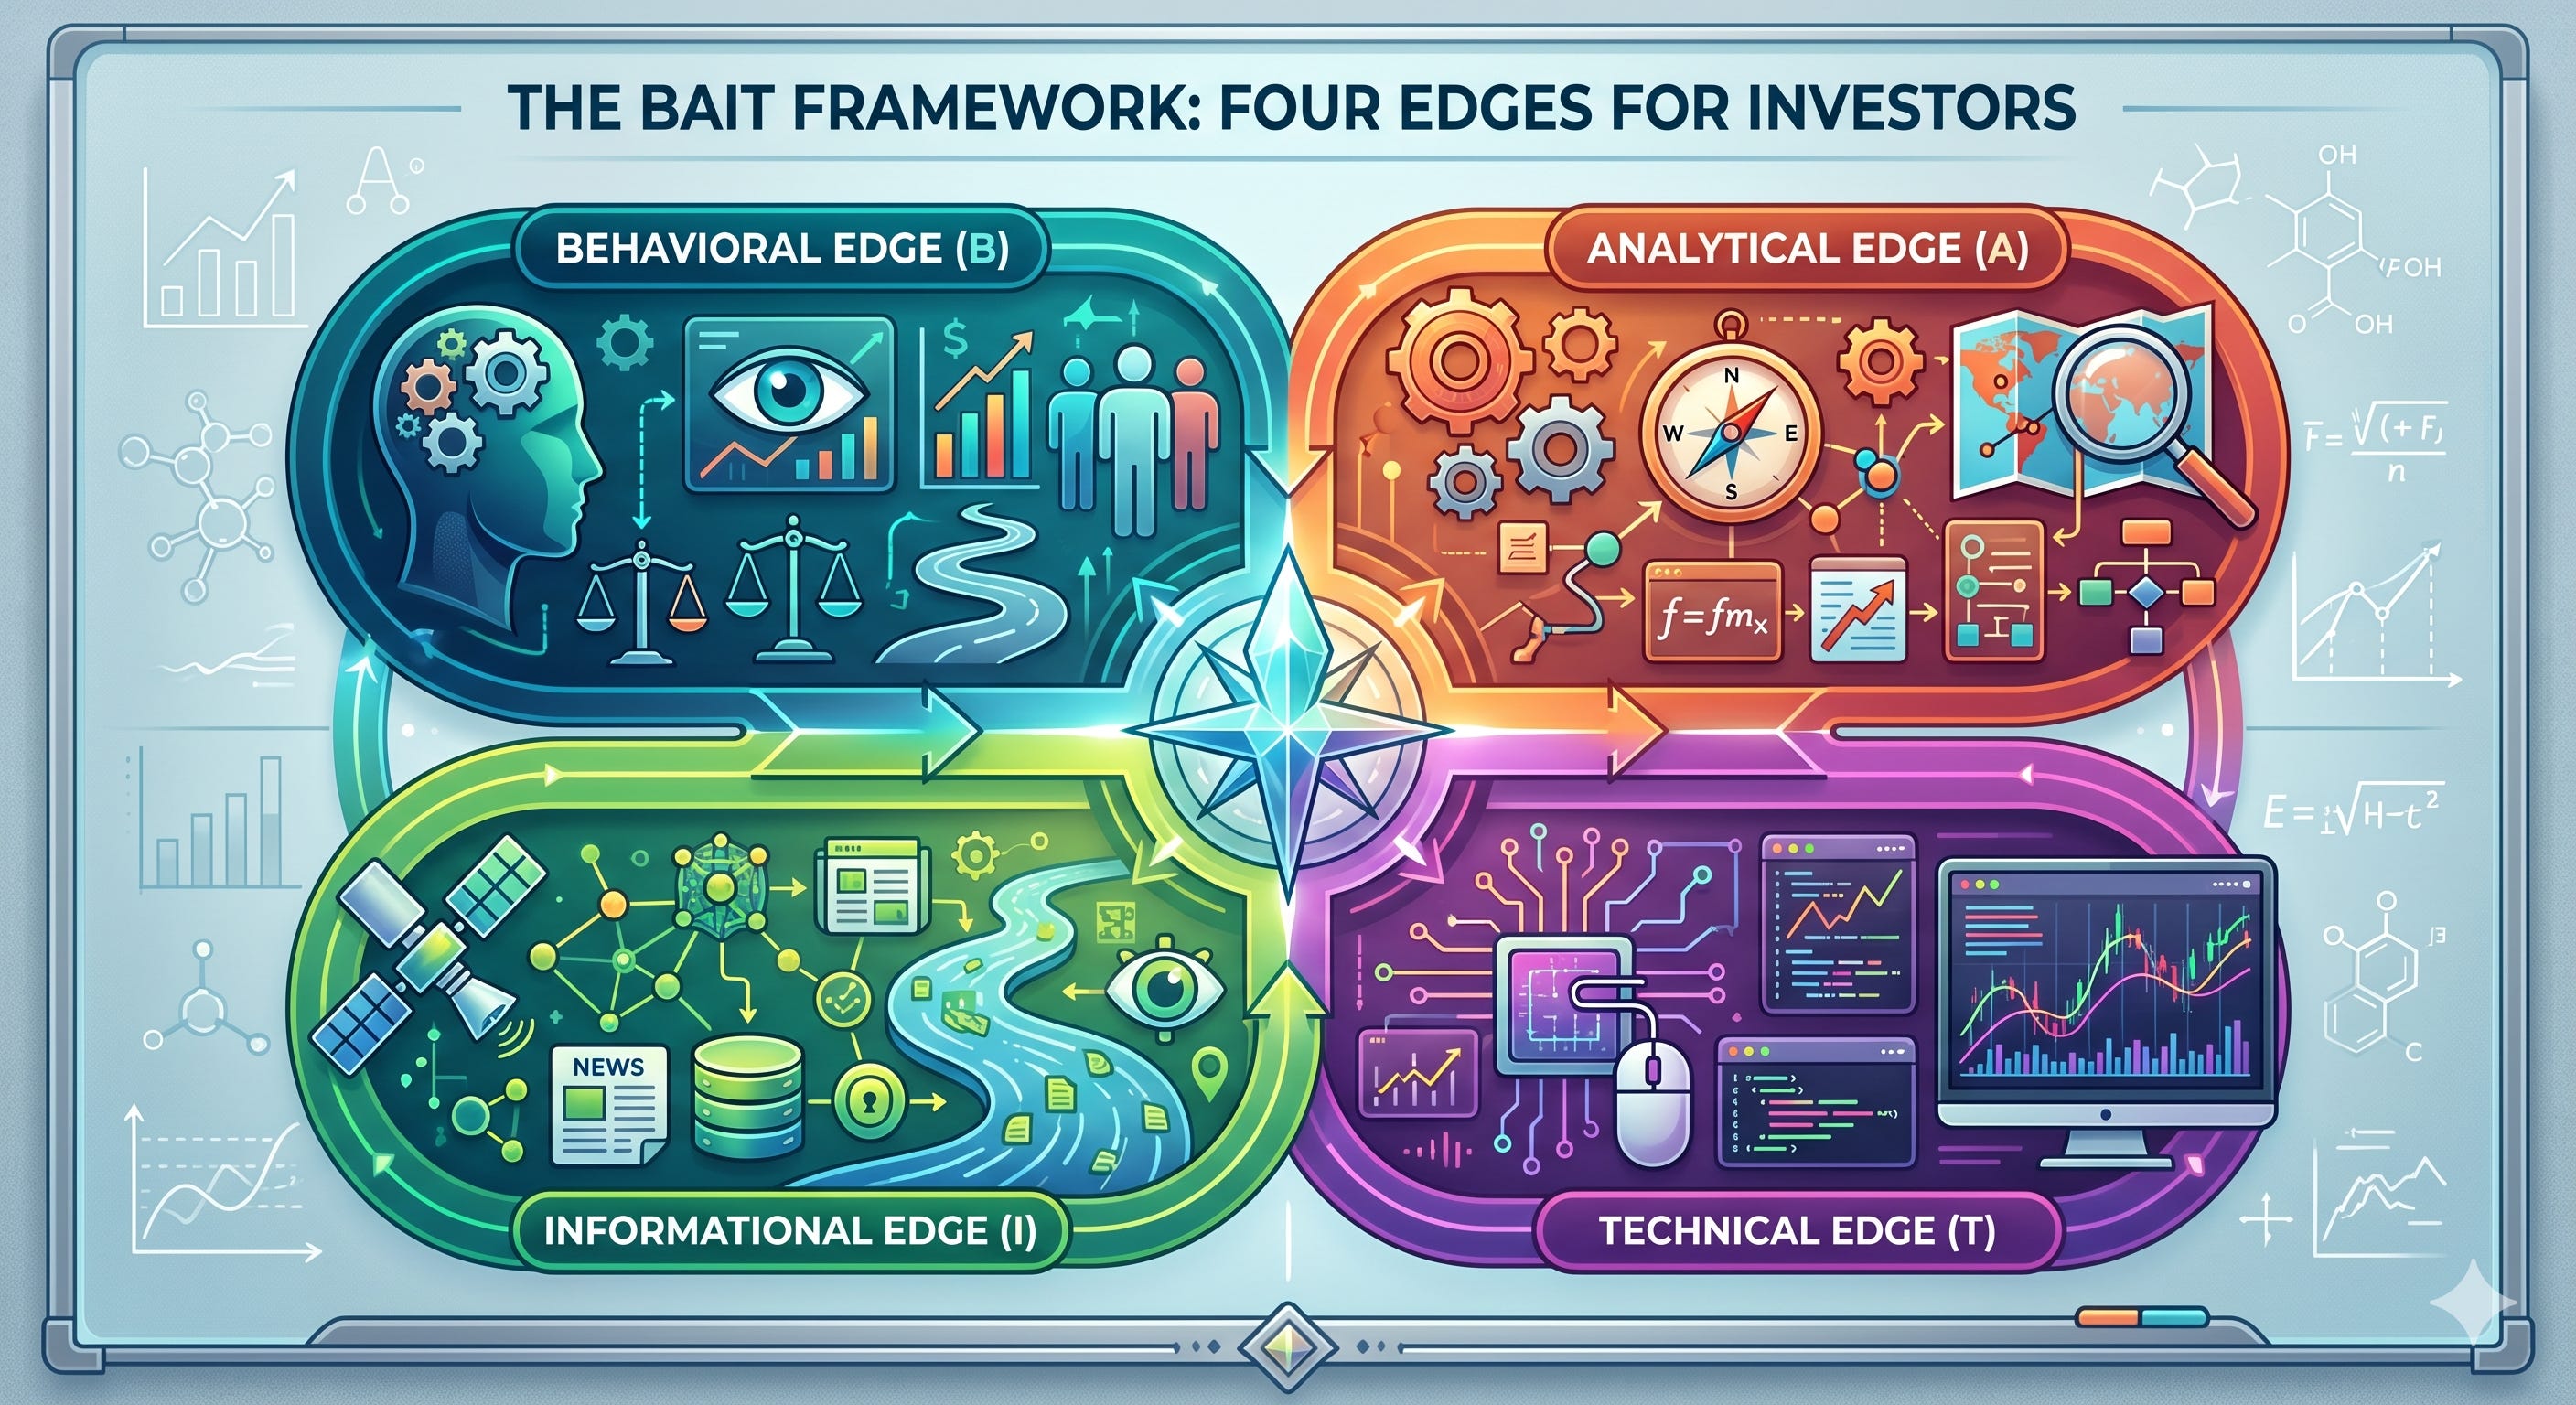
This brings us directly to the BAIT framework, a mental model built on the reality that markets are frequently choked with …
behavioral (B),
analytical (A),
informational (I), and
technical (T)
… inefficiencies.
“Broadly, Bill Miller argued that there are three competitive advantages in investing: informational (I know a meaningful fact nobody else does); analytical (I have cut up the public information to arrive at a superior conclusion) and psychological (that is to say, behavioural). Sustainable competitive advantages are usually a product of analytical and or psychological factors.” - Nick Sleep
Before we explain each edge in more detail, let me share some general observations: An edge only exists when you can confidently identify who is on the other side of your trade, while proving with sound theory or empirical evidence why they are wrong and you are right.
If you cannot articulate the counterparty’s specific error, you are the mark at the table (we’re back to the poker analogy).
In the vocabulary of modern finance, a market inefficiency can be expressed in several distinct ways depending on your level of mathematical rigor. It represents a (positive) expected value that beats the return generated by the broader market. If the market generates a 9% IRR over the next five years, your edge should be measurable by you achieving a higher 5-year IRR. Buffett, the greatest investor of all time, CAGR-ed at roughly 20% over his lifetime (many decades) fwiw. Highly impressive.
But again, the calculation of an “edge” works beautifully in games of defined risks and outcomes, games where you can quickly accumulate large sample sizes, though it becomes significantly cloudier in games of true economic uncertainty and games where you bet infrequently (think of the handful of bets an investor places in a calendar year vs. the 100,000+ of hands a poker player plays in the same time frame) where calculation errors creep in and luck becomes another dominant force.
Culturally, the fancy way to label this phenomenon is a variant perception – a well-grounded view that stands completely apart from the consensus.
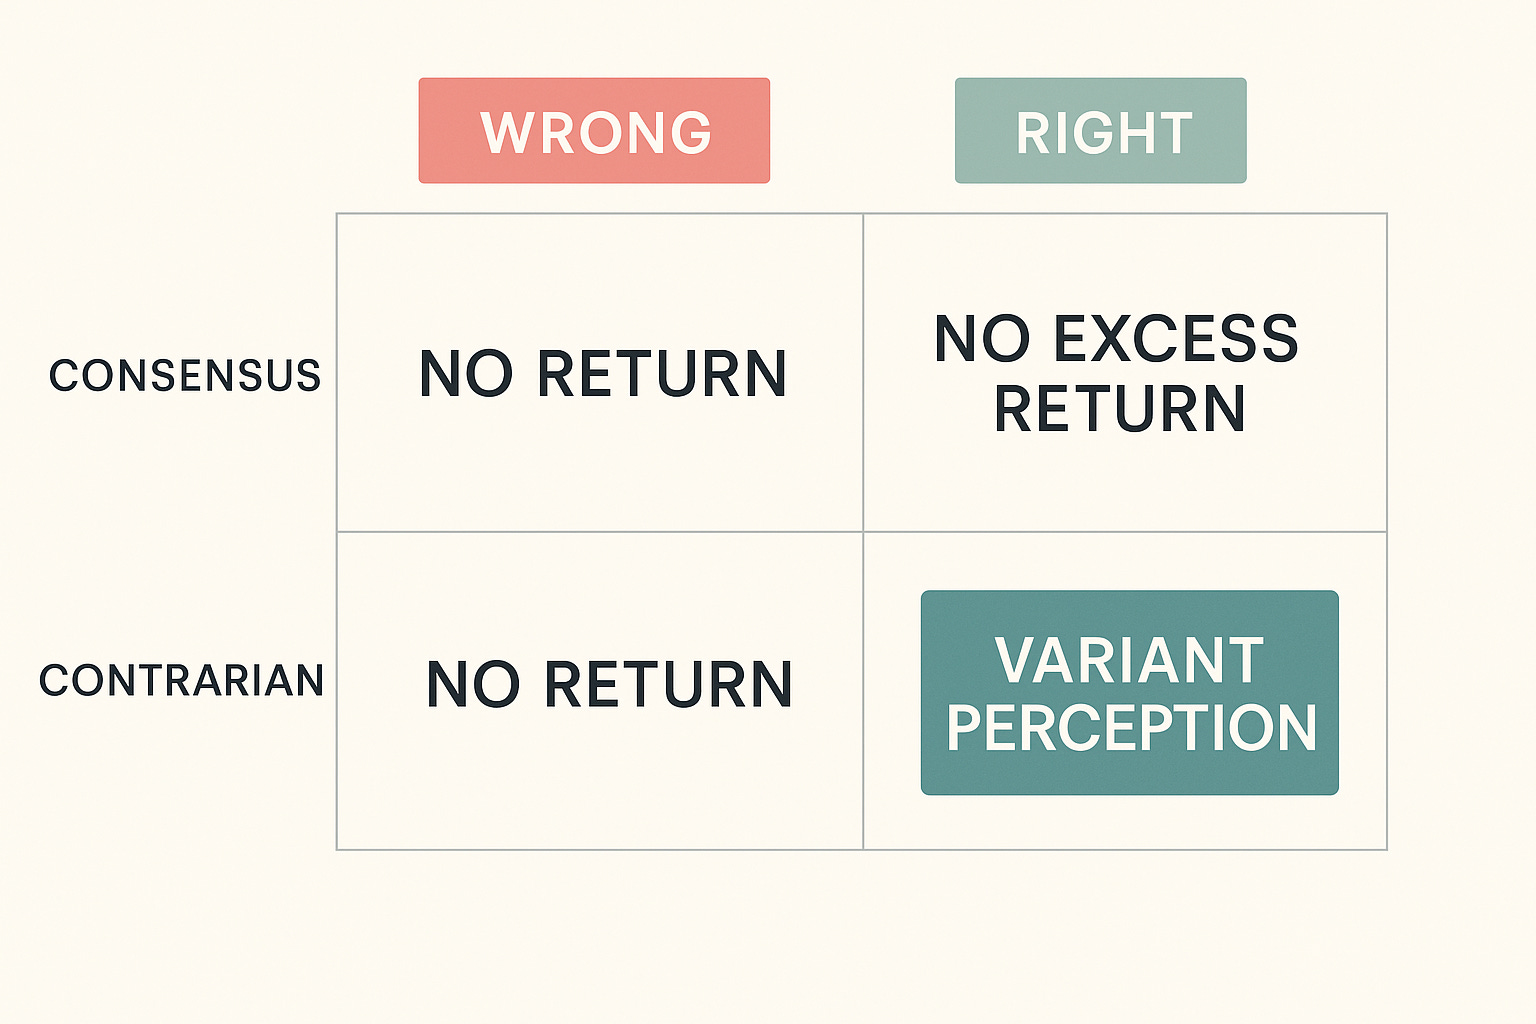
Practically, however, an inefficiency is just the gap between current market expectations and structural fundamentals. You could measure this delta using traditional discounted cash flow modeling and reverse DCF analysis to isolate exactly what the market is pricing into an asset today.
There is a critical secondary considerations here that most amateur investors ignore: position sizing. Size matters. In fact, you should never place a bet without a clear edge, regardless of how highly you rate your own internal skill. This is really important to understand, and if anything, this should be your key takeaway from reading this piece.
“Without an edge, one should not bet. Ever. Regardless of skill.“ - Tiho Brkan
Your bet sizing must be dictated exclusively by the magnitude of the external edge you are exploiting. The larger the edge, the larger your capital allocation can be; in theory, up to a mathematically optimal limit. Push past that threshold, and over-betting will inevitably lead to financial ruin.
"Playing poker in the Army and as a young lawyer honed my business skills .. What you have to learn is to fold early when the odds are against you, or if you have a big edge, back it heavily because you don't get a big edge often." - Charlie Munger
And to tie this discussion back to poker again: this is the exact blueprint used in modern poker. In a game that is now effectively solved, a mathematically optimal bet size does in fact exist for every scenario. However, applying this in practice requires a nuance that amateur investors often miss: you cannot simply deploy a single, predictable size all the time. To keep opponents from exploiting, elite players must balance their strategy by thinking in bet-size ranges. You scale your allocation based on the strength of your edge, while remaining mathematically unpredictable to the rest of the table.
Back to investing … I’d argue that in today’s environment, locating these setups, setups that offer you to lean into and exploit an edge is brutally difficult. Wait for the fat pitches.
“We’re always looking for something where we think we have an insight which gives us a big statistical advantage. And sometimes it comes from psychology, but often it comes from something else. And we only find a few, maybe one or two a year.” - Charlie Munger
So what do the four edges mentioned above actually refer to?
“Knowing when you have an edge is very difficult, but in my experience it is the critical factor that allows us to stand out in the ultra-competitive world of institutional money management.” - Brian Bares
Behavioral Edge
I view the behavioral edge as a direct exploitation of psychological breakdowns in the market landscape. When investors are gripped by collective panic or blind euphoria, they stop acting as cold calculators and begin reacting to raw emotion. Fear reigns supreme. This herd mentality creates an external setup where asset prices dislocate wildly from their actual worth, creating an attractive playground for rational capital. My role here is to let my intensive training in sentiment take over while the crowd makes expensive, emotional mistakes. You cannot force these opportunities. They appear situationally when market participants abandon their senses, hand-delivering a structural mispricing that you can calmly capitalize on if you possess the internal discipline to remain completely rational while others implode.
“Both poker and investing are games of incomplete information. You have a certain set of facts and you are looking for situations where you have an edge, whether the edge is psychological or statistical.” - David Einhorn
Analytical Edge
An analytical edge manifests when you look at the exact same public data as your competitors but arrive at a vastly superior conclusion. This is the art of variant perception, where you articulate a well-grounded view that stands completely apart from the consensus. The consensus is wrong. I actively execute this edge by calculating the stark delta between current market expectations and underlying business fundamentals, utilizing tools like a reverse discounted cash flow analysis to decode what the market is pricing in. It requires deep cognitive skill. You are essentially identifying a massive pricing breakdown because the crowd is misinterpreting a company’s long-term trajectory, allowing you to capture a setup where your unique interpretation of the data aligns with reality while the market remains blind.
“Investors operate with limited funds and limited intelligence; they do not need to know everything. As long as they understand something better than others, they have an edge.” - George Soros
And as Howard Marks very clearly articulates in the quote below, more data or more manpower does not equal better results. Raw scale is a commodity. Anyone with enough capital can hire 160 analysts, buy expensive data terminals, or run massive computing clusters. If everyone has access to the same raw numbers (lack of informational edge) and processes them using standard methodologies (lack of analytical edge), they will arrive at the exact same conclusion. That’s why some fund managers can also ask for multi-million dollar paychecks. They possess unique abilities that allow them to arrive at variant perceptions that turn out to be correct.
"I was recently on a panel that was asked what gave our firms their edge. One panellist responded “we have 160 analysts around the world”. To me, that response demonstrated a total lack of insight. Unless those 160 analysts are more astute than the average investor, they’ll contribute nothing. Certainly another 160 wouldn’t double the managers ability to add value (if they could everyone would be an analyst).” - Howard Marks
Many people argue that finding an analytical edge has become incredibly hard and that this edge may entirely disappear soon.
"There are a lot of trends going on now that make the business very tough. You've had a lot of smart people come into it, making it much harder to find opportunities. You need to determine what your real competitive advantage is." - John Phelan
PS: Funnily, I also came across this quote from Ray Dalio on the website of MastersInvest, and I’m wondering whether Marks was actually referring to Dalio?
“If you’re going to come to the poker table, you’re going to have to beat me. … We have 1500 people who work at Bridgewater. We spend hundreds of millions of dollars on research and so on, we’ve been doing this for 37 years.” - Ray Dalio
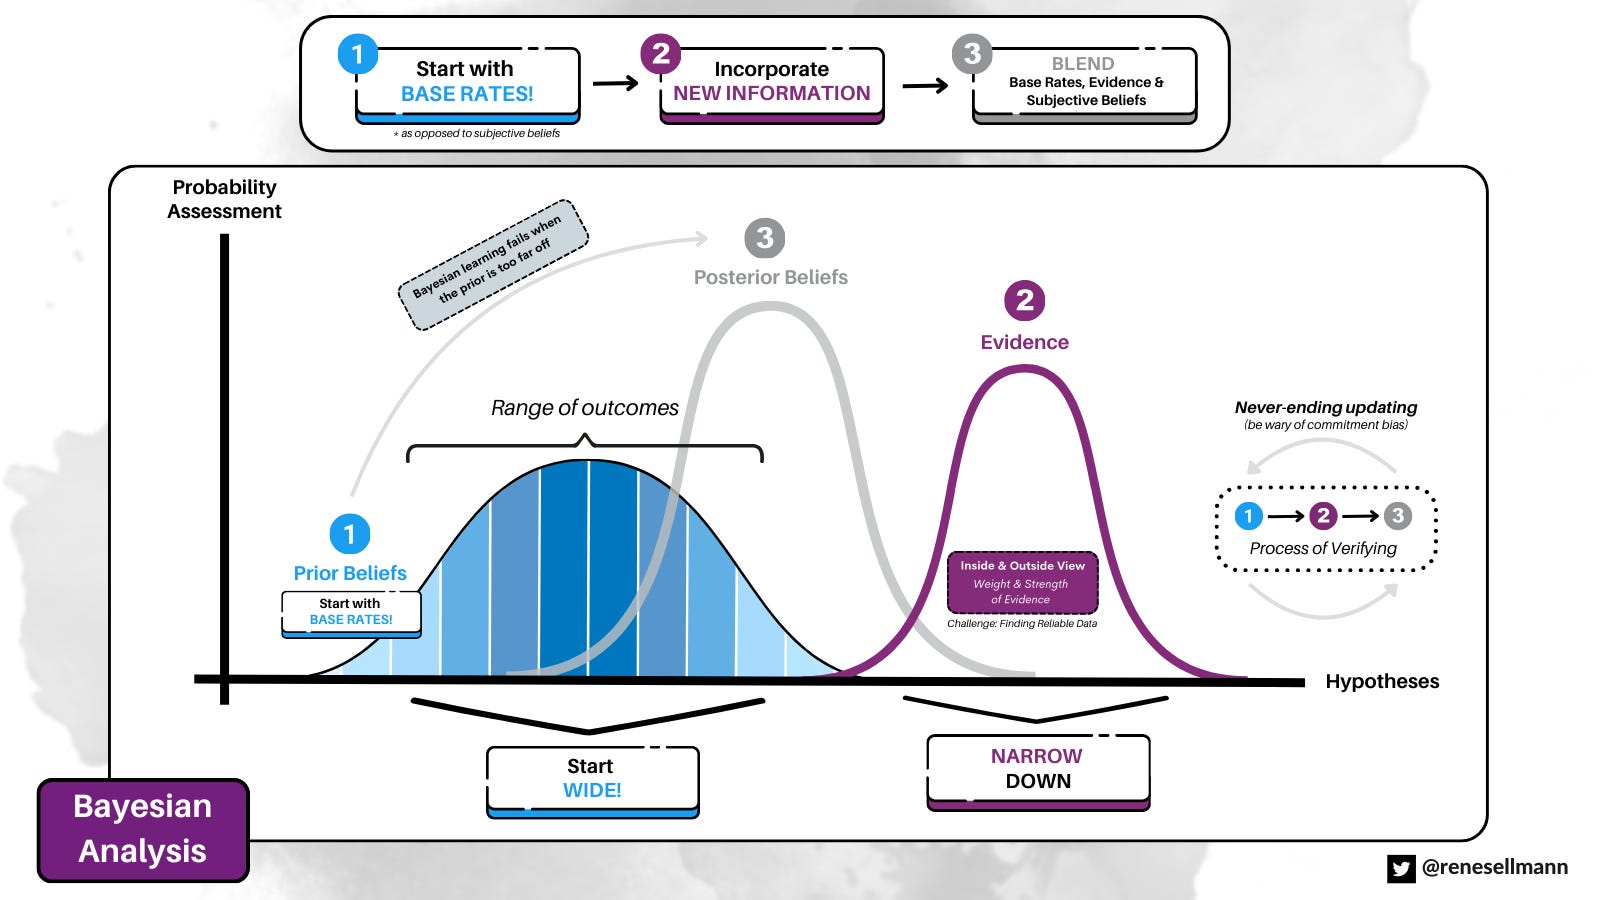
PSS: Don’t forget to constantly update your (analytical) view as new information flows in.
The rest of this post is FREE to read. I only ask that you subscribe, which costs nothing and can be undone with a single click whenever you like.
The wall also helps keep my writing from being freely scraped by AI crawlers, so I hope you understand the small extra step.
In return, you get every deep dive, earnings review, and process piece I publish, straight to your inbox.