

To me, it seems as if Terry Smith is currently the favorite punching bag of the value investing community. It is a role he seems to accept with a mixture of dry wit and a stubborn refusal to pivot. After a significant period of underperformance, his “Quality” strategy is under heavy fire from the usual suspects in the financial press.

I’ve noticed a curious phenomenon that repeats every cycle: price drives narrative. When a fund is soaring, every investor is a cheerleader, but when it stalls, the silence is deafening. My X feed used to be littered with Fundsmith content during the peak of the quality bubble a few years ago, yet today I see … nothing.
It is as if the investing community has collective amnesia regarding the principles that made Smith legendary. But if you actually take the time to watch the 2026 Annual General Meeting, you won’t find a man in retreat. Instead, you’ll encounter one of the most rational voices in a market that feels increasingly unhinged.
While much of the world is currently drunk on AI hype, Terry is soberly dissecting the data and looking back at 1929 and 2000 for clues on what happens next.
“So why study history? We study history not to know the future but to widen our horizons, to understand that our present situation is neither natural nor inevitable, and that we consequently have many more possibilities before us than we imagine.” - Yuval Noah Harari
He didn’t mince words during the opening of the meeting. “The one [word] I would use to describe it for the last 12 months is poor,” he admitted, “if we keep going like that we will all become poor.”
It was a refreshingly honest take in an industry where managers usually bury bad numbers under a mountain of jargon. He isn’t making excuses, even as the “commentariat” accuses him of precisely that.
He’s providing context. He emphasized that “what will determine the outcome... is not what’s happened in the last 12 months but what we do in the next 12 years.” I find that perspective invaluable. He has clearly internalized the timeless principles that work over decades, even if they hit rough patches in between.
In this post, I’ll explore the five most thought–provoking insights from this year’s session and why Terry is willing to look like a “loser” today to avoid the carnage tomorrow.
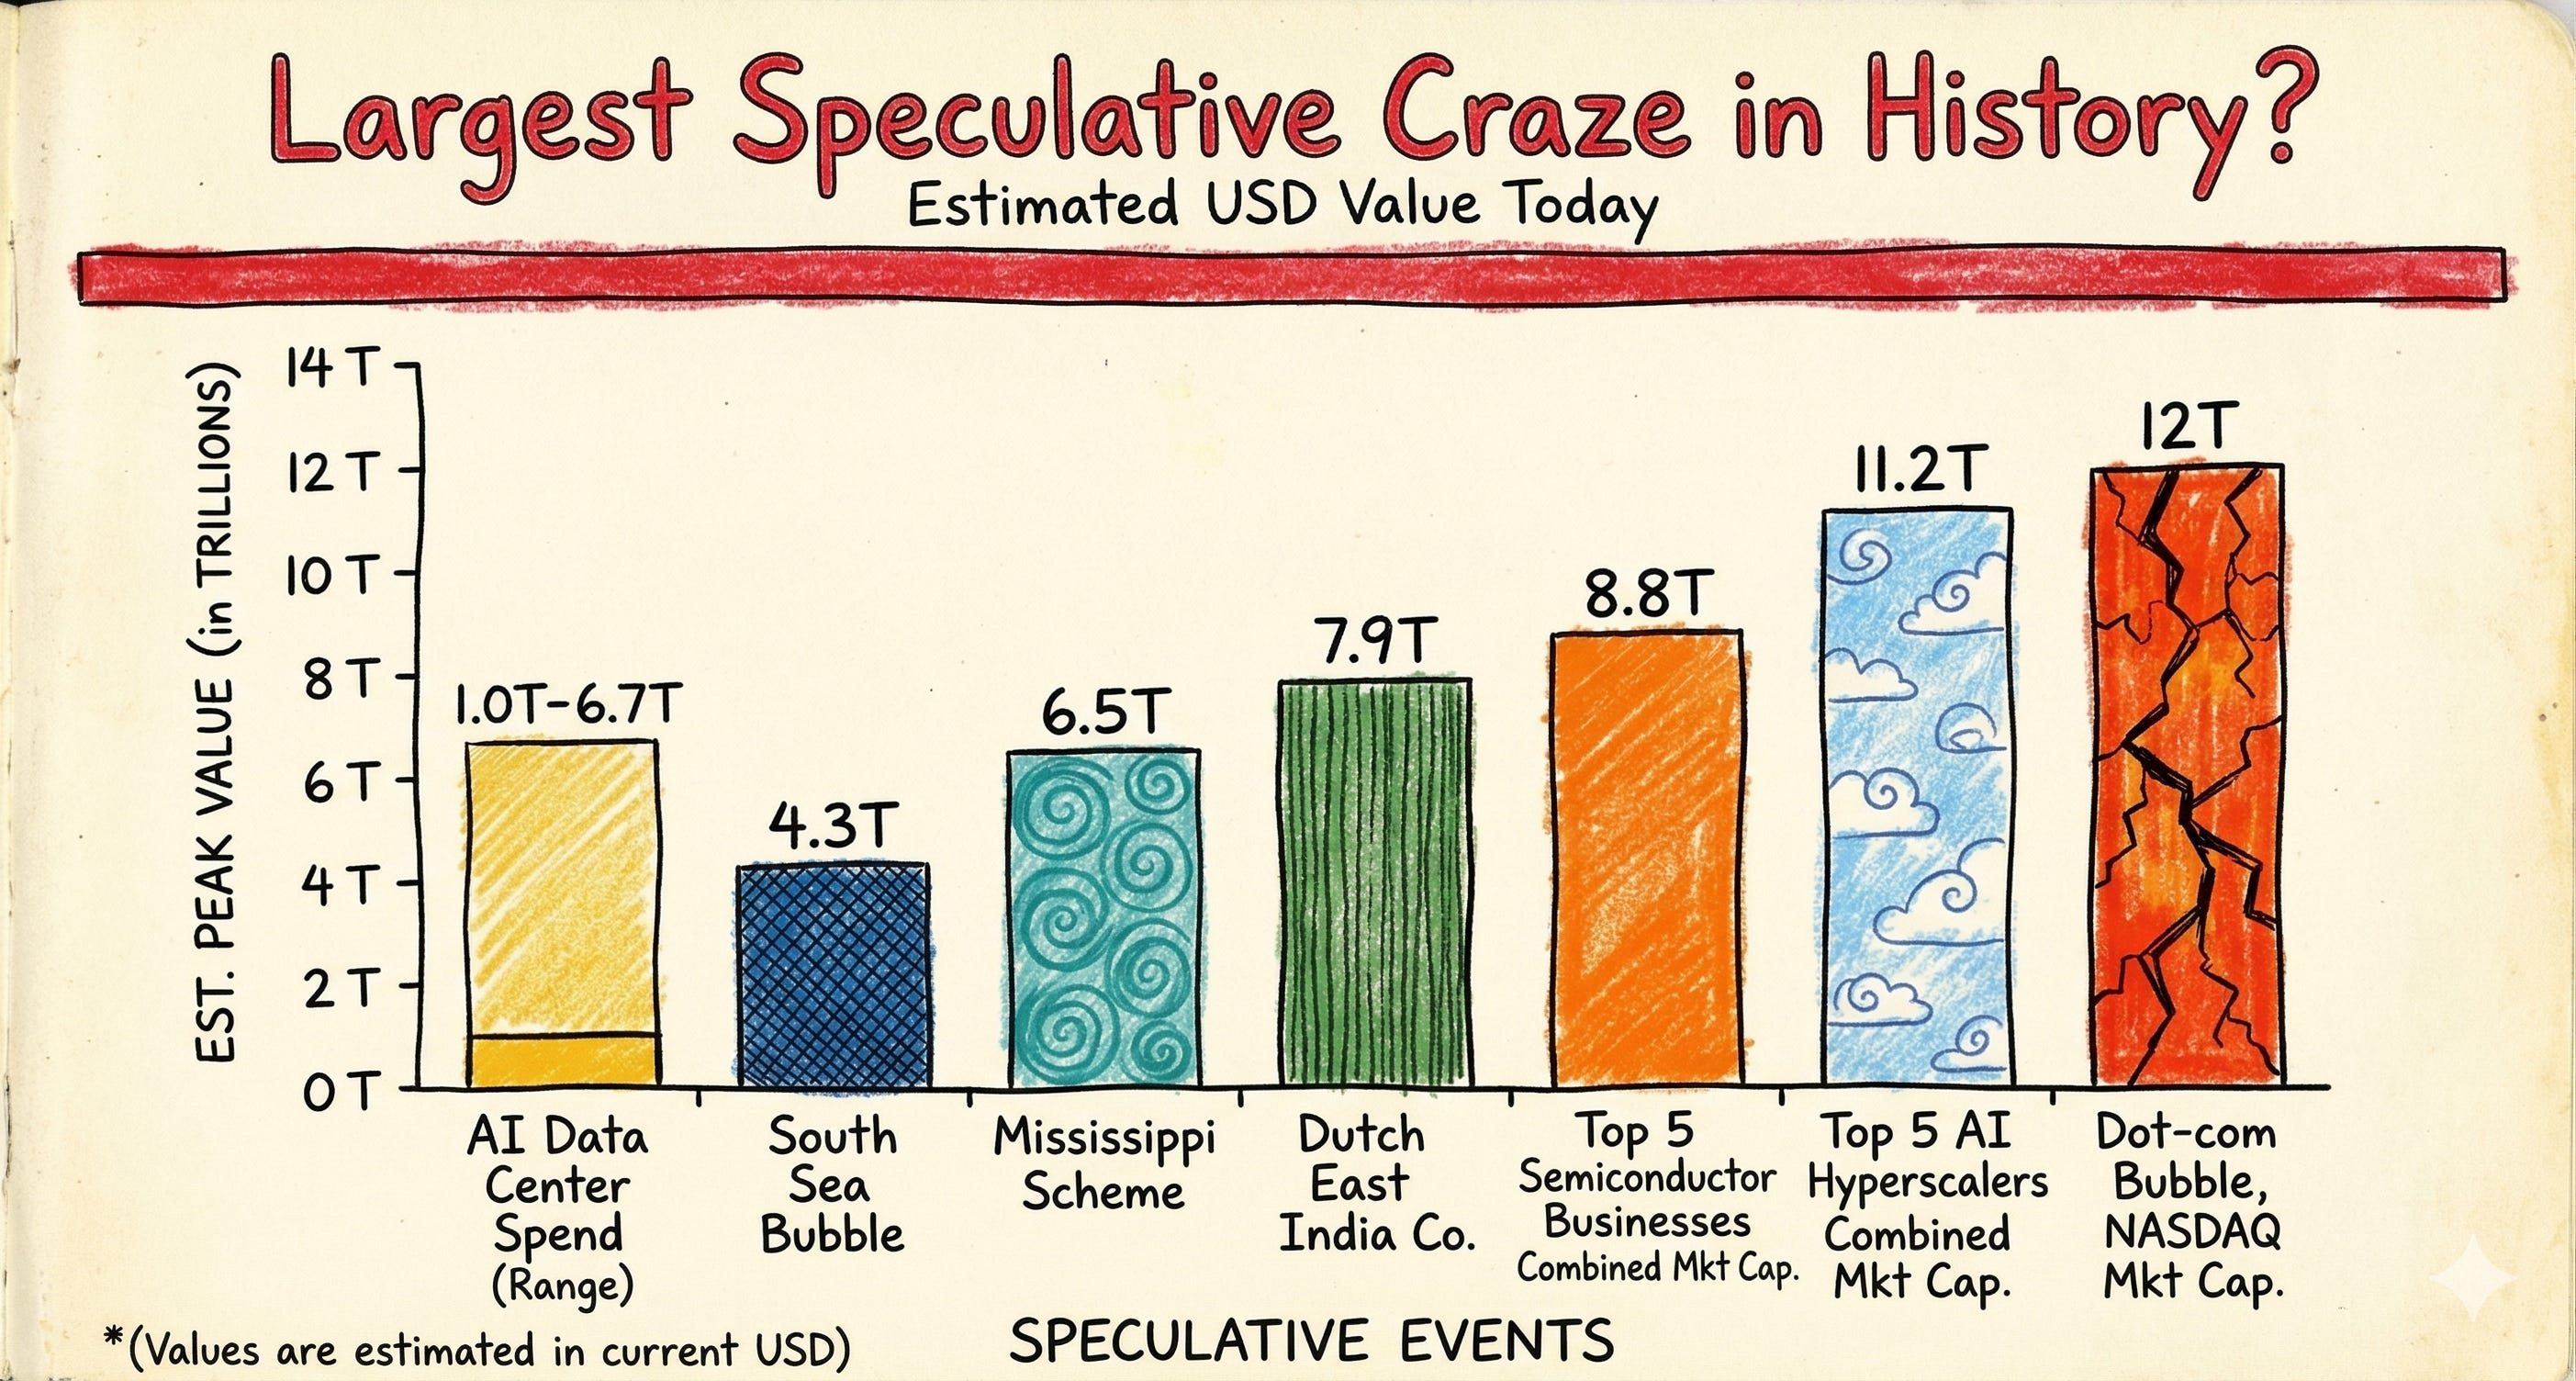
#1 – Why Global Giants are Suddenly Trading Like Penny Stocks
Something about the market’s current structure feels fundamentally off to Smith. It should feel off to you, too. We have reached a point where multi–billion dollar daily moves in single stocks – once once–in–a–generation anomalies – have become routine. It certainly feels this way to me. And the data Smith presented was confirming this “hunch”: More recently, Adyen fell 22% in a single session, Oracle surged 36%, Estée Lauder dropped 19%, and AMD saw a 17% slide.
These aren’t speculative penny stocks; they are some of the largest enterprises on the planet. As Terry noted with his characteristic bluntness, “Something’s not right when a multi–billion dollar company’s share price can move 36% in a day”.
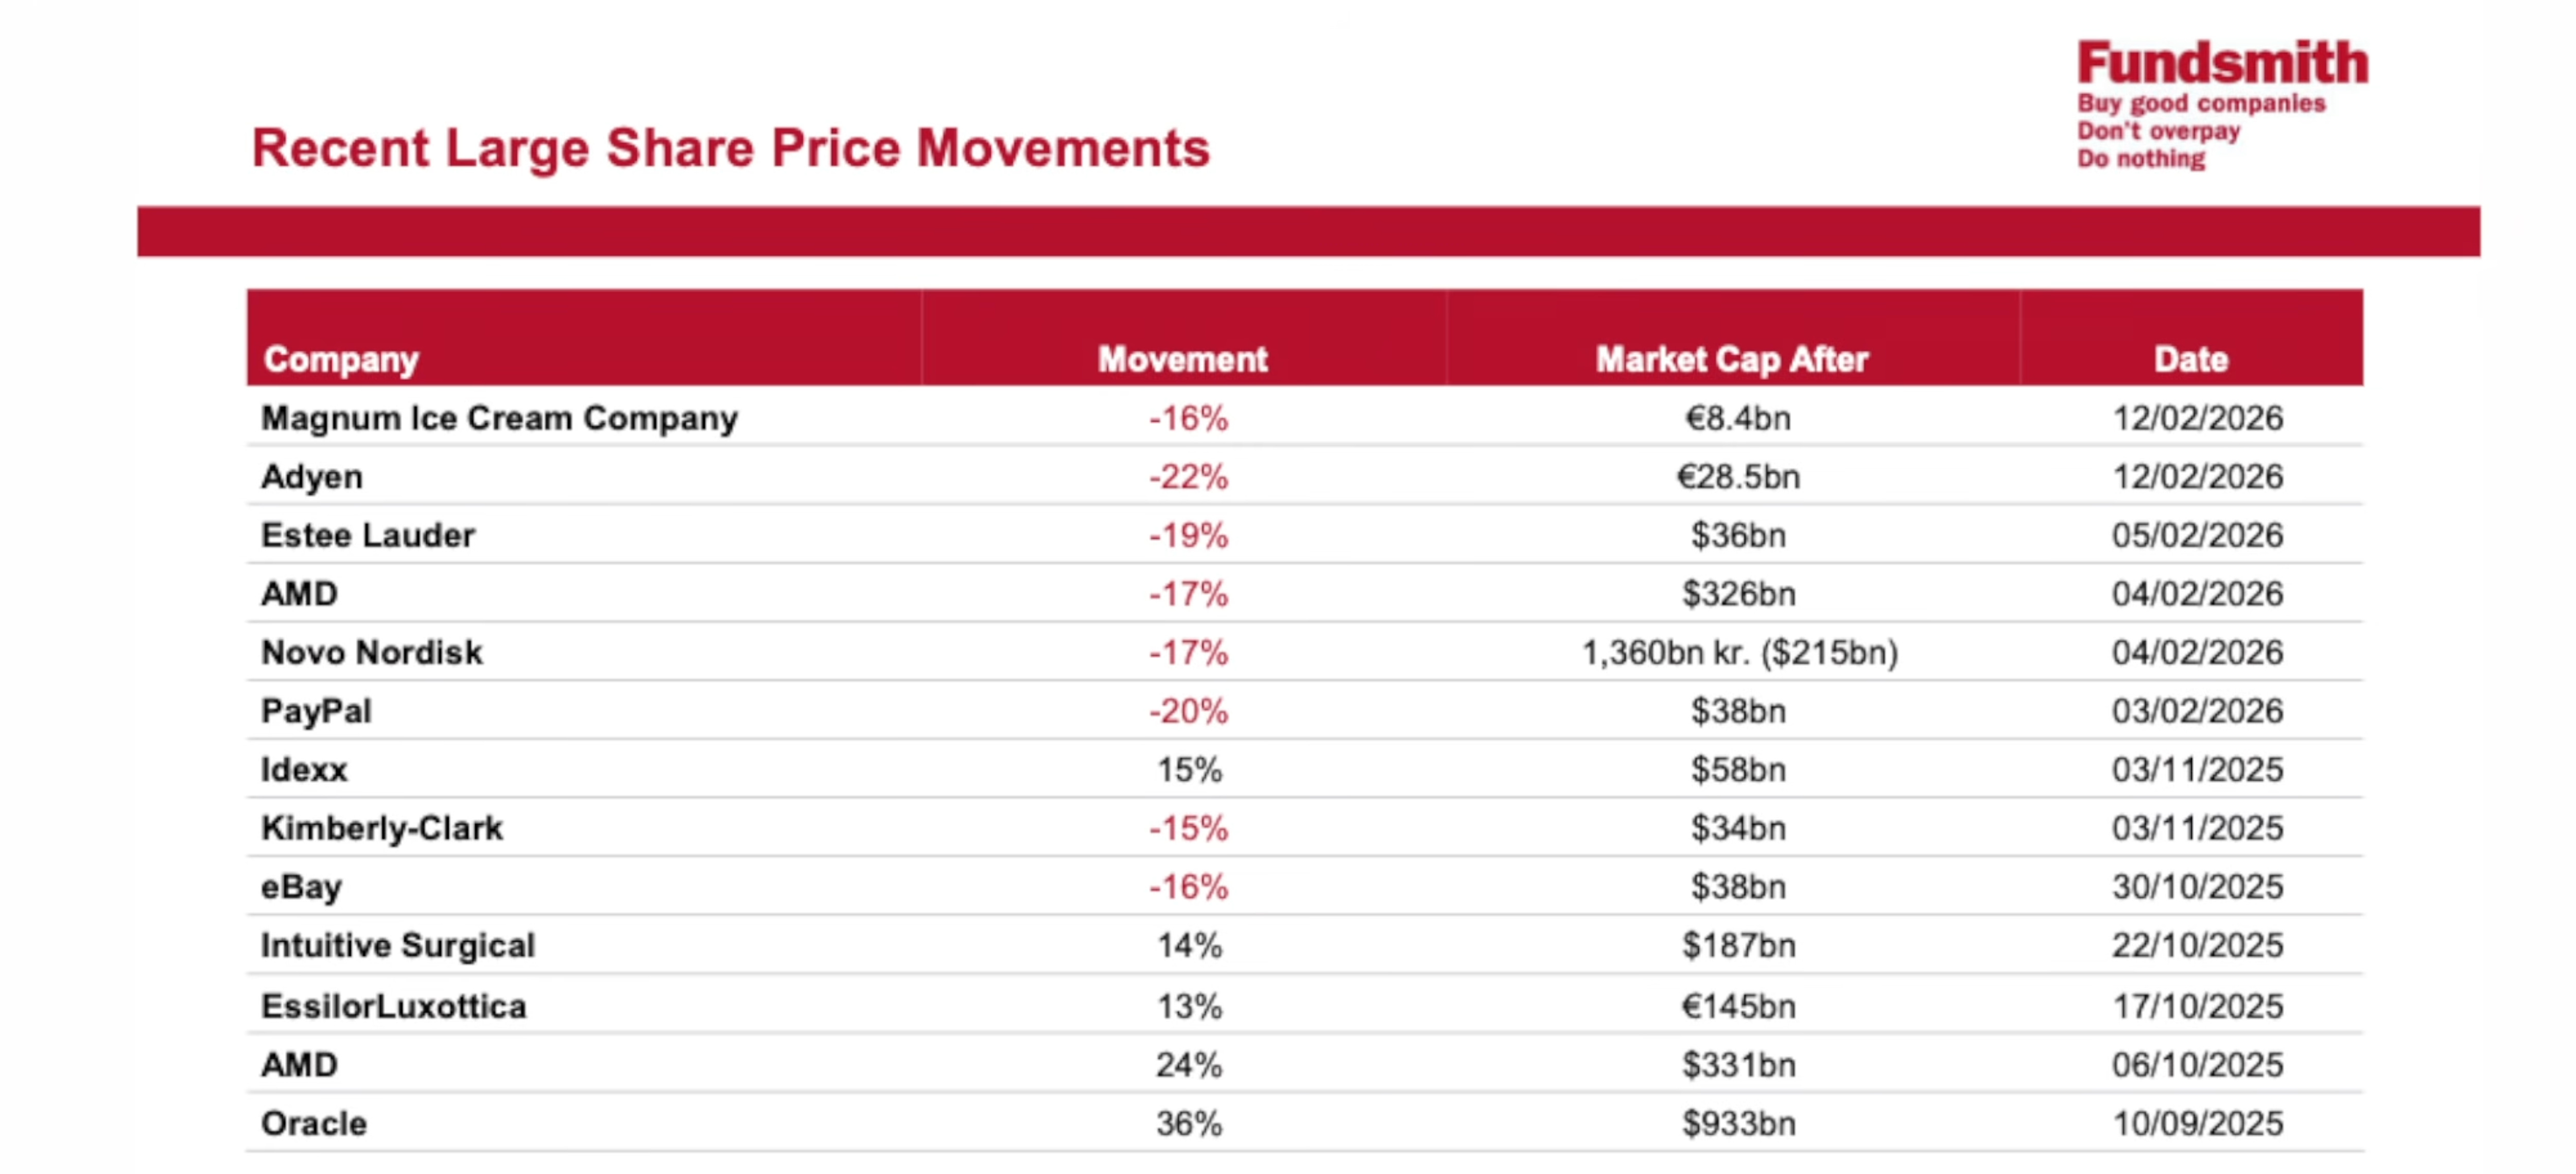
This isn’t just volatility in the traditional sense. It is a structural failure driven by what academics call the “Inelastic Markets Hypothesis.” Because more than half of all equity assets are now held in passive index funds, there may simply not enough active liquidity to settle the price fairly. Index funds are mandated to buy or sell regardless of valuation, which creates a massive imbalance. Smith pointed to research by Gabaix and Koijen suggesting a multiplier effect of roughly 5x – meaning every dollar of active trading can impact a company’s market cap by five dollars.
“You know, if I go and sell Microsoft this evening and put it all into PepsiCo tomorrow, it doesn’t aQect the valuation of either Microsoft or PepsiCo. It’s unaffected. However, these people have looked at the data and discovered that the actual market impact for a dollar going from one security to another in recent years has been a multiplier of somewhere between three and eight times. So when you took your money out of us and the dollar went into Nvidia, the effect on the Nvidia price was somewhere between $3 and $8 on average $5 between those. That’s a startling number.
And the reason for it is, as I tried to explain in the in the title, the inelastic markets hypothesis, because the well, if you take the dollar out of their out of our fund and put it in the passive fund, it doesn’t make any difference. works providing there are people in a in a position to take the opposite view. So if you think that something is vastly overvalued uh it can by being driven by the momentum of index funds that will be bought down to earth by people who are running active funds who will sell it or even short it in the case of hedge funds. What they’re pointing out is there are increasingly fewer of those people because of the rise of index funds. There are increasingly fewer active funds to do that. And even within those active funds, there are an awful lot of people who’ve become index closet index trackers. They’re running an active fund, but they stay pretty damn close to the index for for survival reasons.”
I have read that markets remain theoretically efficient as long as roughly 10–15% of assets are still actively managed (I cannot recall the exact figure), since passive funds are, by nature, price agnostic. But that theory feels increasingly detached from the reality I’m seeing on the ground. It isn’t just the sheer volume of indexing that is the problem; it is the changing nature of the remaining active capital. The rise of multi–strategy “pod shops” and high–frequency players has likely shifted the remaining active liquidity from long–term price discovery to short–term momentum chasing. We discussed these changes in market structure in the series below:
Playing a Different Game: When Fundamentals Aren’t Enough Anymore! (Part 1)

This will be a 3-part series. If you don’t want to miss the follow-up pieces, make sure to subscribe to the blog.
Julian Robins touched on this when he described the current environment as a “feedback loop on steroids.” When everyone is crowded into the same few names, and even the “active” players are often just front–running index flows or managing tight risk limits in a pod, the traditional stabilizer is gone. As Terry put it, there are “increasingly fewer of those people” left in a position to take the opposite view and sell an overvalued stock. We are witnessing a new, much more dangerous arena where price discovery has been sacrificed at the altar of indexing.
#2 – The Seduction of Performance Chasing
I have always found it fascinating how investors treat fund managers like football coaches – as soon as you have a bad season, the fans want you sacked. This “hire the winners and fire the losers” mentality is the most common way to destroy wealth in the long run.
During the meeting, Terry shared a chart that should probably be pinned to the monitor of every retail investor in the country. It showed that the top–performing quintile of funds over a three–year period often becomes the worst–performing group in the following three years.
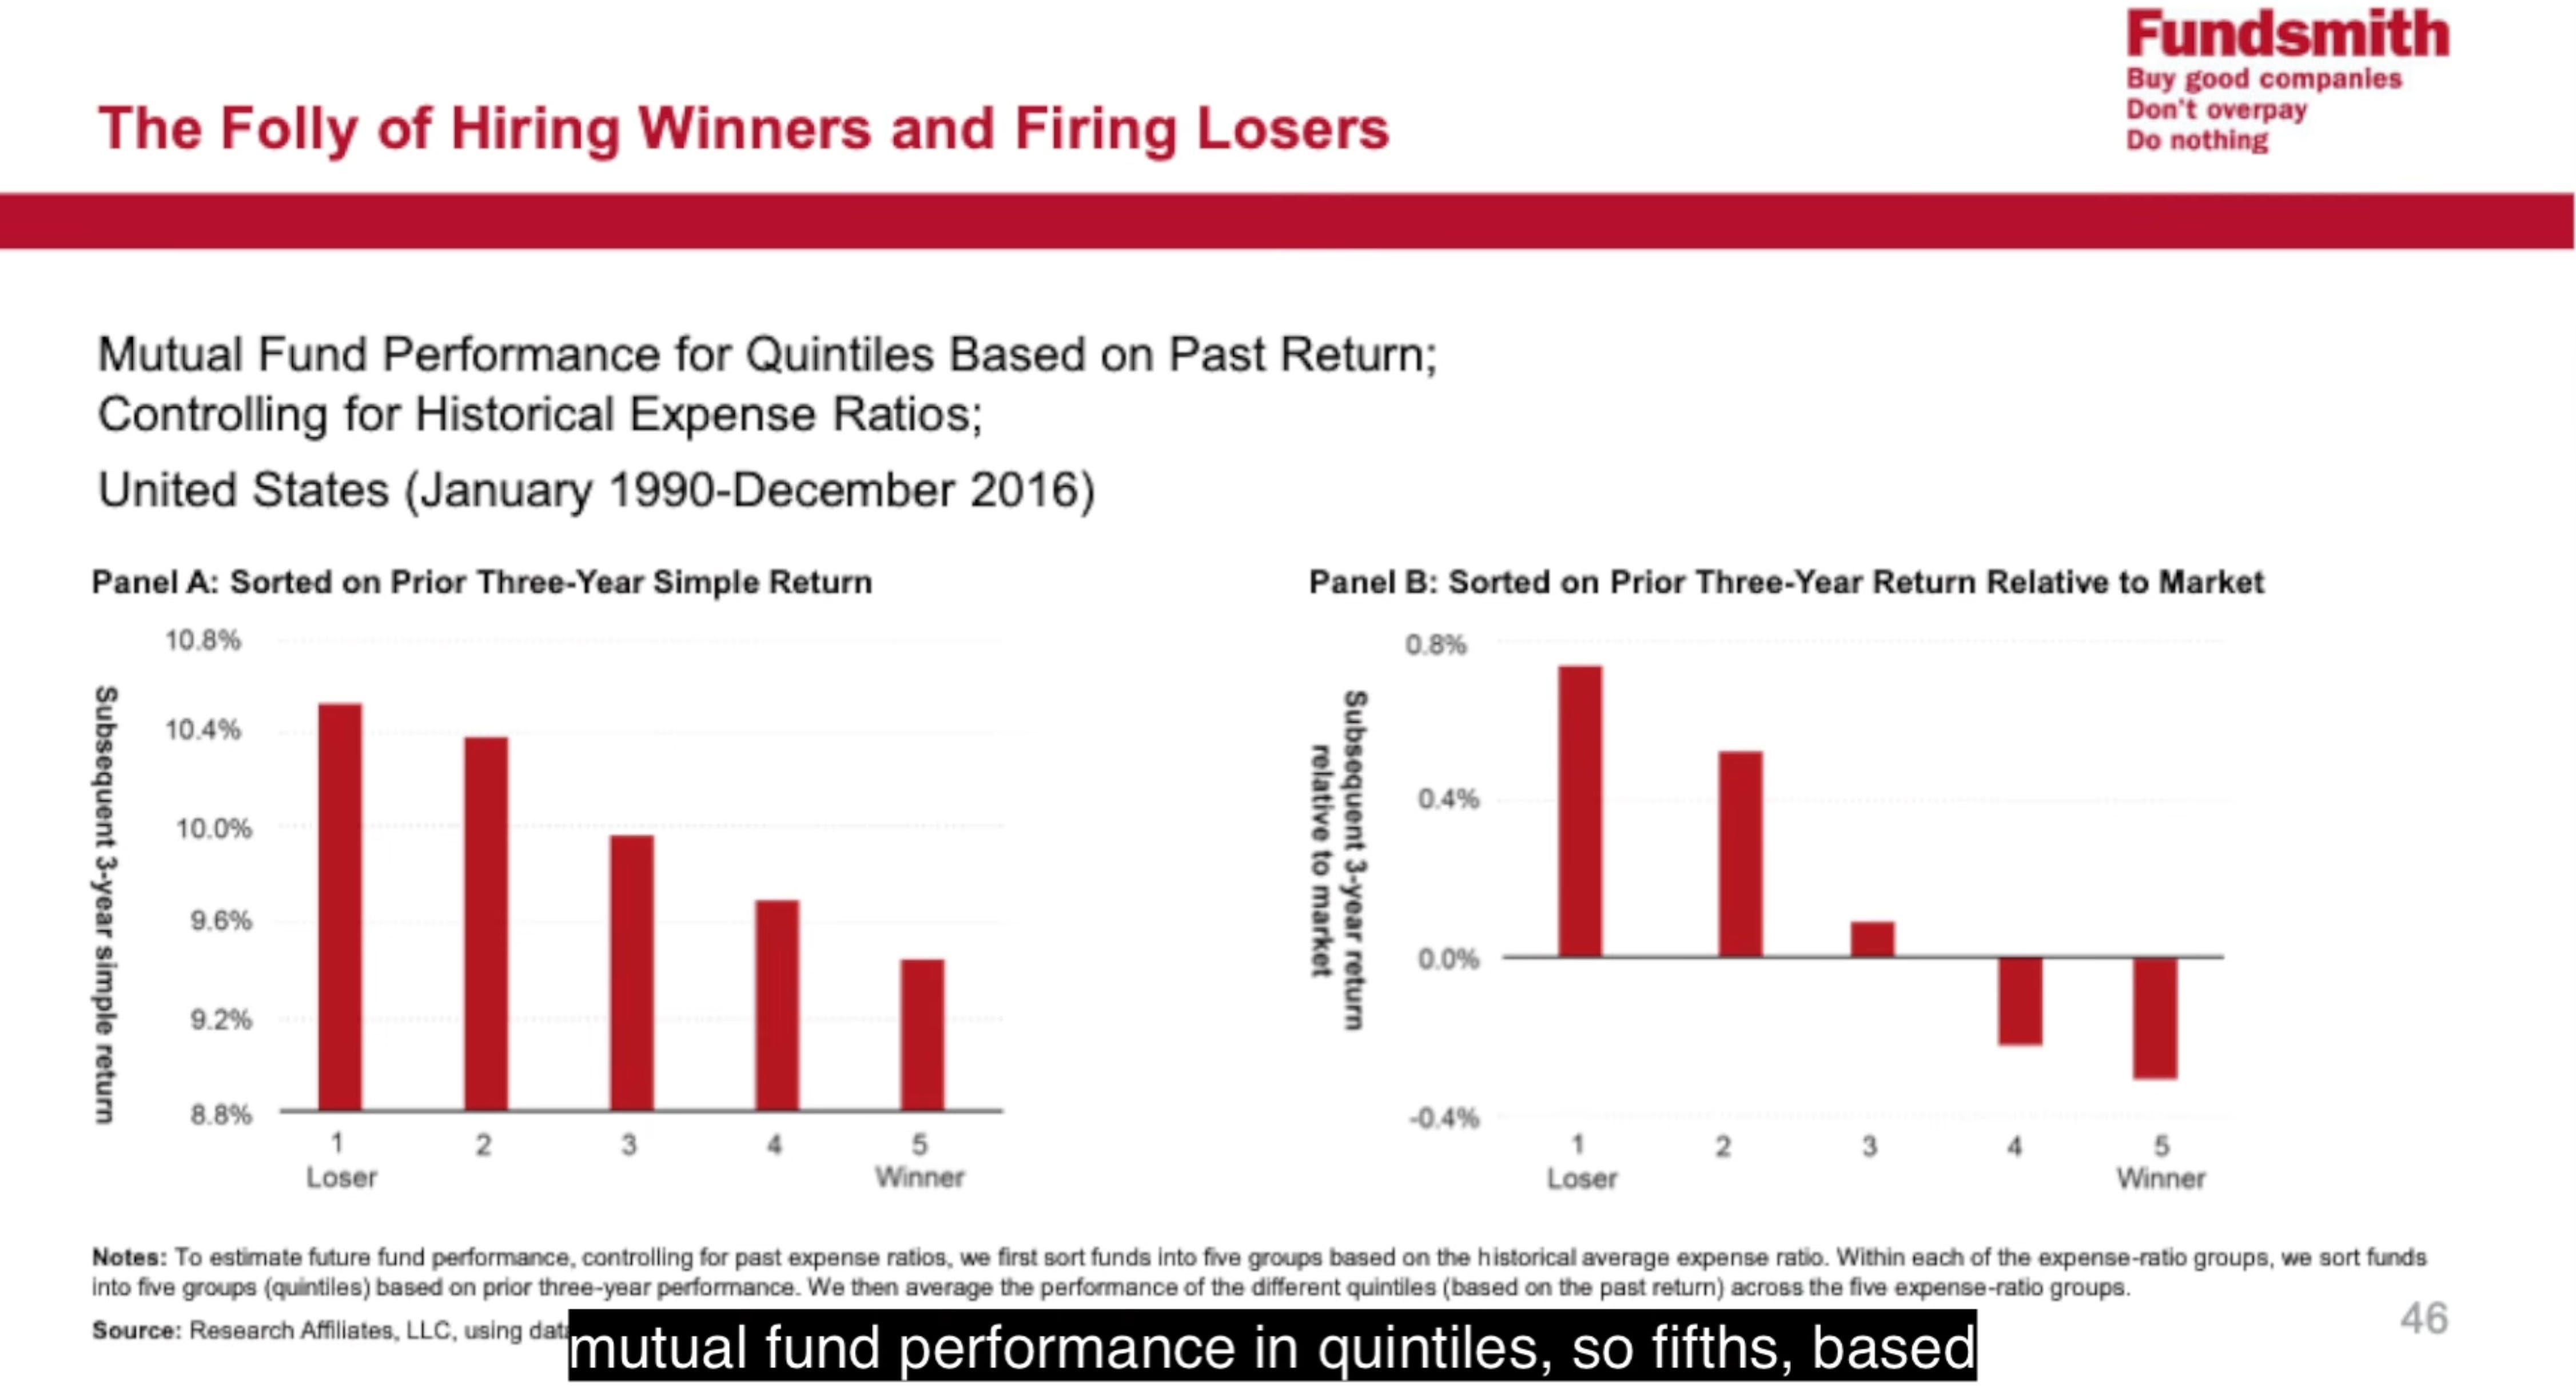
Mean reversion is not just a theory; it is a brutal, impartial law of finance. As Terry dryly noted, “It’s a very natural human reaction to want to move to what’s working now, but in investment, that’s usually a recipe for disaster.”
You see this happen every time a specific style–be it Value, Growth, or Quality–goes out of favor for a few quarters. The pressure to pivot is immense.
It isn’t just about the numbers; it is about the psychological toll of underperforming when everyone else seems to be getting rich on something you don’t own. You start to doubt the process.
“Question: ‘Is the most diQicult part of underperforming a benchmark the psychological pressure of doing something different to catch up?’
Answer: […] Yes, it is a simple answer… look, […] it’s better in career terms to fail conventionally than is to succeed unconventionally. Because even if you’re successful, I mean, you saw during the 10 years when we were doing very well in the lead up to this, the amount of criticism that we got then for doing something different … and now it’s just easier to criticize because you’re doing something different and it doesn’t work. But yeah, the psychological pressure is considerable.“
You wonder if the “Quality” factor has finally been “solved” by the market or rendered obsolete by new technology. But as Smith argued during the Q&A, the moment you pivot to chase the current fad is the exact moment you lock in your relative underperformance.
Julian Robins reinforced this, pointing out that “most investors spend their lives running toward where the puck was, rather than where it is going.”
Smith remains incredibly disciplined here. He is willing to look like a “loser” today because he knows that today’s laggards are often tomorrow’s leaders, provided the underlying business quality remains intact. He knows that “if we keep going like that we will all become poor,” but he also knows that the cure is not to chase the latest high–flyer, but to wait for the inevitable return to the mean.
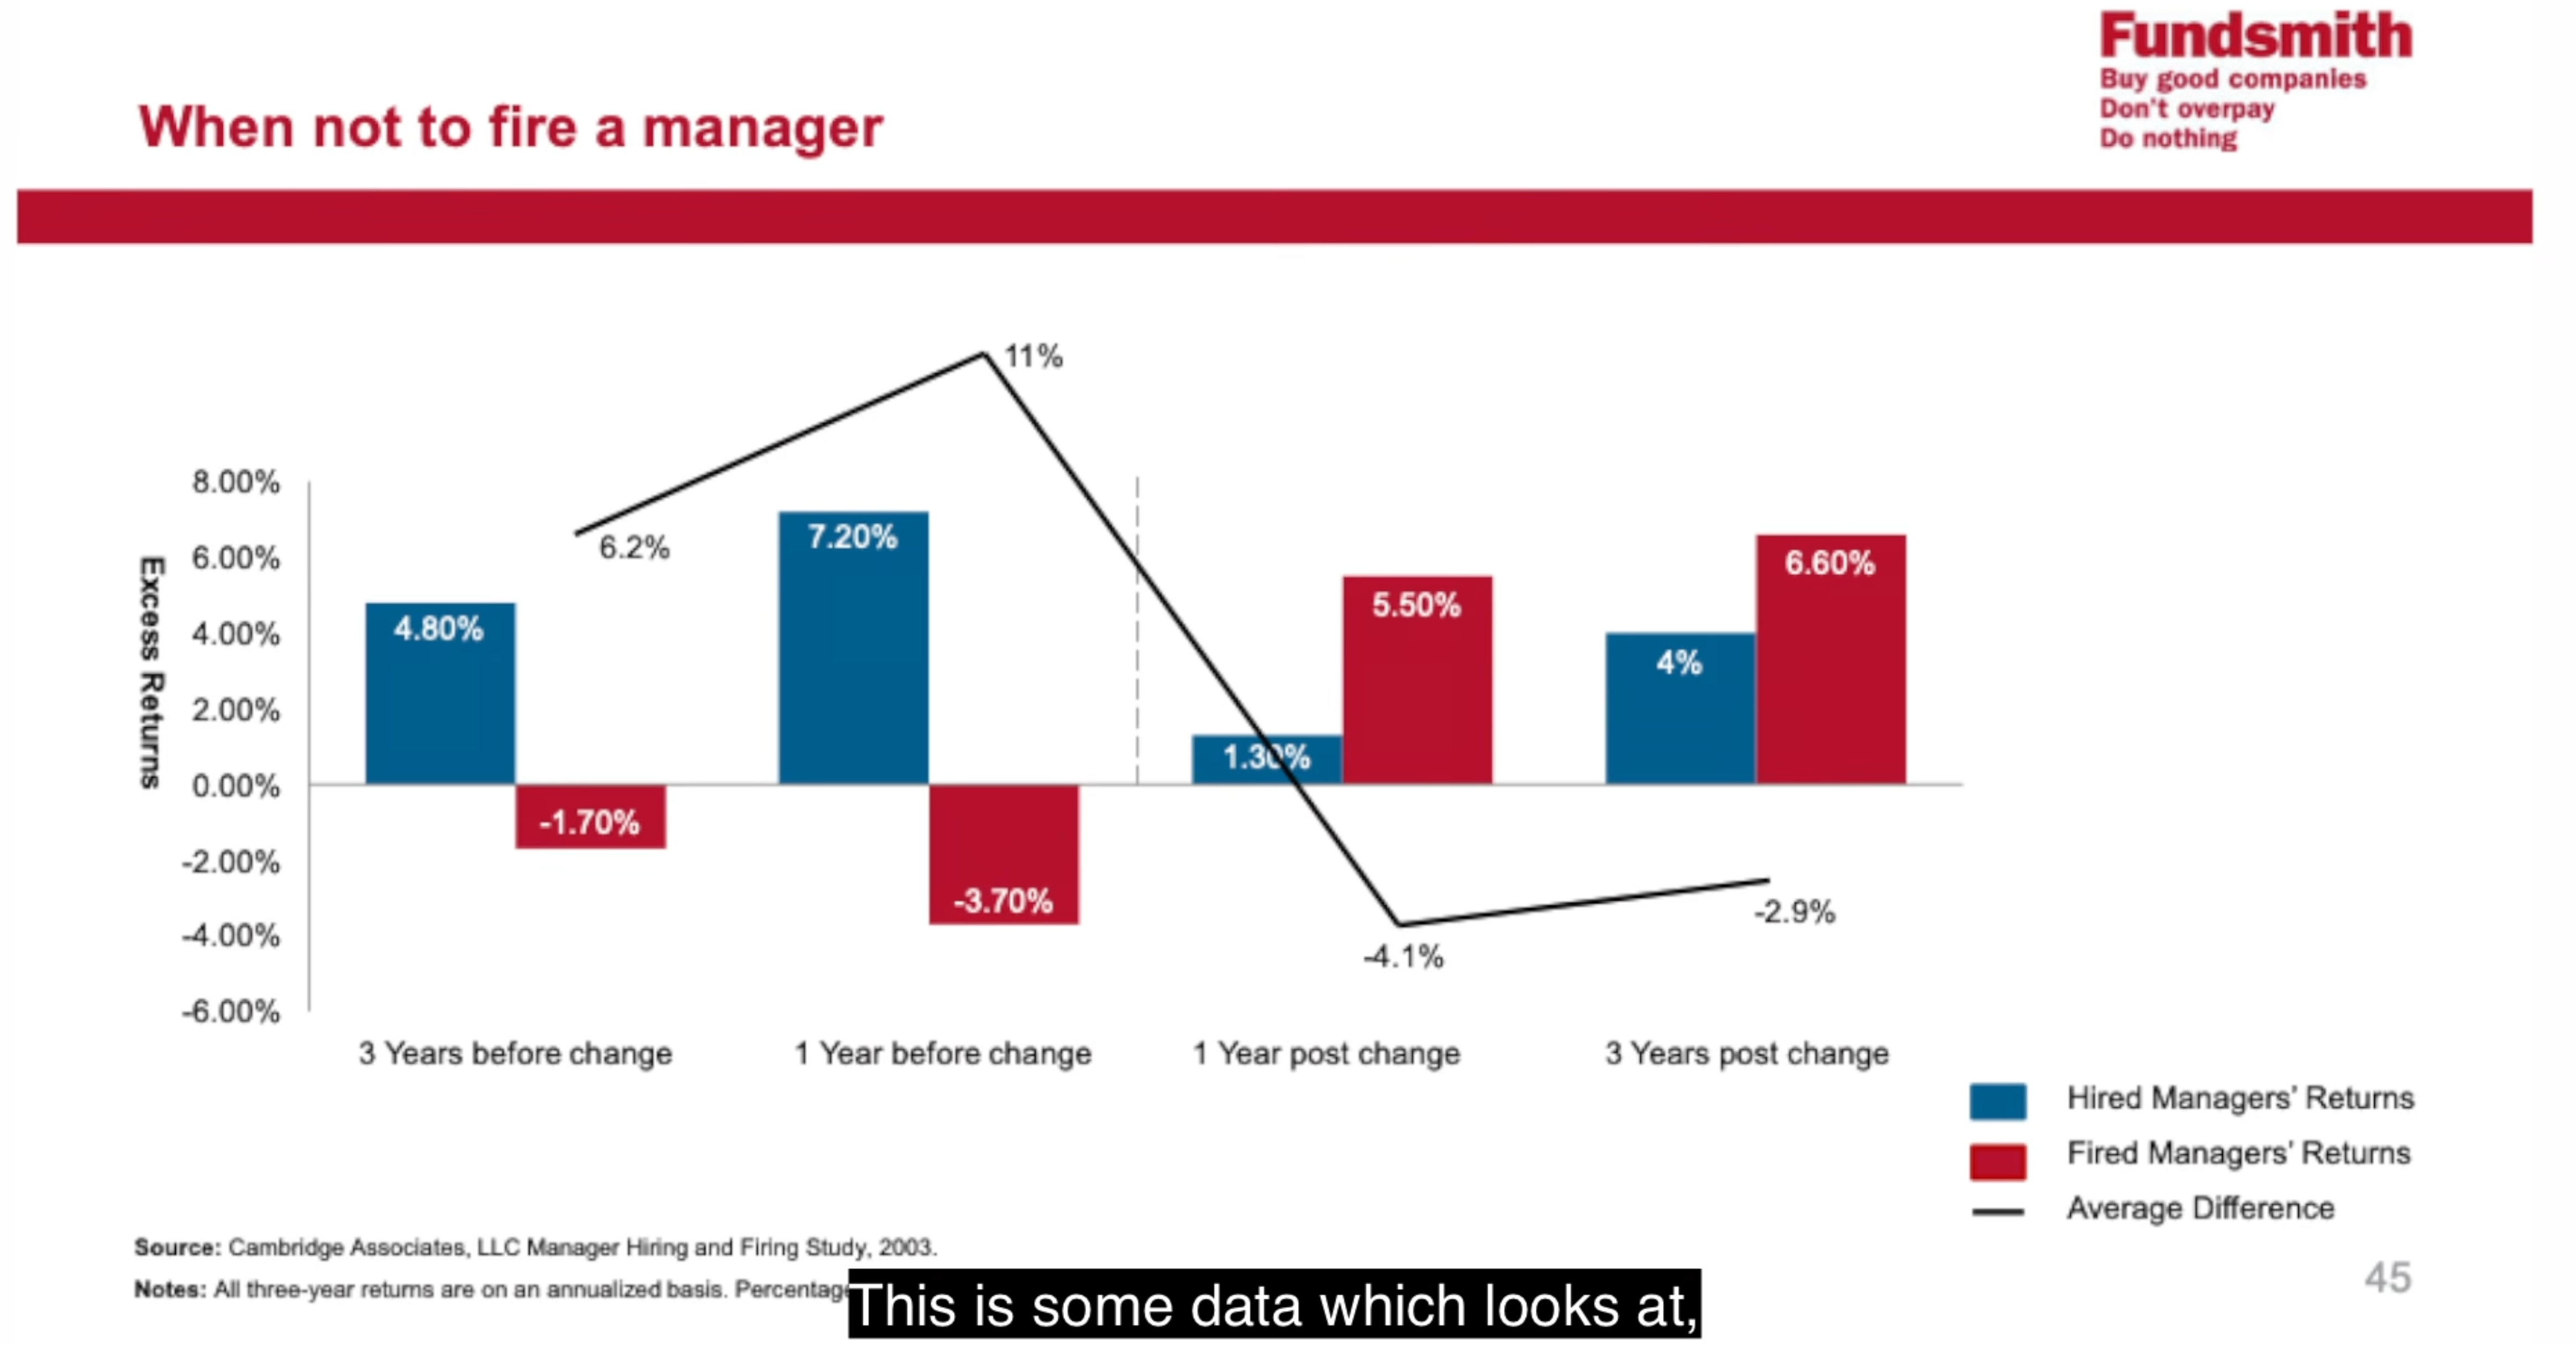
One of the most telling moments was when Terry addressed the “commentariat” and the critics who claim he has lost his touch. He didn’t offer a complicated defense. He simply pointed back to the historical data. He mentioned that “what will determine the outcome... is not what’s happened in the last 12 months but what we do in the next 12 years.” It takes a certain kind of professional arrogance – the good kind – to stand in front of a room of disappointed shareholders and tell them that the best thing they can do is absolutely nothing.
You have to admire the conviction, even if it makes for a boring headline. Most people can’t handle the boredom of a winning strategy when it hits a rough patch. Terry can.
The rest of this post is FREE to read. I only ask that you subscribe, which costs nothing and can be undone with a single click whenever you like.
The wall also helps keep my writing from being freely scraped by AI crawlers, so I hope you understand the small extra step.
In return, you get every deep dive, earnings review, and process piece I publish, straight to your inbox.