

There are just a handful of investors whose interviews I watch the day they come out (investors like Joel Greenblatt, Stanley Druckenmiller, or Peter Lynch come to mind), and Li Lu is near the very top of that list.
He rarely speaks in public, and when he does, he tends to say things that take me some time to fully digest.
His conversation with Tano Santos at the 36th Annual Graham & Dodd luncheon hosted by Columbia Business School (the video went up on October 15) was no exception.
Over roughly an hour, the founder of Himalaya Capital covered the core principles of value investing, the strange psychology of today’s AI-driven market, the state of the Chinese economy, the shifting world order and, in the Q&A, crypto, career risk and how to stay sharp at 60.
A quick word on the man for those who don’t know him (I realize the majority of my readers probably do: Li Lu founded Himalaya Capital in 1997, so next year marks 30 years of the firm. He is one of Columbia’s most distinguished alumni, holding a BA, an MBA and a law degree from the university at the same time. Santos joked about that: why settle for one degree when you can get three? He was Charlie Munger’s long-time partner and friend, he brought BYD to Munger’s and later Berkshire’s attention, and he is widely regarded as one of the most thoughtful practitioners of value investing outside the United States.
What follows is my attempt to walk through the key insights in depth, with plenty of his own words sprinkled in between.
Takeaway #1 – Six ideas that have survived a hundred years
Santos opened by asking Li Lu what he has learned about value investing over three decades and what he wishes he had known at the start.
His answer was a neat distillation of the entire discipline into six principles:
Three come straight from Ben Graham,
one each from Warren Buffett and Charlie Munger,
and the sixth is Li Lu’s own addition.
Graham’s three are familiar to anyone who has read The Intelligent Investor:
A stock is a piece of ownership in a business, so buying a stock is the same as buying a company.
The market exists to serve you and not to instruct you.
And because investing is about predicting a future that is inherently unpredictable, you always need a margin of safety.
What struck me is how he framed the second one. He called it a profound insight “if you are really in the midst of the market activities.” Anyone who has watched a position fall 30% in a week knows exactly what he means.
The idea sounds trivial in a lecture hall. It’s anything but trivial at 9:05 on a Monday morning (Reddit falling 30% last Friday is the latest and most prominent example that comes to my mind).
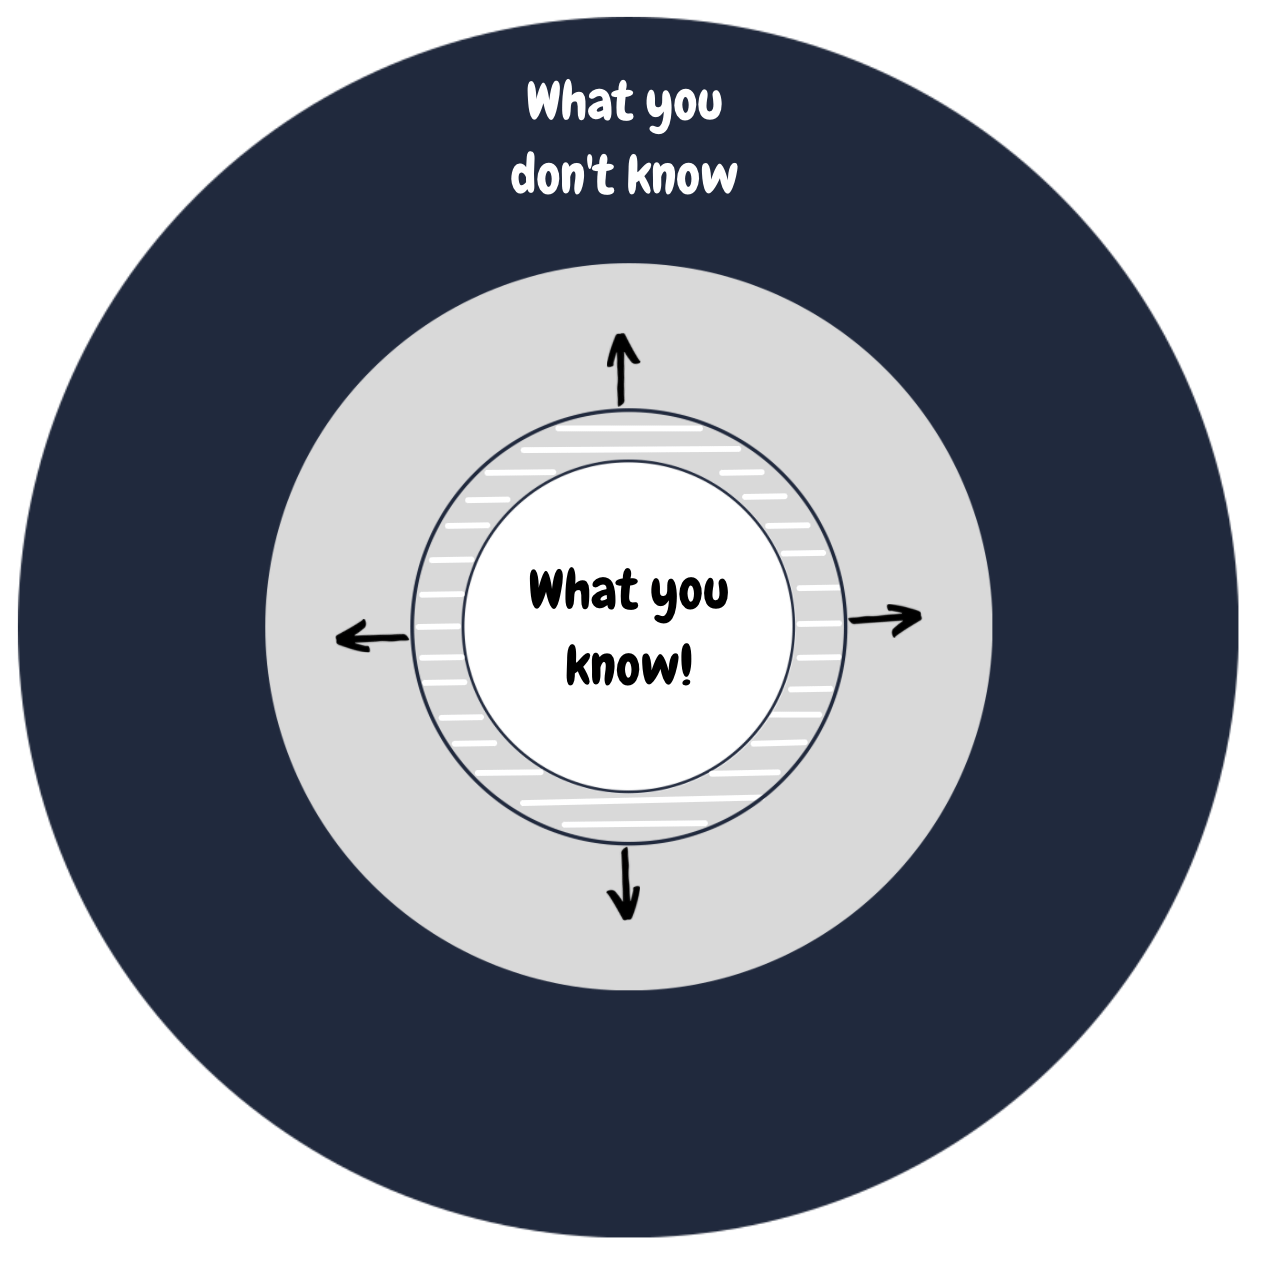
From Buffett comes the “circle of competence principle,” and Li Lu put his emphasis like this – arguably somewhere I think most people overlook:
“The most important concept of a circle of competence is really knowing the edge of it, because most of us really are wired to think a little bit more of ourselves than we actually are. So understanding the edge is as important as understanding what is inside of the edge.”
Personally, and I apologize for adding my own ramblings here, I have always argued that it is critical to respect the edges of your circle of competence, but at the same time, you should remain open-minded about the possibility of widening the edges as you study new businesses and industries, and should not lose that hunger to “grow” your circle of competence.
From Munger, the lifelong fisherman, comes the instruction to fish where the fish are. Some industries, businesses and countries attract enormous attention and therefore competition, which averages out returns. Others attract very few fishermen. Li Lu called this a simple idea that is “amazingly effective” in practice, and given that Himalaya made its name in markets most Western investors ignored for decades, he speaks from experience.
The sixth principle is the one I found most interesting, because it reframes what wealth actually is:
“Wealth in the end is really the percentage ownership of global purchasing power. It isn’t really expressed, especially in the modern economy, in the amount of gold and diamonds or currencies of any kind. With inflation, all of those dissipate over time. What really is important is what you can really buy with it.”
His practical translation of that idea is buying great businesses in the most dynamic economies at advantageous prices, then waiting long enough for value to be created and sharing proportionately in the upside.
Santos picked up on this immediately and noted that keeping an eye on purchasing power may become critical if inflation can’t be controlled amid today’s fiscal challenges. I agree with him. As a German investor, I think about this through the lens of the euro. If your benchmark is your share of what the world produces, a savings account that keeps pace with domestic inflation is still a slow loss of relative wealth whenever the most dynamic parts of the global economy are growing faster than your home market. It’s a quietly radical way to define the goal of investing.
Li Lu’s six core investing principles, condensed:
A stock is a piece of a business (Graham) – buying a share means buying part of a company.
The market is there to serve you, not to instruct you (Graham) – use its prices, don’t take orders from them.
Always demand a margin of safety (Graham) – the future is unpredictable, so protect the downside.
Know the edge of your circle of competence (Buffett) – knowing where your knowledge ends matters as much as what’s inside it.
Fish where the fish are (Munger) – go where competition is thin and attention is scarce.
Wealth is your share of global purchasing power (Li Lu) – own great businesses in dynamic economies and let value compound.
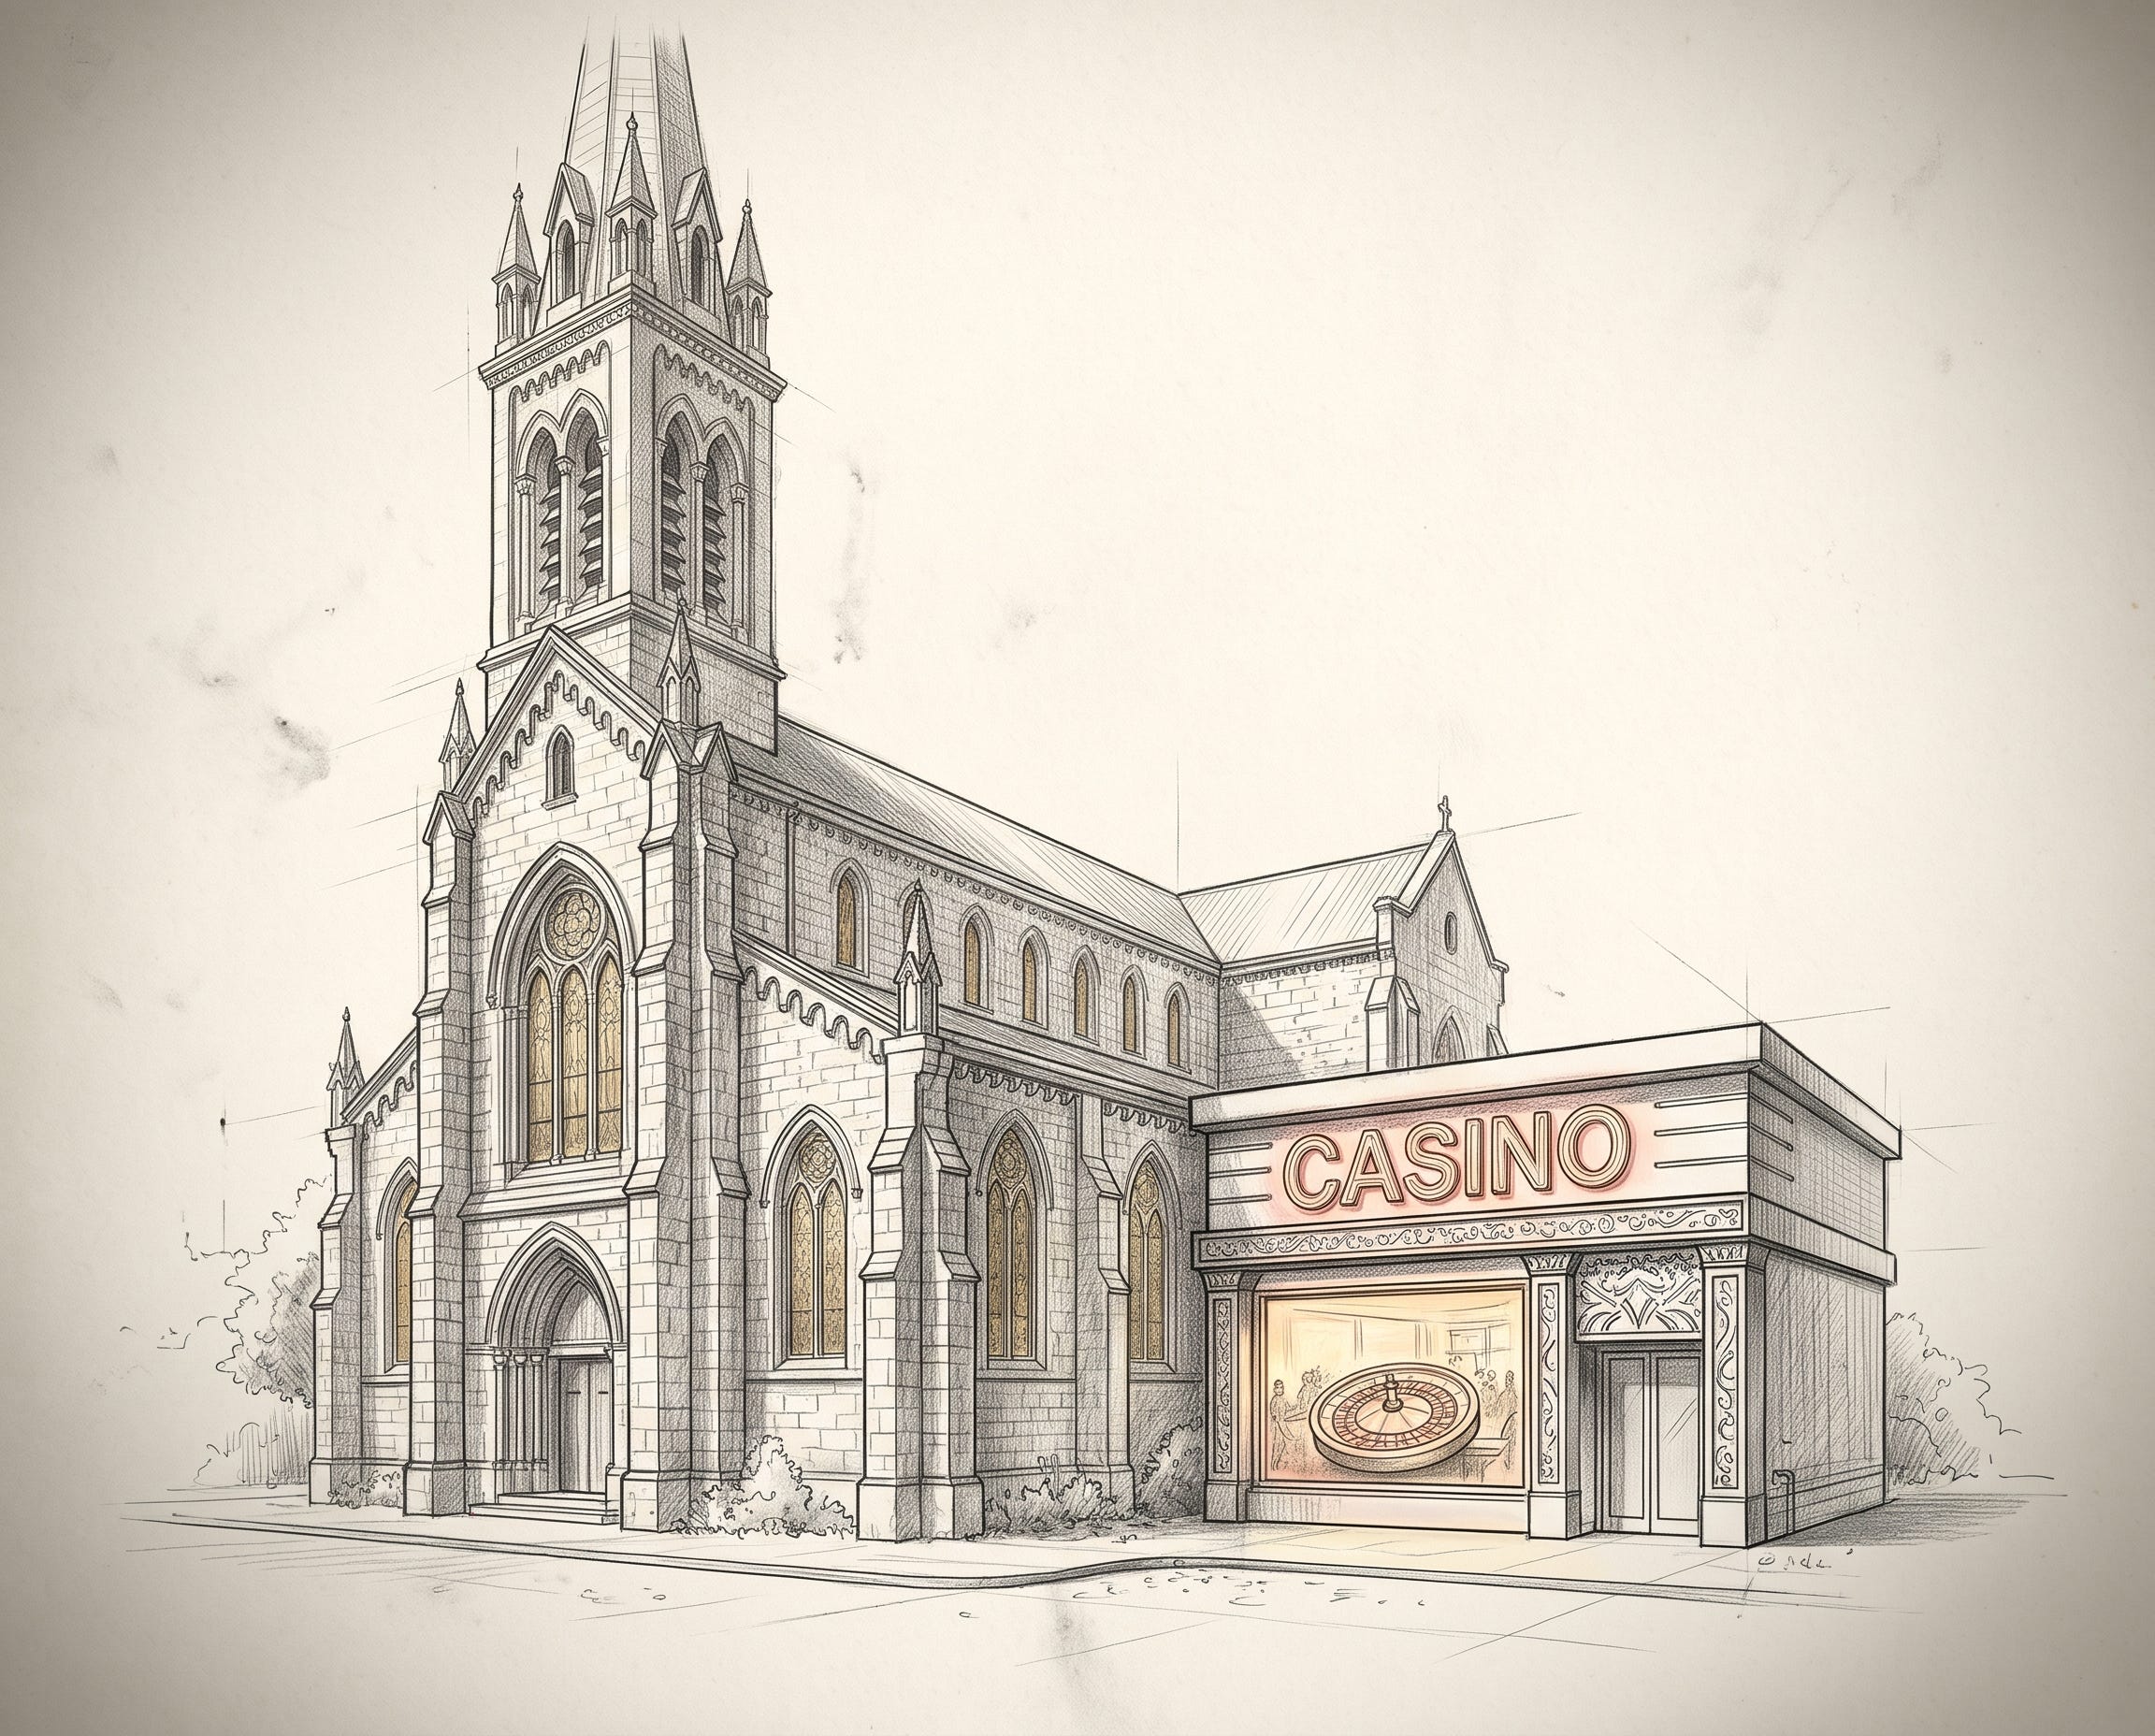
Takeaway #2 – Which game are you playing in the church with a casino attached?
Before getting to AI, Li Lu took a detour that I think is one of the most useful framings in the entire conversation. He divided all market participants into four types:
There are investors who stay with a company over time to benefit from value creation.
There are arbitrageurs who correct mispricings, buying from the pessimist and selling to the optimist in Graham’s terms.
There are speculators, who mostly guess what other people will buy or sell and care neither about the price-to-value gap nor about value creation.
And then there are the brokers and market makers who facilitate all of the above.
In his telling, Graham was primarily an arbitrageur, while Buffett used the arbitrage price to enter but stayed mostly for value creation.
Most people are not purists and carry a bit of all four types in them, which is exactly what an index represents: the average of all participants.
The part that made me pause a little was his assessment of what each group contributes to society: Speculation, by definition, doesn’t stay long enough for any value to be created, so the gains and losses net out to roughly zero. Add the costs of brokerage and market making and you get a net cost to the functioning of the market.
Why does the casino exist at all, then? Li Lu borrowed one of Buffett’s favorite images to answer that:
“Warren always described the stock market as a church with a casino attached to it. The church is where the values are created, and the casino is almost part of the building permit. It’s part of the necessary cost because of the human condition. 400 years ago, when it was created, this is how you really inspired the animal spirits, and 400 years later it is still doing that.”
His point to the students in the room was that this is a personal choice, and one worth making early in a career.
You can play the zero-sum game or the value-creation game.
Society, in turn, has its own choice to make: it should keep the casino from growing so large that it overwhelms the reason the market exists in the first place, which is channeling savings into productive companies that compound economic growth.
He added that it is “pretty miraculous” that this mechanism has survived 400 years of boom, bust, and giant waste and still functions as a core engine of society.
When I read commentary about markets, I find it helpful to ask which of the four participants is speaking. The answer usually explains the time horizon, the language, and the conclusions – remember that a short-seller and a long-only investor who own/short the same stock can both be right at the same time.
And it’s a reminder that you can’t be all four at once, at least not for long.
The rest of this post is FREE to read. I only ask that you subscribe, which costs nothing and can be undone with a single click whenever you like.
The wall also helps keep my writing from being freely scraped by AI crawlers, so I hope you understand the small extra step.
In return, you get every deep dive, earnings review, and process piece I publish, straight to your inbox. Thanks for your support!