

When I pull up a 5-year price chart of Duolingo, it’s hard not to notice how much of the story depends on where you set the starting point. At one end, you see a stock that has returned 107% – a decent run, outperforming the S&P by around 700 bps. But, if you adjust the timeframe by just a few days (see the chart below), the number drops to ~36%. That's the nature of endpoint sensitivity.
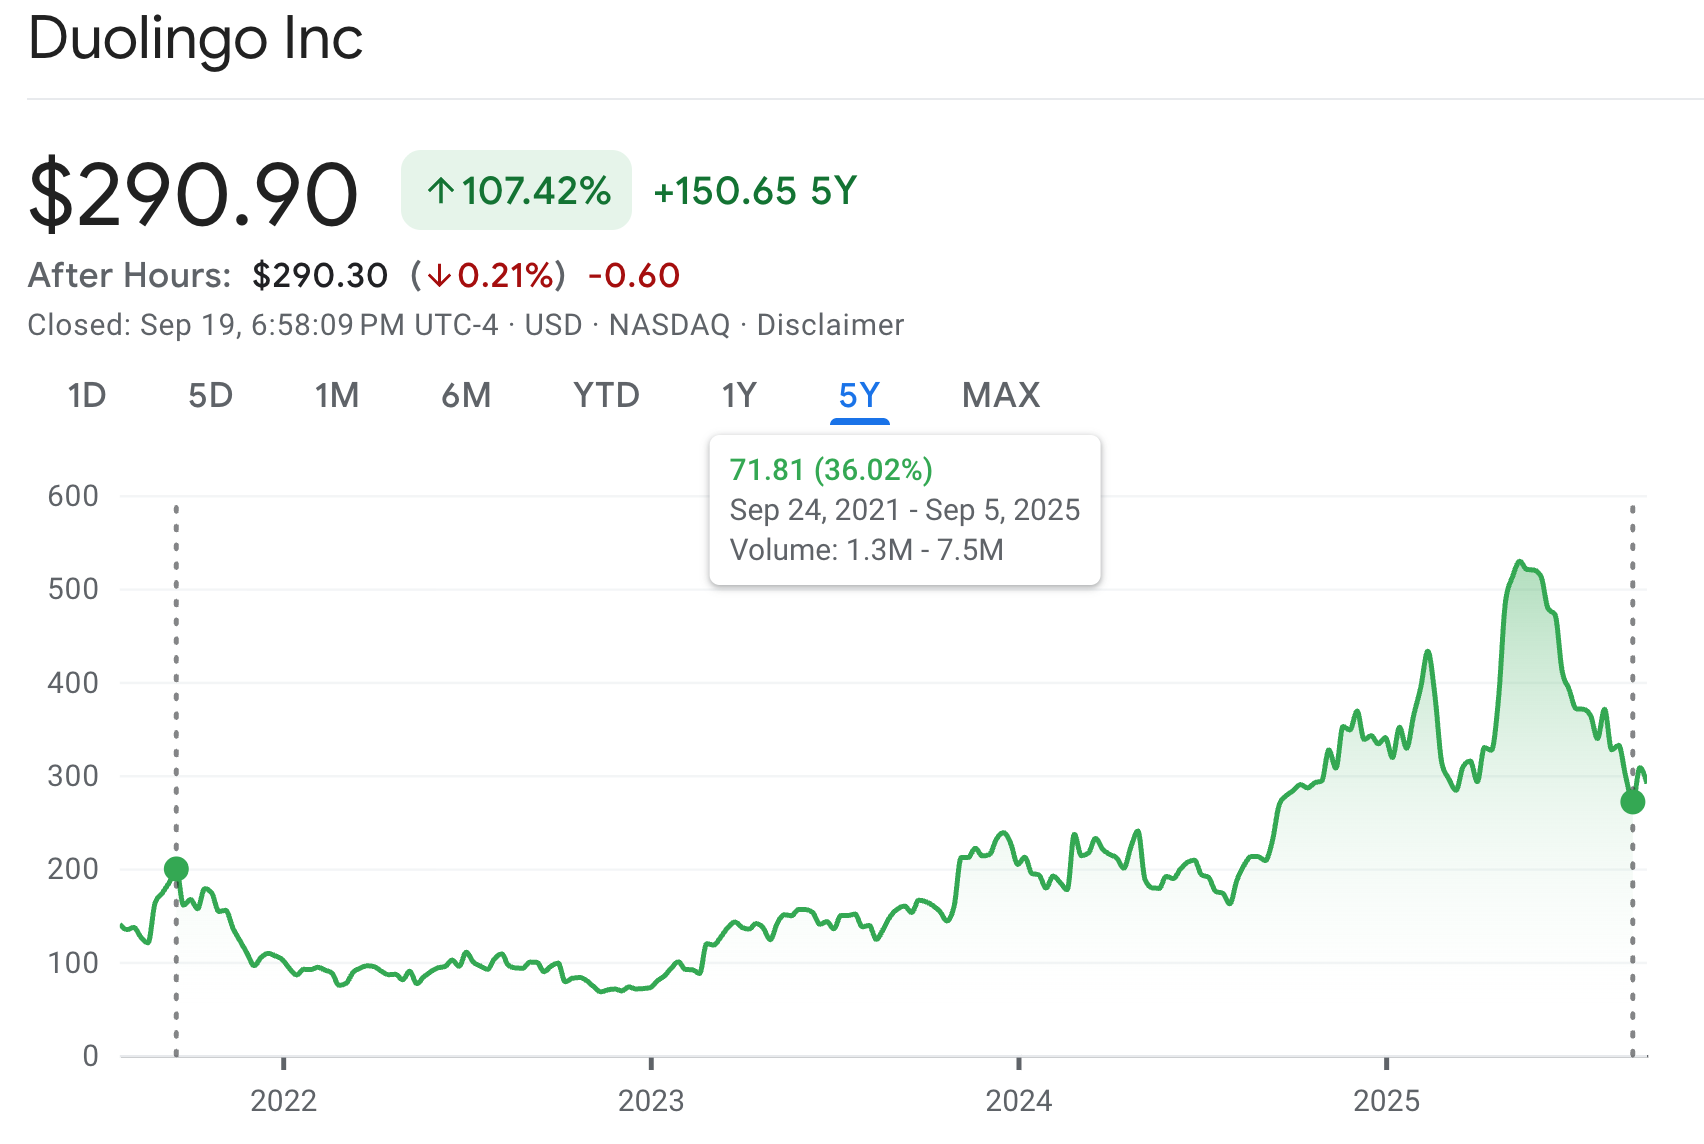
It makes for a great snap sentiment check, because it reminds me how quickly the market’s narrative around a name can swing from “untouchable compounder” (August 2021-May 2025 performance = 277%!) to “overhyped edtech” … and back again.
That’s exactly why Duolingo is back on my radar. By most operating metrics, the business has been firing on all cylinders – DAUs at record highs, revenue growth well into the double digits, free cash flow margins climbing steadily.
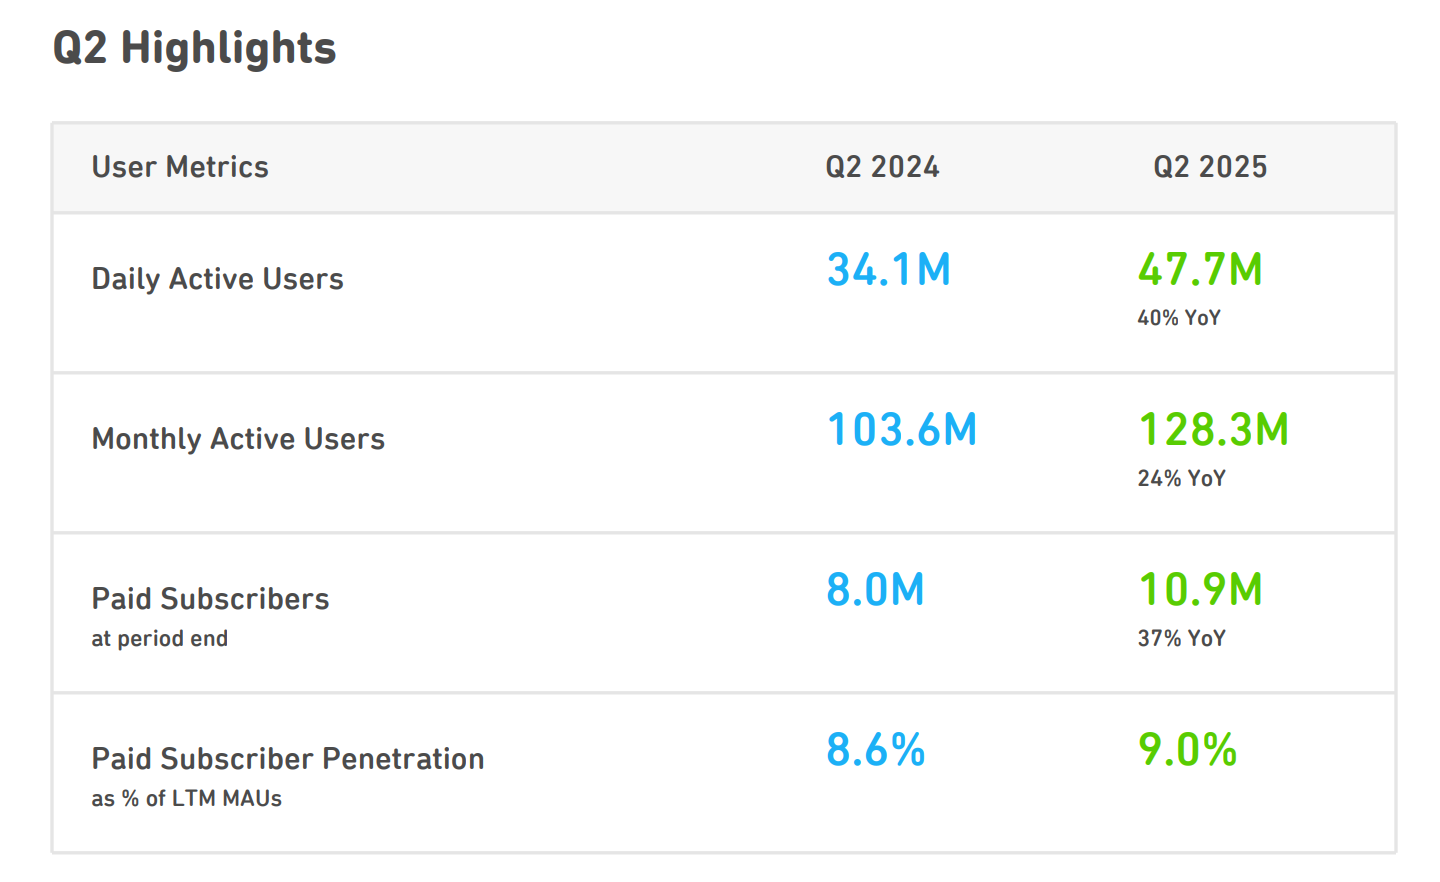
Yet the stock has pulled back meaningfully from its highs. That alone doesn’t make a stock interesting. But when the business and the stock diverge, it usually signals a point where deeper work pays off.
“We believe we’re still early in our user growth journey. We’ve delivered innovation while growing profitability—through strong performance across all subscription tiers, continued investment in our core product, and new subjects that help us increase engagement. We remain focused on building for long-term engagement and growth.” - Luis von Ahn, Co-Founder and CEO of Duolingo
For me, the hook came from Meta Connect 2025. Watching the live demo of their AI-powered translation glasses, I couldn’t help but think about the existential bear case I’ve carried for Duolingo for years: what if the very need to learn another language gets eroded away by technology? That’s not the same as competition – it’s problem shrinkage. If AI makes language barriers melt away in real time, then what happens to a company whose entire existence is tied to helping people cross those barriers the old-fashioned way, through practice and study?
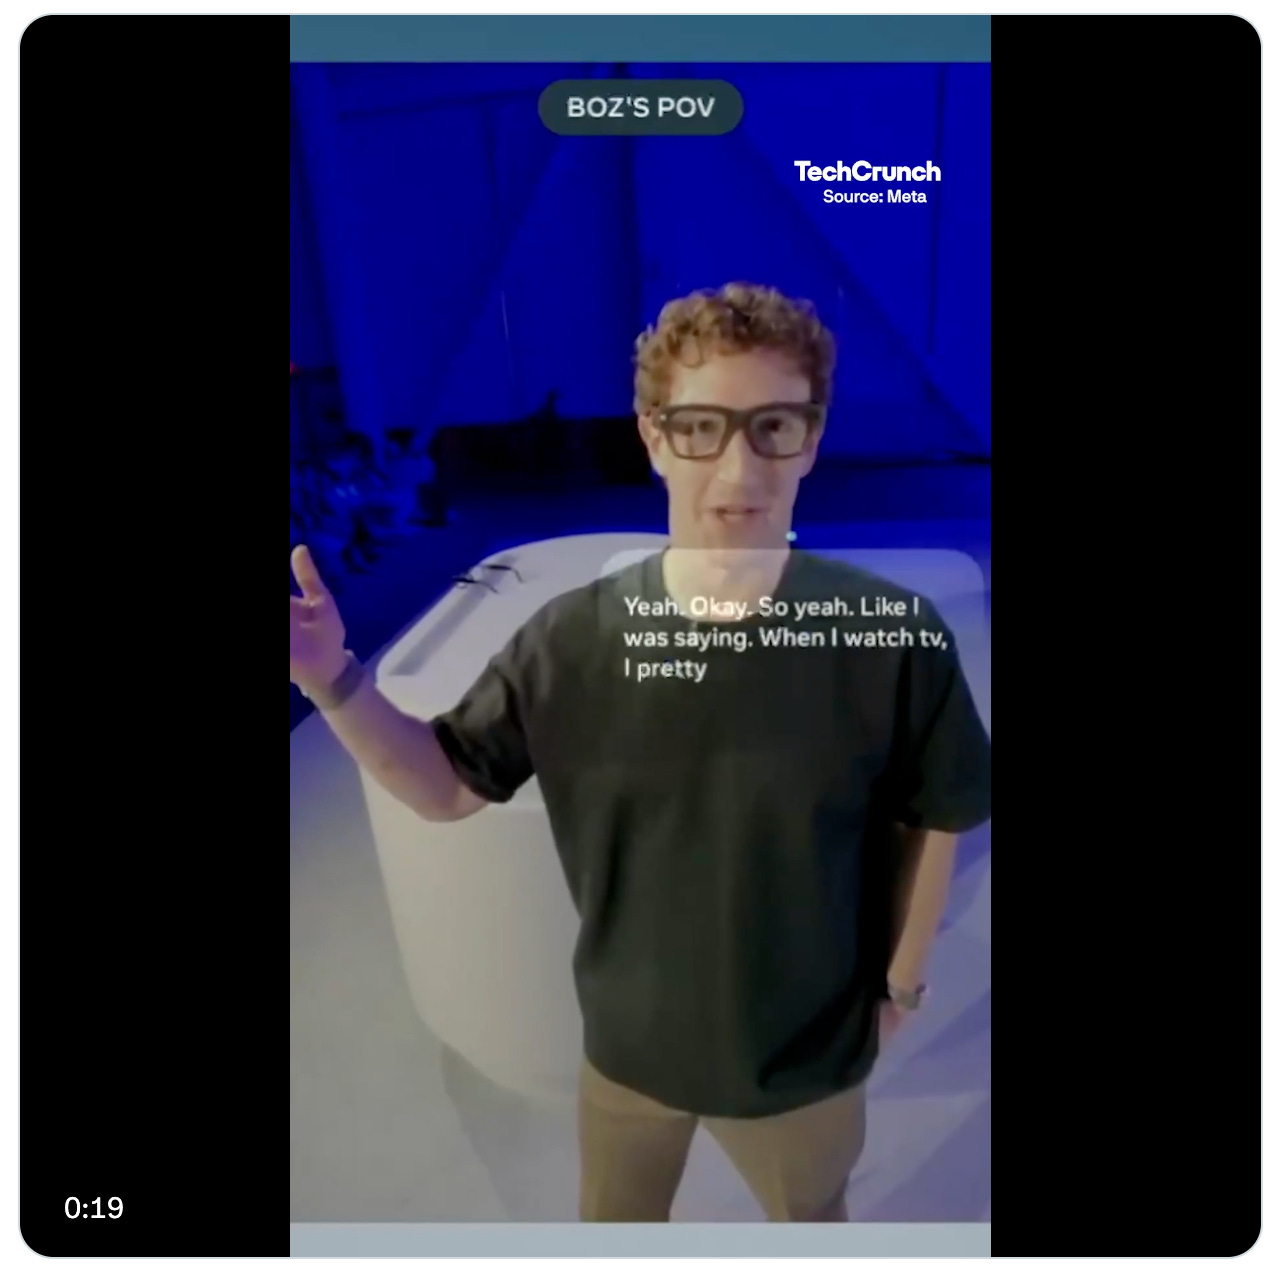
The thing is, the Meta Connect demo didn’t quite deliver on that fear. In fact, it may have pushed the threat timeline further into the future. Which is exactly why now feels like a moment worth re-examining Duolingo. Not to dismiss the bear case – far from it. But to test how durable it really is, what the company has built to defend itself, and whether the valuation makes sense once you frame the disruption risk realistically rather than hypothetically.
That’s the journey I want to take you through in this post: start with the default bearish lens I apply to Duolingo, stress-test the assumptions behind it, dig into what Meta’s latest moves actually mean, and then see how the bullish arguments stack up. Along the way, I’ll look at Duolingo’s brand, its data advantage, its optionality beyond language learning, and finally sketch out a few scenarios for how this could play out.
Paying subscribers get access to the entire post (around 5,500 words) featuring:
My default bearish filter – applying Bill Ackman’s principle of avoiding businesses exposed to uncontrollable extrinsic risks; why language learning feels like a fragile beachhead; parallels to Tesla’s robotaxi pitch and the risk of “problem erosion” rather than competition.
Meta Connect 2025 as a reality check – what Meta actually showed with its translation demo, what the “hiccups” signal Duolingo investors, and how user anecdotes (e.g. Mostly Borrowed Ideas) confirm reliability challenges; why the timeline for disruption likely shifted out.
What true disruption would require – four pillars; plus the human and market frictions of privacy, cost, comfort, and social acceptance.
The case for Duolingo – founder-operator intensity, a brand that has become synonymous with its category, behavior design that engineers habit formation, proprietary data at scale, monetization lanes (subscriptions, ads, English Test, future adjacencies), and why the market may be overestimating disruption.
Proprietary data in an AI world – how Duolingo’s granular learning data could become/remain a moat and a growth engine; potential applications
Scenario analysis – probabilistic timelines for when AR-driven translation could hit mainstream
Before we dive into the analysis …
Paid subscriptions don’t just keep this blog alive – they help me produce the best-possible content I can think of. No ads, no fluff. Just high-quality, independent research for long-term thinkers.
Your support helps me go deeper, write better, and serve smarter investors like you. If you value clarity in a noisy world, subscribe.
PS: Using the app on iOS? Apple doesn’t allow in-app subscriptions without a big fee. To keep things fair and pay a lower subscription price, I recommend just heading to the site in your browser (desktop or mobile) to subscribe.
My Default Bearish Filter – Extrinsic risk and the shrinking-problem thesis
Not too long ago, Duolingo started popping up all over my timeline again. The stock had gone through a major drawdown – more than 40%, and at one point it even touched the –50% mark. The trigger? A wave of AI concerns. That’s when I shared some of my thoughts on why Duolingo doesn’t quite pass my snap judgment filter on X.
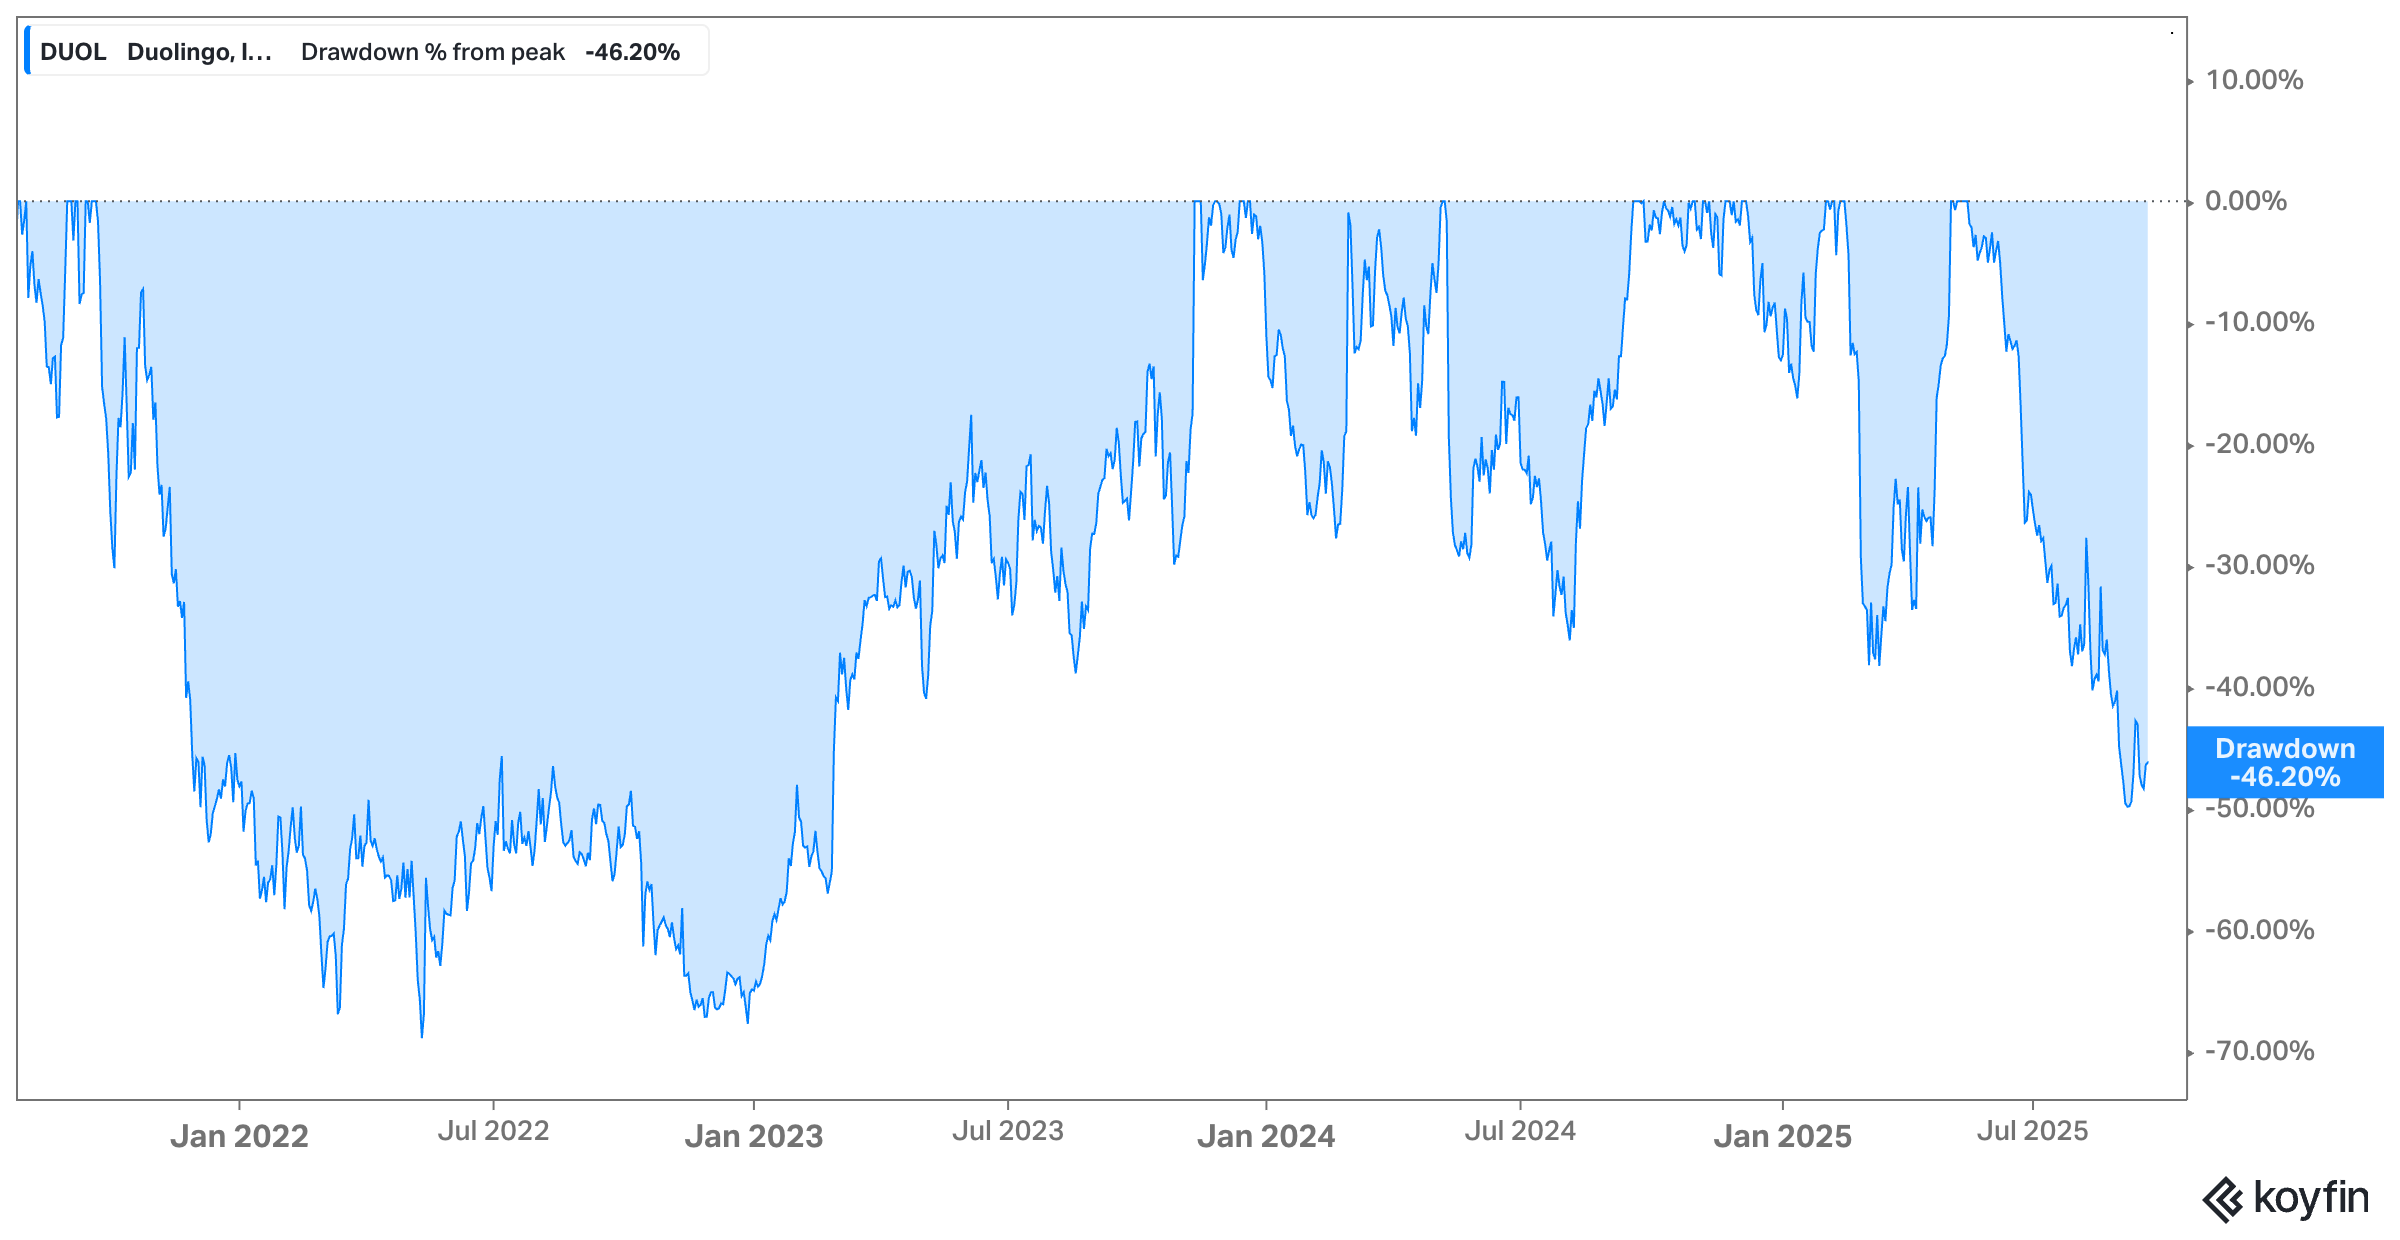
To be fair, the snap-rejection of Duolingio wasn’t based on the exact process I usually apply in my initial snap-judgment screenings. It was more of a gut check rooted in one of Bill Ackman’s principles:
Look for businesses with limited exposure to extrinsic risks outside their control.
That’s the filter I apply almost instinctively now. And Duolingo doesn’t clear it. The probability of the company being completely disrupted isn’t low enough for my liking – in fact, I’d want that probability close to zero.
So that’s not a great starting point.
Here’s why. The bull thesis for DUOL 0.00%↑ often sounds less like a language-learning app story and more like a bet on the company’s ability to design digital experiences that “engineer” the human brain into learning something new. If you view it that way, the pitch starts to resemble the Tesla robotaxi narrative. For Tesla, the transformative promise is autonomous driving – a product that doesn’t yet exist at scale, but that supposedly makes today’s car sales almost irrelevant – that’s been the thesis surrounding Tesla for many years now.
For Duolingo, the parallel would be escaping language learning altogether and reinventing itself as a foundational player in adaptive education. That’s the moonshot upside. But like Tesla’s robotaxi pitch, it’s not proven. It requires a leap in capability, product-market fit, and adoption that no one can guarantee.
The problem is that language learning itself feels like a fragile beachhead to build on. AI, even in its current imperfect state, is already starting to erode the need for traditional language skills by making translation faster, cheaper, and more accessible.
Imagine a world where high-quality translation is so seamless and ubiquitous that you no longer think twice before engaging across languages. In that scenario, the old-fashioned reason to grind away on a language app shrinks dramatically.
Of course, there will always be people who want to learn a language for cultural, emotional, or professional reasons. Language is identity, not just utility.
But if AI becomes an invisible layer that removes language barriers in real time, then the total addressable market for deliberate language learning will be far smaller than the bulls assume – and far smaller than it is today.
So that’s not a problem of competition Duolingo could face. That’s problem erosion. And that distinction should give investors pause.
This is the core tension I see in Duolingo. Its long-term upside depends on escaping the confines of language learning – its current core business – before AI commoditizes it. In other words, it needs to reinvent itself as a more general “learning optimization” platform. Maybe its brand, data, and behavioral design expertise give it a head start. Maybe not. I’m not sure about this. If it succeeds, the future could look radically different from today’s business model.
If it fails, the risk is that it builds an elegant bridge to a destination that fewer and fewer people need to reach.
I should stress here that this was always an outside-in view. I never dug deep into the company when I first formed these thoughts. But the framing stuck with me and made me pass on the idea quickly.
Enter Meta Connect 2025 …
Meta Connect 2025 – A reality check on live translation and timelines
I went into Meta Connect with the same nagging thought I laid out earlier: if live translation becomes good enough, cheap enough, and ubiquitous enough, the rationale for learning a language on purpose starts to wobble.
So I watched the keynote specifically through that lens. What I saw didn’t eliminate the long-run threat – but it did push my disruption timeline to the right. The gap between “captioned assistance” and “frictionless, expressive two-way translation in the wild” is still meaningful. That buys time, and time matters a lot for a company like Duolingo.
First, the keynote stumbled. More than once. The flagship Ray-Ban Display demo misfired on stage, with Meta’s team initially blaming Wi-Fi before subsequent coverage clarified the failures weren’t simply connectivity gremlins. The neural wristband interaction that was meant to answer a live video call didn’t trigger as expected, and several on-stage flows felt brittle rather than inevitable. Meta’s CTO later called them “demo failures” rather than “product failures,” which is fair – but for our purposes as investors, the signal is that even controlled conditions weren’t smooth. That tempers expectations about how robust this will feel out in the messy real world.
Second, what worked most reliably on stage – and in Meta’s polished promos – is better described as “live captions” with select translation rather than fully symmetric, natural, real-time interpretation.
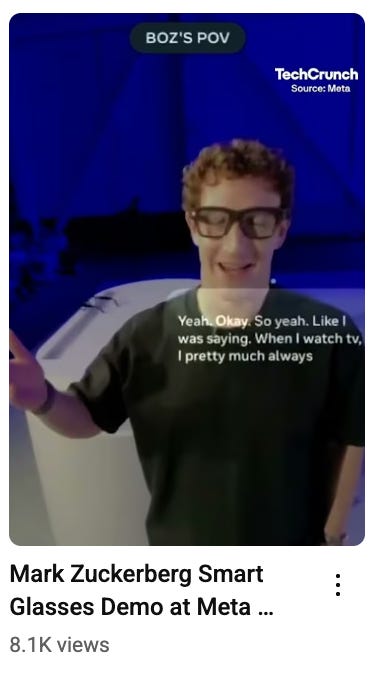
The product page and launch blog lean into “live captioning” and “translate select languages in real time,” with current help-center materials listing English, Spanish, French, and Italian. That’s useful. It’s not yet a Star Trek universal translator. The lived experience looks like text appearing in your lens – think subtitles for speech directed at you – rather than an ambient layer that seamlessly handles nuance, tone, and timing across any environment – comparing Meta Connect 2025 to 2024 felt like a step backwards.
Now, none of this means the device isn’t impressive. Reviewers who got brief hands-on time came away intrigued by the display, and Meta’s ambition is obvious: put an always-there assistant on your face and give it a control surface via an EMG wristband. But ambition isn’t adoption. The price point for the display model is fair, but the value prop hinges on AI that still feels hit-or-miss in daily use, and even Meta-friendly observers called out the keynote hiccups.
My read is that Meta is inching toward the right product thesis, yet the delta between keynotes and day-to-day reliability remains non-trivial. That delta is your timeline buffer if you’re underwriting Duolingo.
Mostly Borrowed Ideas shared his perspective in his faily newsletter, and I think it is helpful here because it comes from a heavy daily user of Meta’s glasses – which I am not. He’s bullish on the form factor for music, calls, and capturing moments – and he’s candid that, so far, the AI layer has been hit or miss. He specifically called out that the live demo failures resembled the inconsistencies he has experienced too. Importantly, he still thought the “live subtitle” demo was cool and potentially life-changing for travel once it matures. That combo – practical enthusiasm with grounded skepticism – is exactly how I’m framing the opportunity myself. It’s not that real-time translation won’t get good. It’s that getting to “good enough for everyone, everywhere” takes more years of engineering and iteration than headline clips imply.
There’s also the human layer that rarely fits in a spec sheet. You’re asking people to wear cameras and displays on their faces in social spaces – cafés, classrooms, trains. Privacy norms, signage translation in sensitive contexts, and bystander discomfort all slow diffusion. Even with brighter LED indicators, watchdogs argue trust hasn’t been solved. Social acceptability is a stubborn adoption gate. If that gate stays half-closed, usage concentrates in travel and niche workflows rather than becoming an all-day, every-interaction utility that truly erases the need to learn. That again stretches the timeline.
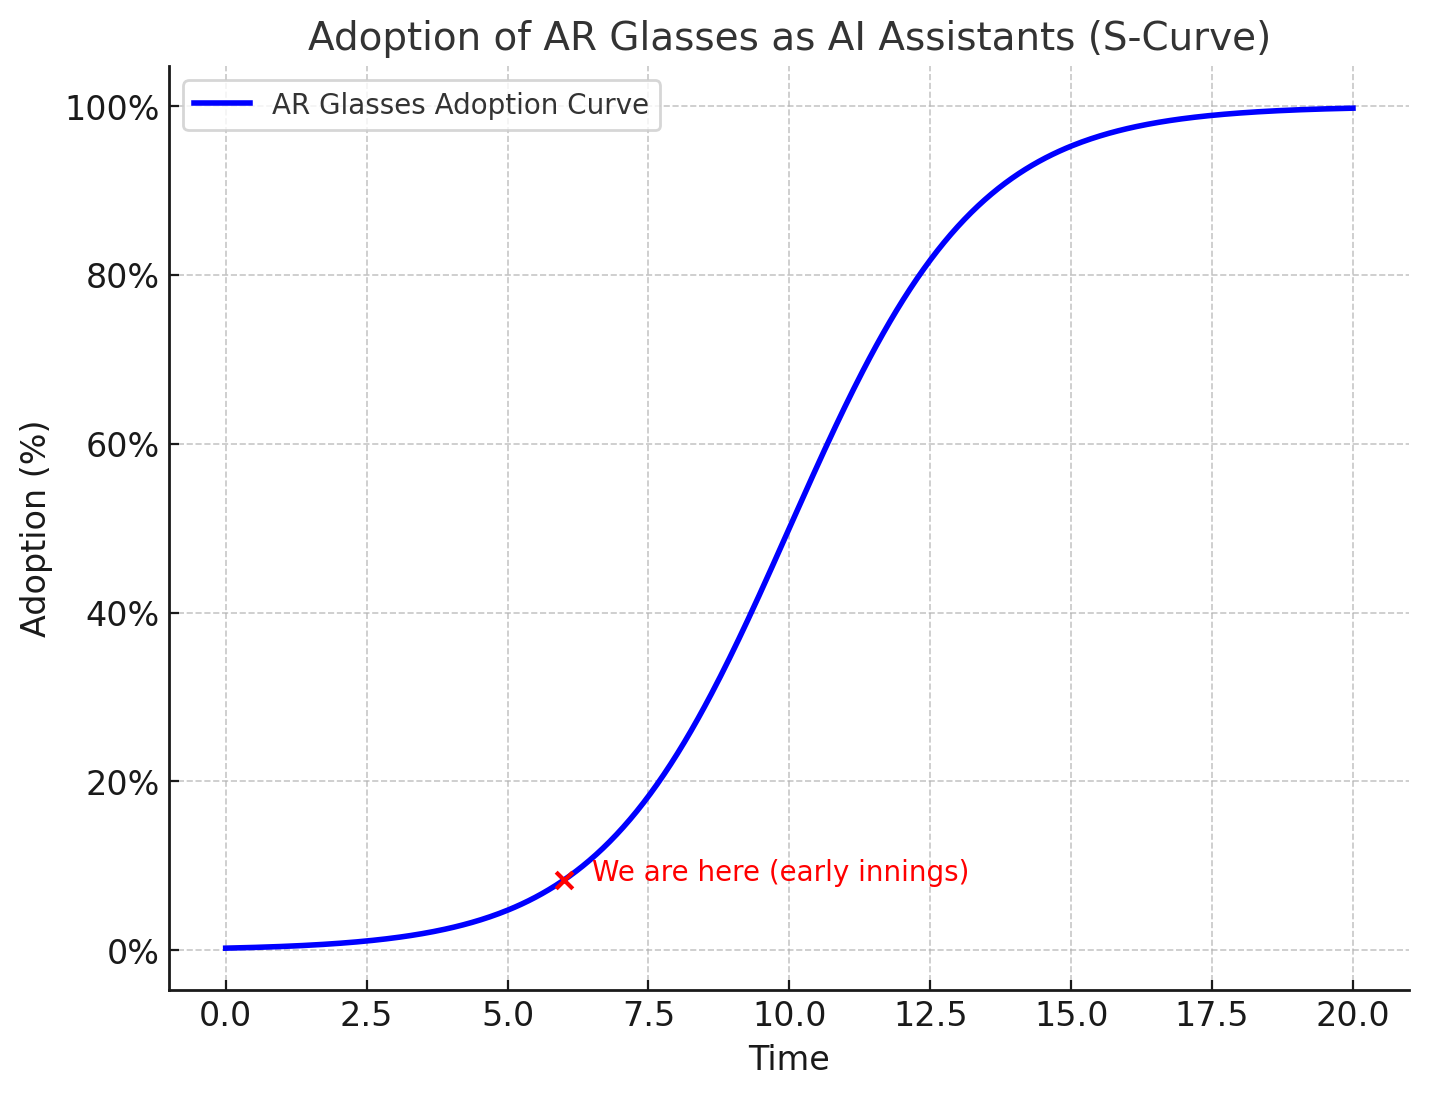
Put differently: Meta showed some progress toward captioned assistance on glasses; it did not show that expressive, low-latency, environment-robust translation is here for mainstream, high-stakes interactions.
There’s a ladder to climb – device comfort and battery life, microphone arrays that cope with wind and din, models that preserve intent and affect, UX that recovers gracefully when things go wrong.
You can feel the direction of travel. You can also feel how many failure modes remain before you’d trust this in, say, a job interview or a medical appointment, which is the kind of bar that makes language learning obsolete for broad swaths of the population.
For Duolingo, that nuance is of course relevant. If the threat were imminent, you’d demand a steep discount to any growth multiple – and Duolingo’s multiples seem quite demanding.
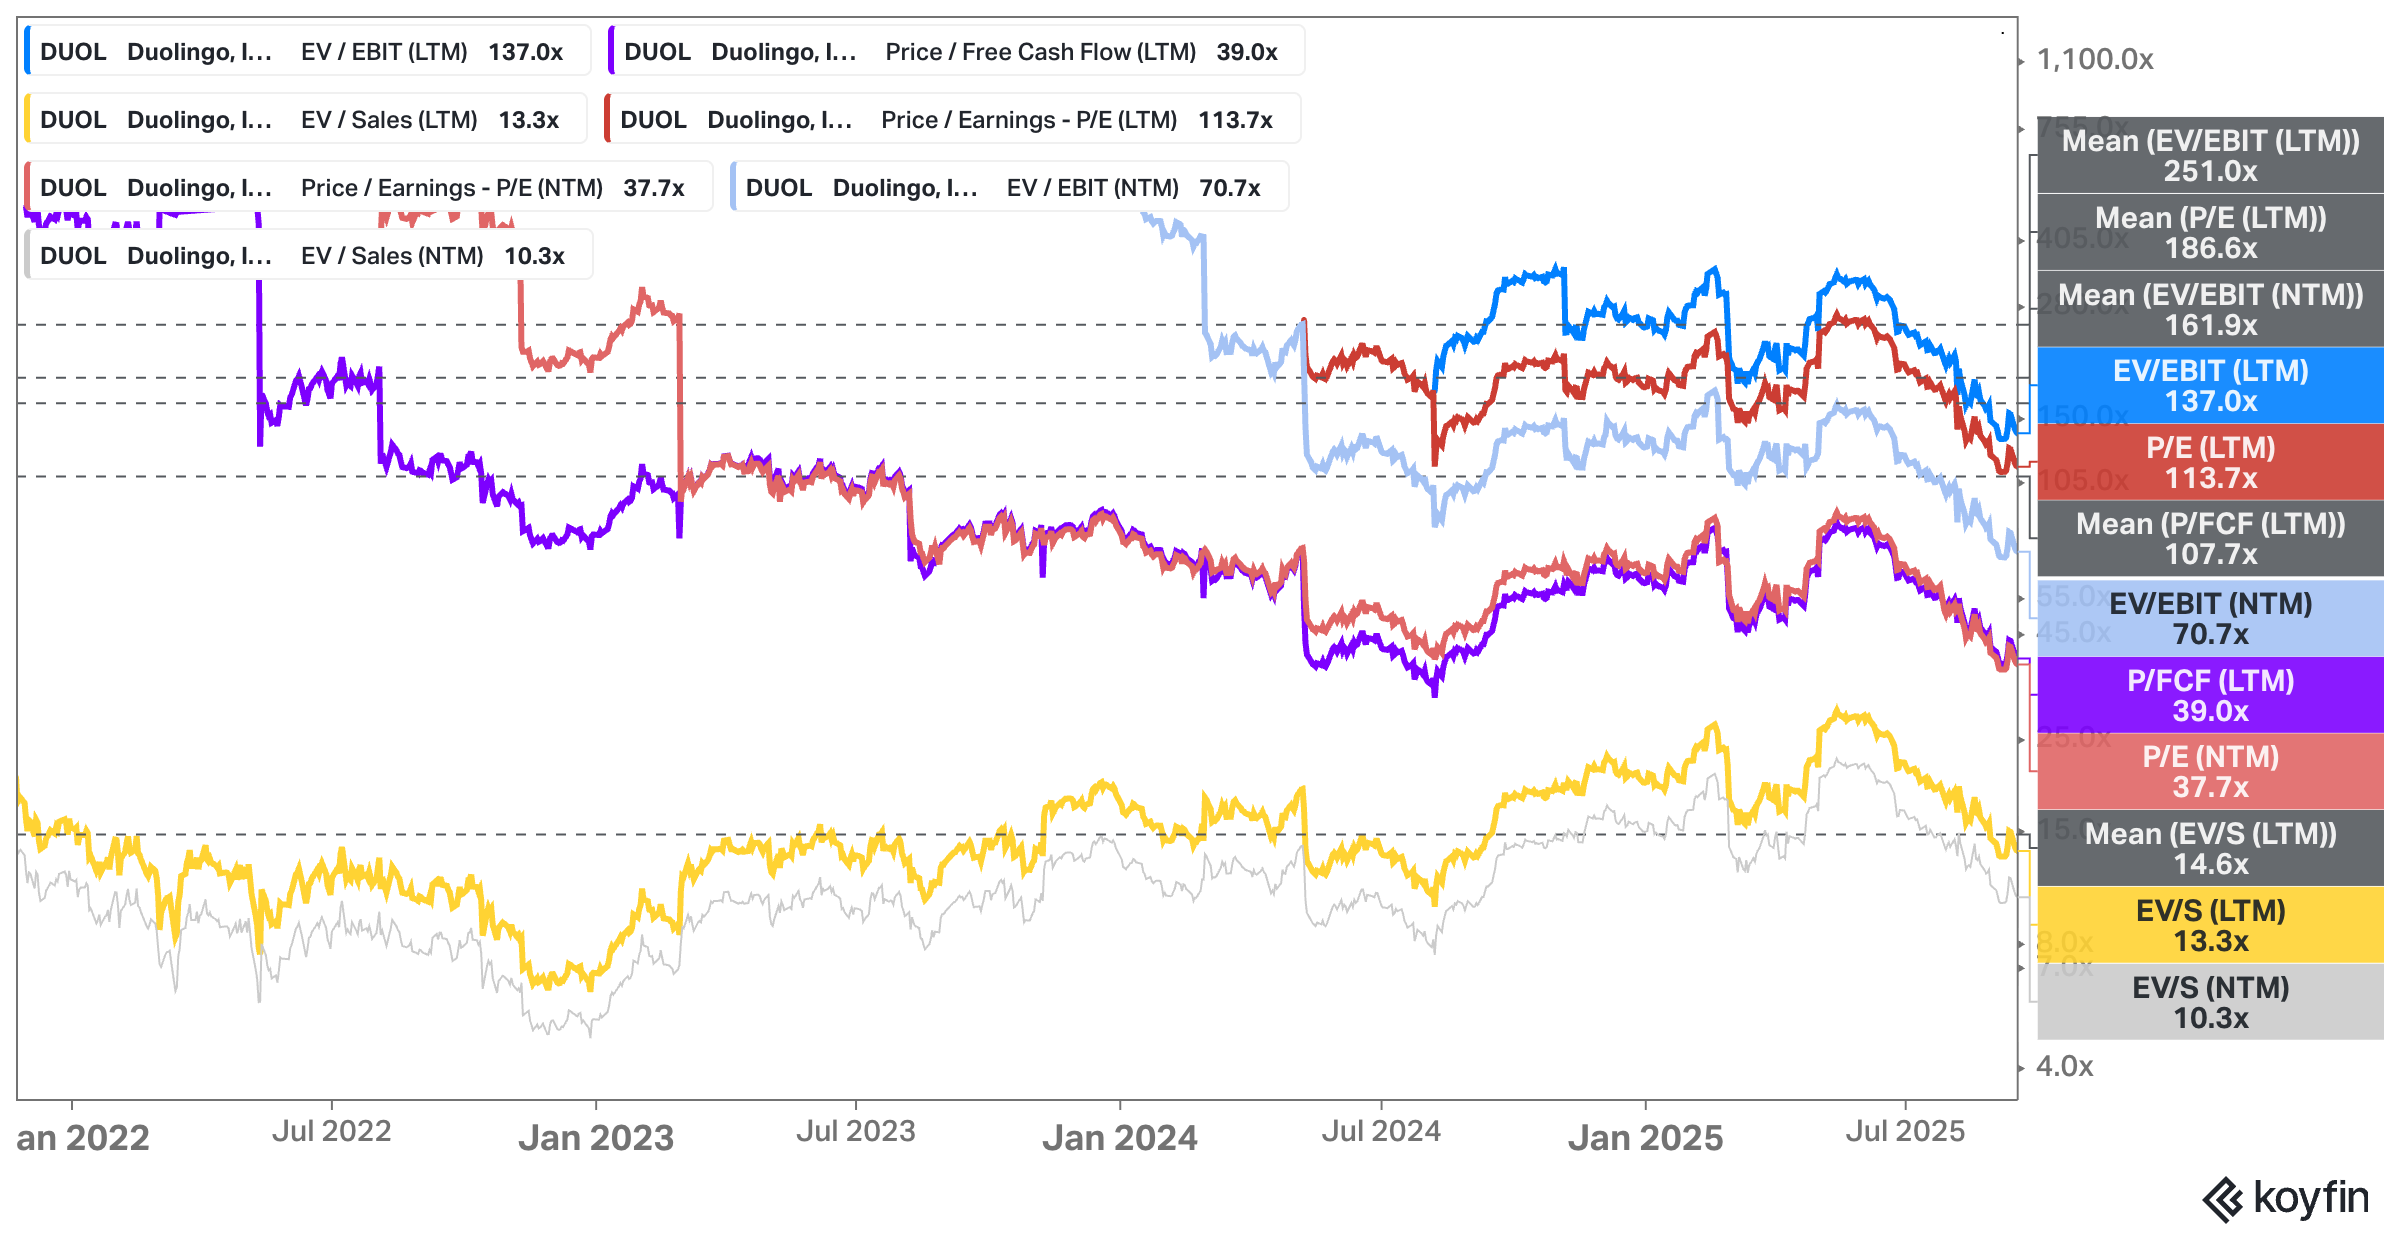
If however the threat is material but years out – and gated by hardware adoption, social norms, and ML reliability – you have room to ask a different question: how much time does Duolingo have to deepen its moat, diversify its earnings mix, and repurpose its data and product DNA into adjacent learning domains?
That’s where the analysis heads next.
If you’re following my logic, Meta Connect didn’t invalidate the bear frame I opened with. It reframed it. Live translation still looks inevitable in some form. The keynote suggested it won’t be uniformly reliable, socially frictionless, and widely adopted as an all-day utility in the near term. That pushes my disruption clock out a few ticks – enough to reassess Duolingo’s next moves rather than writing a eulogy in advance.
The rest of this post is FREE to read. I only ask that you subscribe, which costs nothing and can be undone with a single click whenever you like.
The wall also helps keep my writing from being freely scraped by AI crawlers, so I hope you understand the small extra step.
In return, you get every deep dive, earnings review, and process piece I publish, straight to your inbox.