

Interactive Brokers has been in my portfolio for close to three years now if I recall correctly, and in all that time I have never dedicated a post to it (to be fair, I only started writing on this blog around two years ago).
Strictly speaking, I discussed it in “Not All Reinvestment Is the Same: How Two Companies Reinvented Growth Strategies“
Given how much ink I spill on far smaller positions and names that don’t make it into my portfolio, that may strike you as odd.
The explanation has little to do with the company itself, and a lot to do with the kind of attention it asks of me as a shareholder. Or rather, the attention it doesn’t ask for.
When drafting this post (it’s not my typical deep dive, following my typical structure, but I believe it covers the thesis quite nicely nonetheless), I remember a distinction I drew in a post last year. More specifically, in an update on Wise back in mid-2025, I drew a line between two types of holdings:
“Every portfolio has its needy stocks – the ones that seem to require constant attention, where each earnings call might reveal a twist or signal a derailment. You watch them closely, read between the lines, scrutinize segment margins, and debate strategy with yourself. They’re not necessarily bad businesses, but they often come with more moving parts, more competitive risk, or more volatility in execution (which may have led to an attractive valuation in the first place).
Then there’s the other bucket: the ones you don’t have to babysit. You check in, not out of fear something’s gone wrong, but out of habit and discipline. These companies quietly go about compounding intrinsic value. Wise fits squarely into this category. I still read the full report. I still think critically about what might break the thesis. But the exercise is different. I’m not looking for a story to unravel – I’m tracking the same handful of long-term KPIs I’ve been following for months or sometimes years. And each time I check, I’m reminded why it’s in the portfolio.”
Funnily enough, Wise has since switched buckets. Between the stablecoin debate, mounting regulatory scrutiny, and the denial of its U.S. national trust bank charter, it has run into an almost perfect storm of headwinds that currently dominates the narrative, and I suspect it is clouding a lot of investors’ judgment.
That’s a topic for my next post, which I have planned already. Today, however, belongs to IBKR, which has always been my textbook example of the second bucket.
A few days ago, while reflecting on my first decade as an investor, I tweeted the following:
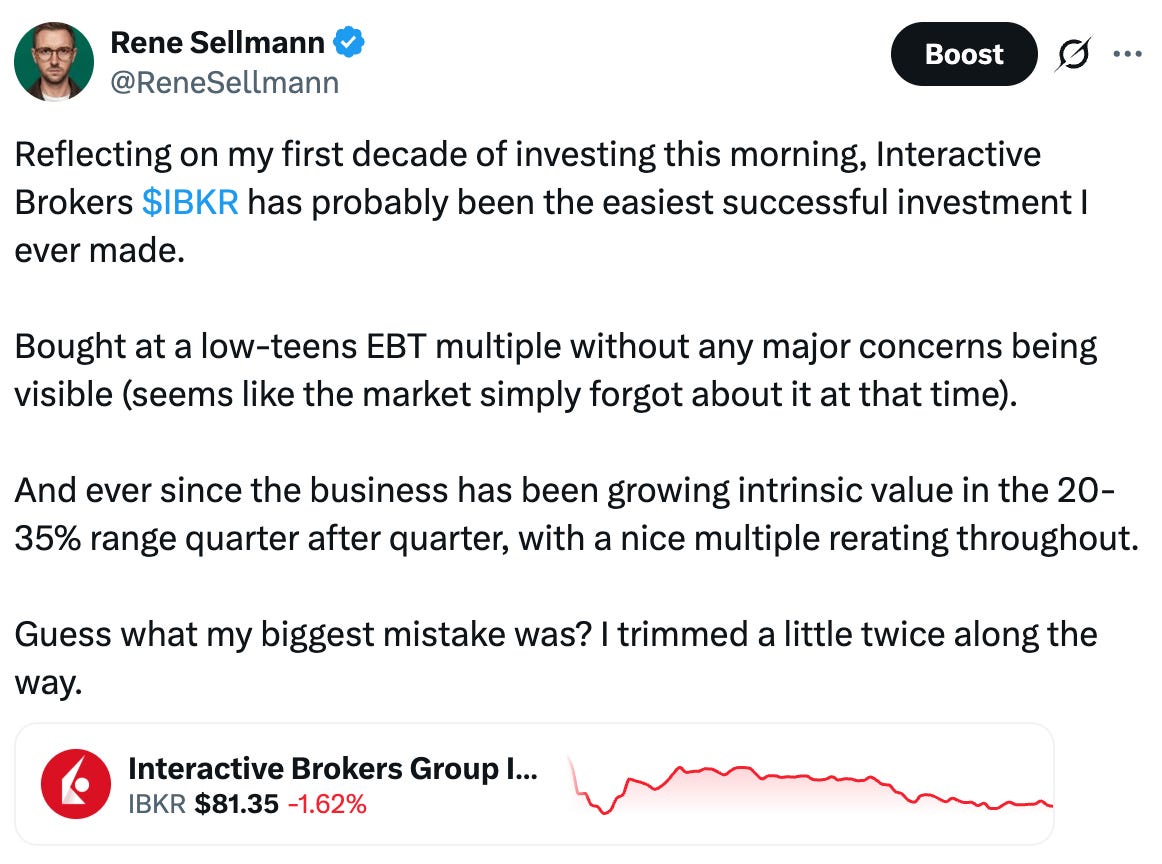
I meant every word of it. If anything, the business has outrun the expectations I had when I first bought it. Number of accounts, client equity, margin balances, and pretax earnings have all compounded faster than my base case, and the move from a low-teens to a now mid-20s EBT multiple (and higher at the recent peak) came on top of that.
My own contribution was mostly limited to getting in the way twice. Lesson noted.
So why write about it now? I still believe there isn’t a great deal to say about IBKR in any given quarter, and that’s precisely what makes it such a pleasant holding. But the third quarter was a little different. For the first time in a while, a few numbers softened, and trading activity cooled noticeably. The market noticed too. IBKR’s stock is now down close to 17% from its previous high, uncomfortably close to the 20% drawdown that technically marks bear market territory.
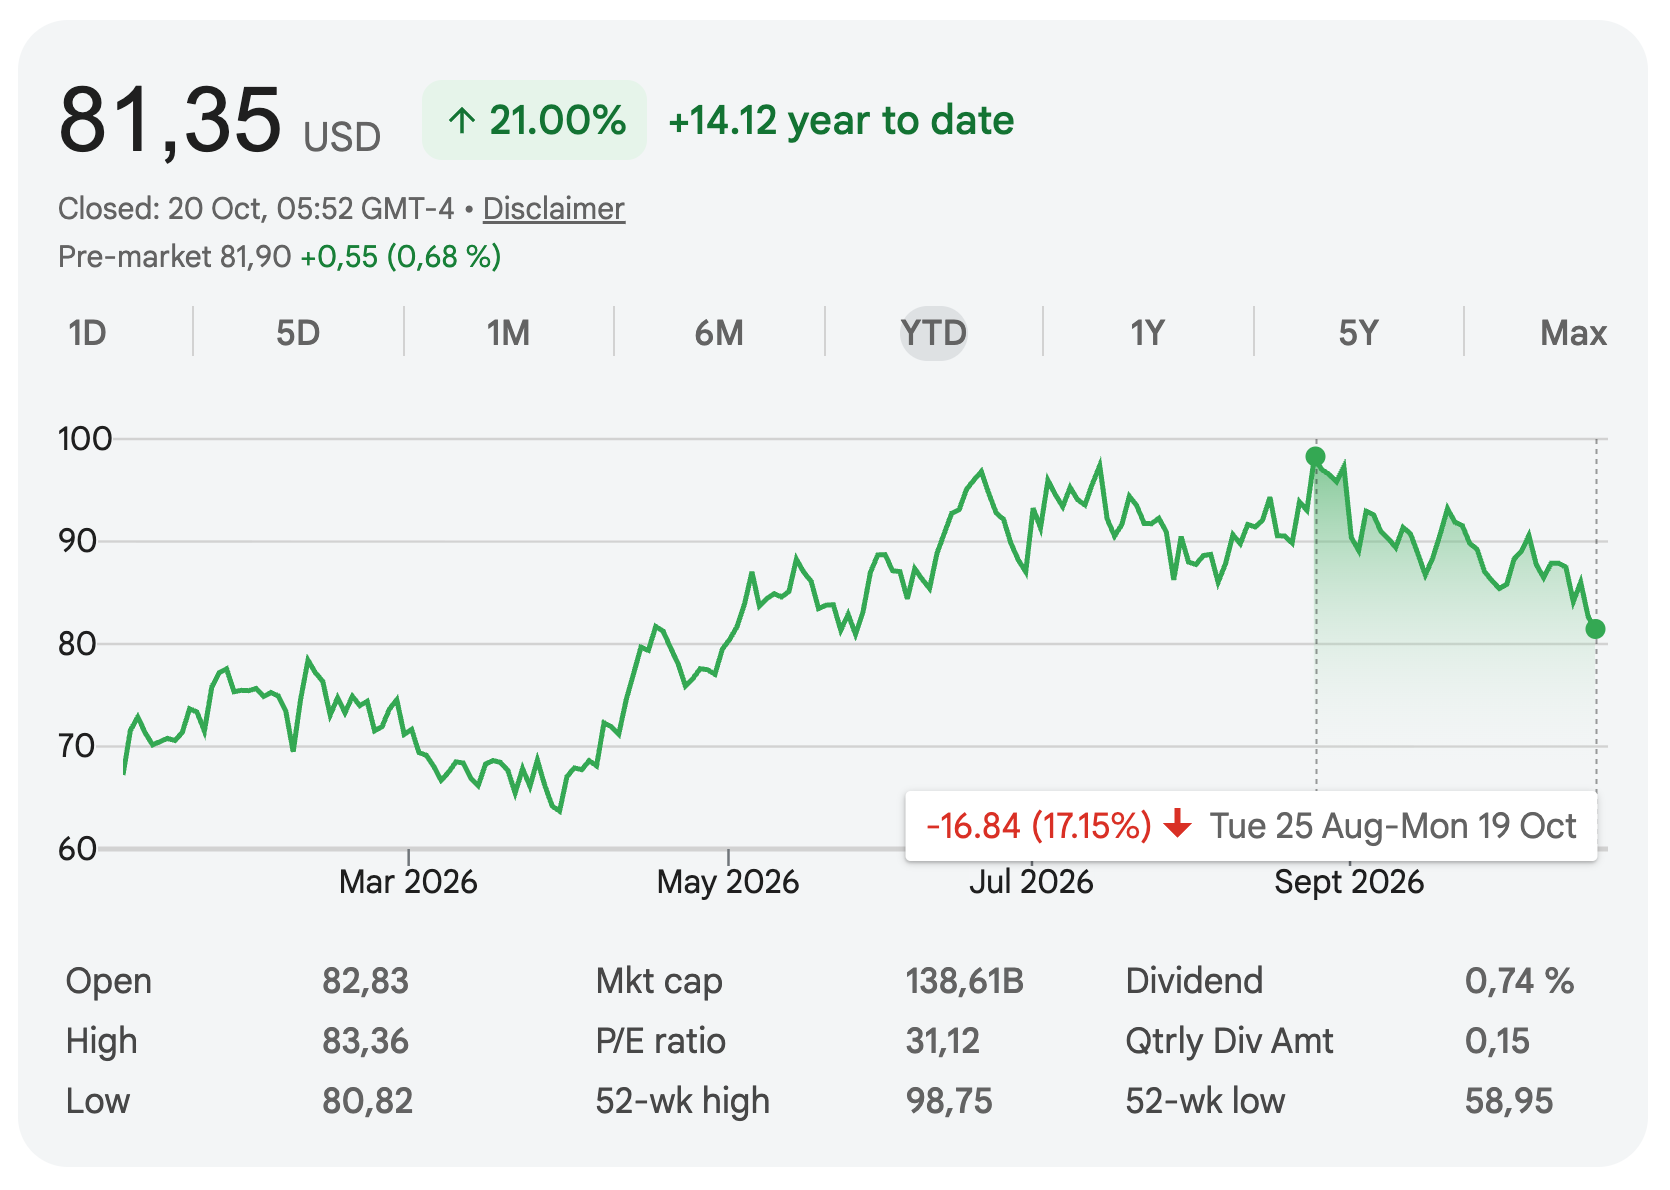
At the same time, I did something I hadn’t done since initiating the position in early 2024. I added to my IBKR position for the first time.
On the surface, those facts may seem to pull in opposite directions: a cooling business, a falling stock, and an investor buying more.
The rest of this post explains why I think they fit together. Before I get to the interesting parts, though, let me just very briefly walk you through the quarter itself.
Disclaimer:
As of the date of publication, the author OWNS SHARES in the company; but that may change. The analysis presented in this blog may be flawed and/or critical information may have been overlooked. The content provided should be considered an educational resource and should not be construed as individualized investment advice, nor as a recommendation to buy or sell specific securities. I may own some of the securities discussed. The stocks, funds, and assets discussed are examples only and may not be appropriate for your individual circumstances. It is the responsibility of the reader to do their own due diligence before investing in any index fund, ETF, asset, or stock mentioned or before making any sell decisions. Also double-check if the comments made are accurate. You should always consult with a financial advisor before purchasing a specific stock and making decisions regarding your portfolio.
The rest of this post is free. I only ask that you subscribe, which costs nothing and can be undone with a single click whenever you like. In return, you get every deep dive, earnings review and process piece I publish, straight to your inbox.